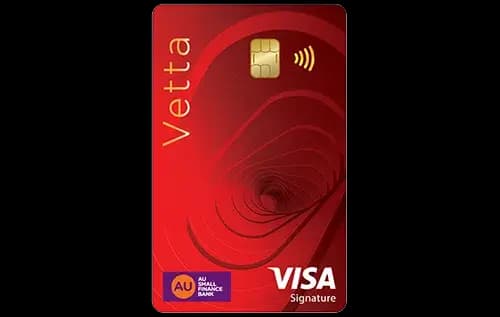
Quick Verdict
- The Vetta Credit Cardⓘ wins for everyday spending with a higher base reward rate and better category returns on online and dining spends.
- The SBI Prime Credit Cardⓘ offers more premium benefits like golf access and a complimentary Priority Pass membership, but Vetta also covers lounges well.
- Vetta is cheaper to hold if you can meet the higher waiver threshold of Rs 5 lakh annually compared to Rs 3 lakh for SBI Prime.
- Choose Vetta if you prioritize rewards on online, dining, and travel spends with a decent forex mark-up; pick SBI Prime if you want golf access, a lower waiver threshold, and complimentary club memberships.
Side by Side
| Detail | Vetta Credit Card | SBI Prime Credit Card |
|---|---|---|
| Annual fee | Rs 2,999 | Rs 2,999 |
| Joining fee | Rs 2,999 | Rs 2,999 |
| Fee waiver on spend | Rs 5.00 lakh | Rs 3.00 lakh |
| Reward rate | 1% base, 4% online & dining | 0.5% base, 2.5% dining, grocery & utilities |
| Reward type | points | points |
| Domestic lounge | 8 per year | 8 per year |
| International lounge | 4 per year | 4 per year |
| Forex markup | 1.99% | 3.5% |
| Best suited for | premium, rewards, lounge, dining, travel, shopping | rewards, dining, lounge, grocery, travel, shopping |
Rewards Compared
Spending Rs 10,000 on the Vetta Credit Cardⓘ earns you Rs 100 in rewards at its base rate. When spending is focused on online shopping or dining, the return jumps to Rs 400 for every Rs 10,000 spent, thanks to its attractive 4% category rate. This makes it highly rewarding for premium and frequent online shoppers and diners.
In comparison, the SBI Prime Credit Cardⓘ yields Rs 50 per Rs 10,000 at its base rate. However, it offers enhanced returns of Rs 250 per Rs 10,000 in dining, grocery, and utility bill spends with a 2.5% category reward rate. Therefore, SBI Prime is more beneficial for users who spend significantly in these categories but less rewarding on general spends.
Fees Compared
Both cards have a joining and annual fee of Rs 2,999. The fee waiver on the Vetta Credit Cardⓘ requires an annual spend of Rs 5 lakh, which translates to Rs 41,667 monthly. On the other hand, the SBI Prime Credit Cardⓘ demands a lower waiver threshold of Rs 3 lakh annually or Rs 25,000 monthly. The break-even spend to cover the annual fee at base rates is about Rs 3 lakh for Vetta, significantly lower than the Rs 6 lakh needed on SBI Prime, making Vetta easier to justify for users with higher spends.
Which One Should You Pick
The Vetta Credit Cardⓘ is ideal for premium users who can meet the higher spend threshold and want superior rewards on online and dining categories. Its lower forex markup of 1.99% and complimentary lounge access add to its appeal for frequent travelers. However, those who cannot meet the Rs 5 lakh annual spend might find it expensive to hold.
The SBI Prime Credit Cardⓘ suits users who prefer a lower spend requirement for fee waiver and want benefits like golf access and a complimentary Club ITC Silver Tier Membership. It is better for those who spend more on groceries, utilities, and dining but less on online categories. However, its higher forex markup at 3.5% makes it less attractive for international spenders.
In conclusion, if your spending patterns align with online and dining categories and you can meet the waiver spend, the Vetta Credit Cardⓘ is the more rewarding and cost-effective choice. If your spend is diversified with emphasis on groceries, utilities, and you seek premium lifestyle benefits, the SBI Prime Credit Cardⓘ may be a better fit.
What to Check Before You Apply
- Confirm if the category rates have caps or limits on maximum rewards earned.
- Check the redemption value and ease of converting points to vouchers or cash back.
- Understand the monthly spend needed to waive fees and whether it is realistic for your budget.
- Verify forex markup charges carefully if you frequently spend abroad.
- Review the number of domestic and international lounge visits allowed and any spend gates to access them.

Comments
No comments yet
Be the first to share your experience with this card.