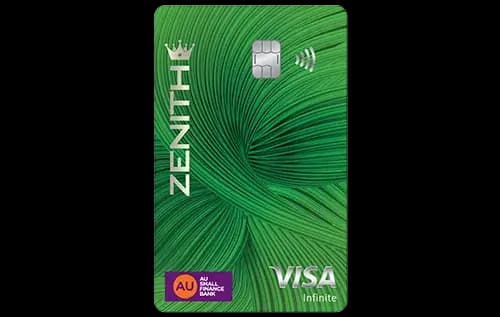
Quick Verdict
- The Zenith Credit Cardⓘ wins for everyday spend with a higher base reward rate of 1%, compared to 0.5% on the SBI Elite Credit Cardⓘ.
- Both cards offer excellent travel benefits and similar lounge access, making them neck-and-neck for travel and lounge perks.
- The SBI Elite Credit Cardⓘ is cheaper to hold, with a Rs 4,999 annual fee and a waiver on Rs 10 lakh annual spend, compared to Zenith’s Rs 7,999 fee without waiver.
- Choose Zenith if you prioritize rewards on dining and travel with premium perks; pick SBI Elite if you want a lower fee card with broad category rewards and added golf access.
Side by Side
| Detail | Zenith Credit Cardⓘ | SBI Elite Credit Cardⓘ |
|---|---|---|
| Annual fee | Rs 7,999 | Rs 4,999 |
| Joining fee | Rs 7,999 | Rs 4,999 |
| Fee waiver on spend | , | Rs 10.00 lakh annual |
| Reward rate | 1% base | 0.5% base |
| Reward type | points | points |
| Domestic lounge | 8 per year | 8 per year |
| International lounge | 6 per year | 6 per year |
| Forex markup | 1.99% | 1.99% |
| Best suited for | premium, travel, lounge, rewards, dining, shopping | travel, lounge, dining, rewards, shopping |
Rewards Compared
The Zenith Credit Cardⓘ offers a base reward rate of 1%, which translates to Rs 100 earned on Rs 10,000 spent. It excels in dining and travel categories with a 5% rate, yielding Rs 500 back on Rs 10,000 spend in these areas. Additionally, Zenith provides monthly milestone bonuses and birthday points, enhancing rewards for consistent spenders. This card targets premium users who spend heavily on travel and dining.
In contrast, the SBI Elite Credit Cardⓘ provides a base reward rate of 0.5%, resulting in Rs 50 back on Rs 10,000 spent. It offers a 2.5% reward rate on dining, grocery, and online spends, giving Rs 250 back per Rs 10,000 in these categories. While its base rate is lower, the SBI Elite covers a broader range of categories, making it suitable for diversified spending patterns. Its reward structure favors users who spend across multiple lifestyle categories including dining and shopping.
Fees Compared
The Zenith Credit Cardⓘ demands a steep joining and annual fee of Rs 7,999 each, with no fee waiver available regardless of spend. To justify its higher fee through base rewards alone, a cardholder would need to spend approximately Rs 7,99,900 annually. However, its category bonuses and premium benefits may offset this for high spenders.
The SBI Elite Credit Cardⓘ charges a lower joining and annual fee of Rs 4,999 each. Importantly, the annual fee is waived if the cardholder spends Rs 10 lakh annually, which breaks down to Rs 83,333 monthly. This waiver threshold makes it more accessible for those who can meet this spend target, effectively reducing the cost of holding the card. The break-even spend difference between the Zenith’s higher base rate and SBI Elite’s lower fee sits around Rs 6,00,000, meaning only very high spenders benefit from Zenith’s superior reward rate.
Which One Should You Pick
Choose the Zenith Credit Cardⓘ if you are a premium spender focused on travel and dining. Its higher reward rates in these categories and premium benefits like concierge service, milestone bonuses, and comprehensive protection covers make it ideal for users who seek luxury and extra perks. This card suits those who spend heavily and want to maximize rewards and lounge access with less concern for fee waiver calculations.
The SBI Elite Credit Cardⓘ is best for users who prefer a lower fee and more balanced rewards across dining, groceries, and online shopping. Its fee waiver on Rs 10 lakh annual spend makes it attractive for high but diversified spenders. Golf access is an added benefit for lifestyle seekers. This card is a solid choice if you want lounge access and travel perks but with a focus on broad category rewards and controlled fees.
In a decisive call, if your annual spend is below Rs 6 lakh or you want a card with fee waivers, pick the SBI Elite Credit Cardⓘ. If you are a premium traveler and diner willing to pay higher fees for better returns and perks, the Zenith Credit Cardⓘ is the winner. Avoid Zenith if you cannot meet high spend thresholds, and skip SBI Elite if you want top-tier rewards on travel and dining only.
What to Check Before You Apply
- Confirm the quarterly Rs 20,000 lounge spend gate on Zenith for free domestic lounge visits.
- Understand the redemption value and expiry rules of points on both cards.
- Calculate if your monthly spend meets SBI Elite’s Rs 83,333 fee waiver threshold.
- Check that the 1.99% forex markup applies equally abroad on both cards and consider your foreign currency spend.
- Verify lounge access locations and partner networks to ensure convenience for your travel routes.

Comments
No comments yet
Be the first to share your experience with this card.