Quick Verdict
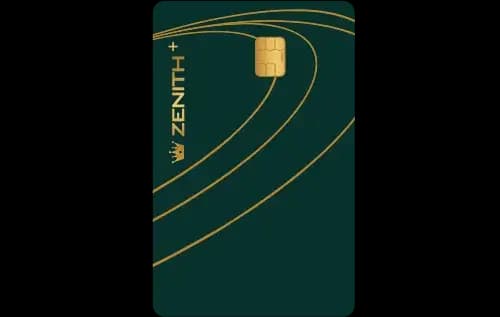
- For everyday spend, the Zenith Plus Credit Cardⓘ wins with higher category reward rates of 4% compared to HSBC’s 3%.
- For travel and lounge benefits, both offer similar domestic and international lounge access, but HSBC Travelone Credit Cardⓘ has a lower forex markup of 0.99%, making it better for international spending.
- Both cards charge the same joining and annual fee of Rs 4,999, but HSBC offers fee waiver on Rs 8 lakh annual spend, making it cheaper to hold for very high spenders.
- Pick Zenith Plusⓘ if you prioritise premium dining, online shopping rewards, and concierge services. Choose HSBC Traveloneⓘ if you want better forex rates, holiday booking discounts, and efficient air miles conversion.
Side by Side
| Detail | Zenith Plus Credit Cardⓘ | HSBC Travelone Credit Cardⓘ |
|---|---|---|
| Annual fee | Rs 4,999 | Rs 4,999 |
| Joining fee | Rs 4,999 | Rs 4,999 |
| Fee waiver on spend | Rs 8.00 lakh | |
| Reward rate | 1% base, 4% dining, travel, online | 1% base, 3% dining, travel |
| Reward type | points | points |
| Domestic lounge | 8 per year | 8 per year |
| International lounge | 6 per year | 6 per year |
| Forex markup | 1.99% | 0.99% |
| Best suited for | premium, travel, lounge, rewards, dining, shopping | travel, rewards, lounge, forex, shopping |
Rewards Compared
The Zenith Plus Credit Cardⓘ offers a base reward rate of 1%, which means Rs 100 back on Rs 10,000 spent. It shines in its category rates, offering 4% returns or Rs 400 on Rs 10,000 spent in dining, travel, and online categories. This makes it highly attractive for premium spenders who frequently dine out or shop online.
The HSBC Travelone Credit Cardⓘ also has a base reward rate of 1%, equating to Rs 100 on Rs 10,000 spent. However, its category rewards are slightly lower at 3% for travel and dining, yielding Rs 300 on Rs 10,000 in these categories. HSBC’s strength lies in travel-centric perks and efficient conversion of points to air miles, appealing to frequent travellers who prioritise flexible redemption.
Fees Compared
Both cards charge an identical joining fee and annual fee of Rs 4,999. However, only the HSBC Travelone Credit Cardⓘ offers a fee waiver on spending Rs 8 lakh annually, which translates to about Rs 66,667 per month. This waiver is beneficial for very high spenders who can offset the fees entirely. The Zenith Plus Credit Cardⓘ does not specify any fee waiver, meaning the Rs 4,999 fee is unavoidable. Both cards require roughly Rs 5 lakh spend to cover the fee through base reward earnings alone, so casual spenders should consider whether the benefits justify the cost.
Which One Should You Pick
Choose the Zenith Plus Credit Cardⓘ if you are a premium user who values higher returns on dining, travel, and online categories, along with perks like concierge service, golf access, and Taj Epicure membership. Its comprehensive lounge access and welcome benefit of luxury gift vouchers or points worth Rs 5,000 add to its appeal for lifestyle-focused cardholders. Skip this card if you tend to spend less than Rs 5 lakh annually or want better forex savings.
Opt for the HSBC Travelone Credit Cardⓘ if you are an avid traveller who frequently spends abroad, thanks to its low forex markup of 0.99%, and if you can meet the Rs 8 lakh annual spend for fee waiver. Its discounts on holiday bookings, purchase protection, and instant reward-to-air miles conversion make it suitable for globetrotters. Avoid HSBC if you do not spend enough to justify the fees or want higher category reward rates on dining and online.
Overall, the Zenith Plus Credit Cardⓘ is better for premium everyday rewards and lifestyle benefits, while HSBC Travelone Credit Cardⓘ offers more value for travel and forex-savvy users willing to spend heavily. The final choice depends on your spending patterns and priorities.
What to Check Before You Apply
- Confirm the exact lounge access count and whether any visits carry extra fees.
- Understand redemption terms for points and vouchers, especially the value you get per point.
- Calculate if you can realistically meet the fee waiver threshold on HSBC Travelone Credit Cardⓘ.
- Consider the forex markup difference carefully if you frequently transact abroad; HSBC’s 0.99% is significantly lower than Zenith Plus’s 1.99%.
- Check if golf access, concierge, and other premium benefits align with your lifestyle to justify the fees.

Comments
No comments yet
Be the first to share your experience with this card.