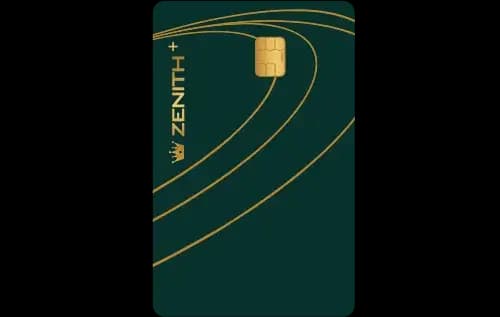
Quick Verdict
- For everyday spending, the Marriott Bonvoy HDFC Bank Credit Cardⓘ wins with a higher base reward rate of 1.3% compared to 1% on the Zenith Plus.
- For travel benefits and lounge access, the Zenith Plus Credit Cardⓘ offers a wider range of premium perks including more complimentary lounges and a lower forex markup, making it the travel-friendly choice.
- The Marriott Bonvoy card is cheaper to hold at Rs 3,000 annual and joining fees versus Rs 4,999 each on the Zenith Plus.
- Choose the Marriott Bonvoy HDFC if you want more base rewards and a lower fee card; pick Zenith Plus if you value premium travel benefits, lounges, and a lower forex cost despite its higher fees.
Side by Side
| Detail | Zenith Plus Credit Cardⓘ | Marriott Bonvoy HDFC Bank Credit Cardⓘ |
|---|---|---|
| Annual fee | Rs 4,999 | Rs 3,000 |
| Joining fee | Rs 4,999 | Rs 3,000 |
| Fee waiver on spend | None specified | None specified |
| Reward rate | 1% base, 4% dining, travel, online | 1.3% base, 2.6% dining, travel |
| Reward type | points | points |
| Domestic lounge | 8 per year | 12 per year |
| International lounge | 6 per year | 12 per year |
| Forex markup | 1.99% | 3.5% |
| Best suited for | premium, travel, lounge, rewards, dining, shopping | travel, premium, lounge, rewards, shopping |
Rewards Compared
On a Rs 10,000 spend, the Zenith Plus Credit Cardⓘ earns Rs 100 back at the base rate. However, spend on dining, travel, or online categories yields Rs 400 back, reflecting its 4% category reward rate. This makes it highly rewarding for targeted spends in these categories. In comparison, the Marriott Bonvoy HDFC Bank Credit Cardⓘ provides Rs 130 back at the base level, which already outperforms Zenith Plus’s base earn rate. In its dining and travel categories, it returns Rs 260, which is notably less than Zenith Plus’s 4% but still substantial.
This means Marriott Bonvoy is better for general spenders who want solid returns without category restrictions, while Zenith Plus offers strong rewards for diners and travelers who can maximize category bonuses. Neither card specifies rewards for shopping outside these categories, but Zenith Plus’s extensive category bonus could be a bigger draw for lifestyle spenders.
Fees Compared
The Zenith Plus charges Rs 4,999 as both joining and annual fee, with no stated waiver threshold. This means the cardholder pays Rs 4,999 upfront and yearly regardless of spend. The Marriott Bonvoy card is significantly cheaper at Rs 3,000 joining and Rs 3,000 annual fee. Neither card explicitly mentions fee waivers on annual spend, so the fees are effectively fixed.
Looking at break-even spends, Zenith Plus requires about Rs 4,99,900 in annual spend just to cover its fee from base rewards alone, while Marriott Bonvoy needs around Rs 2,30,769. This confirms that Marriott Bonvoy provides better value for moderate to high spenders, whereas Zenith Plus needs very high spending or selective category use to justify its higher fees.
Which One Should You Pick
If you prioritize premium travel benefits, such as personalized airport meet-and-assist, Taj Epicure Membership, more international lounge visits, and a lower forex markup of 1.99%, the Zenith Plus Credit Cardⓘ is the clear choice. It suits heavy travelers and lifestyle consumers who will make full use of these perks despite the higher fees. Also, its 4% rewards on dining, travel, and online spend make it attractive for category-focused users.
On the other hand, if you want a card with a lower annual cost, better base rewards of 1.3%, and more frequent lounge access domestically and internationally, the Marriott Bonvoy HDFC Bank Credit Cardⓘ fits well. It is ideal for moderate spenders who want consistent rewards and benefits on travel and dining without the need to hit very high spend thresholds.
In conclusion, the Marriott Bonvoy card is better for everyday use and moderate spenders. Zenith Plus is better for premium, high-frequency travelers and category spenders who can extract value from its perks. Those unwilling to pay high fees should skip Zenith Plus, while reward maximizers on a budget should skip Marriott Bonvoy.
What to Check Before You Apply
- Confirm if any caps or limits apply to the 4% category rewards on Zenith Plus or the 2.6% on Marriott Bonvoy.
- Check the actual redemption value of points as both cards use points, but value can vary widely.
- Verify the exact monthly spend required to waive fees, if any, since neither card specifies fee waiver conditions clearly.
- Consider the forex markup rates carefully if you plan significant foreign spending, Zenith Plus’s 1.99% is much lower than Marriott Bonvoy’s 3.5%.
- Review which airport lounges are accessible and whether the lounges align with your typical travel routes.

Comments
No comments yet
Be the first to share your experience with this card.