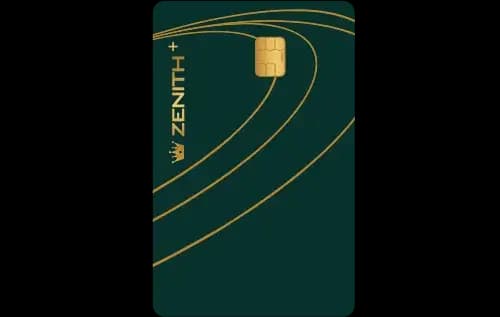
Quick Verdict
- For everyday spend, the Standard Chartered Ultimate Credit Cardⓘ wins with a higher base reward rate of 3.33% compared to 1% on the Zenith Plus.
- For travel and lounge benefits, the Zenith Plus Credit Cardⓘ offers more international lounge visits and premium perks like Taj Epicure Membership and personalized airport services.
- Both cards have similar annual fees around Rs 5,000, but the Ultimate card’s higher rewards rate means it breaks even on fees at a much lower spend.
- Choose the Zenith Plus if you prioritize luxury travel benefits and lounge access; pick the Standard Chartered Ultimate for superior rewards on everyday and shopping spends.
Side by Side
| Detail | Zenith Plus Credit Card ⓘ | Standard Chartered Ultimate Credit Card ⓘ |
|---|---|---|
| Annual fee | Rs 4,999 | Rs 5,000 |
| Joining fee | Rs 4,999 | Rs 5,000 |
| Fee waiver on spend | Not recorded | Not recorded |
| Reward rate | 1% base, 4% on dining, travel, online | 3.33% base |
| Reward type | Points | Points |
| Domestic lounge | 8 per year | 8 per year |
| International lounge | 6 per year | 4 per year |
| Forex markup | 1.99% | 2% |
| Best suited for | Premium, travel, lounge, rewards, dining, shopping | Rewards, travel, lounge, premium, shopping |
Rewards Compared
Spending Rs 10,000 on the Zenith Plus Credit Cardⓘ earns Rs 100 back at the base rate of 1%. However, if you spend in dining, travel, or online categories, the effective return jumps to Rs 400 per Rs 10,000, reflecting a 4% reward rate. This makes it attractive for premium spenders focused on these categories.
In contrast, the Standard Chartered Ultimate Credit Cardⓘ delivers a flat 3.33% base reward rate, translating to Rs 333 per Rs 10,000 spent across all categories. This higher baseline rewards all spending more generously, especially outside the Zenith Plus’s bonus categories. For general everyday purchases and shopping, the Ultimate card clearly offers better value.
Fees Compared
The Zenith Plus charges an annual fee and joining fee of Rs 4,999 each, while the Standard Chartered Ultimate has a slightly higher fee of Rs 5,000 for both. Neither card specifies a fee waiver threshold based on spend, so these fees are effectively fixed costs.
Looking at the break-even points, the Zenith Plus requires a very high spend of about Rs 4,99,900 annually to cover its fee at the base reward rate. The Ultimate card breaks even much earlier at Rs 1,50,150 due to its superior 3.33% base rate. The extra Rs 1 in annual fee for the Ultimate card is negligible compared to the rewards advantage it offers.
Which One Should You Pick
Choose the Zenith Plus Credit Cardⓘ if you are a premium traveler who values luxury perks such as Taj Epicure Membership, personalized airport services, and more international lounge visits. Its 4% rewards on dining, travel, and online categories also benefit focused spenders in these areas. However, the high break-even spend means it suits those with substantial annual expenses.
The Standard Chartered Ultimate Credit Cardⓘ is ideal for those who want a strong flat rewards rate on all spends without worrying about categories. Its lower break-even spend and generous welcome benefits make it a better fit for everyday users and shoppers seeking consistent cashback. The card’s insurance and family supplementary card benefits add further value.
In summary, premium travel and category-focused spenders should pick the Zenith Plus, while general spenders and shopping enthusiasts will find the Ultimate card more rewarding. Those with low annual spends should skip the Zenith Plus due to its high break-even, and those uninterested in premium travel perks may find the Ultimate card a simpler, more rewarding choice.
What to Check Before You Apply
- Verify any caps on category rewards, especially the 4% rates on Zenith Plus.
- Confirm the redemption value and ease of converting points to vouchers or cashback.
- Understand the fee waiver math if any, as neither card clearly offers it.
- Check forex markup carefully if you travel abroad frequently; Zenith Plus has a slightly lower rate.
- Review the list of domestic and international lounges accessible and their partner airports.

Comments
No comments yet
Be the first to share your experience with this card.