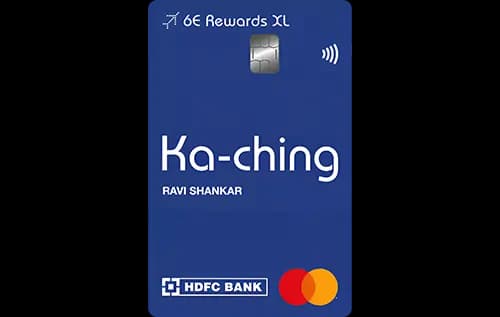
Quick Verdict
- The Ashva Credit Cardⓘ wins for everyday spend with a higher base reward rate of 1.25% compared to 1% on the 6E Rewards XL IndiGo HDFC Bank Credit Cardⓘ.
- For travel and lounge benefits, 6E Rewards XL IndiGo HDFC Bank Credit Cardⓘ excels in domestic lounge access and IndiGo flight-related perks, while Ashva Credit Cardⓘ offers international lounge access and more premium benefits including hotel stays and concierge.
- The 6E Rewards XL IndiGo card is significantly cheaper to hold with Rs 1,500 annual and joining fees versus Rs 2,999 each on the Ashva Credit Cardⓘ.
- Frequent domestic travelers and IndiGo flyers should pick the 6E Rewards XL IndiGo HDFC Bank Credit Cardⓘ, whereas premium travelers seeking international lounge access and luxury perks will prefer the Ashva Credit Cardⓘ.
Side by Side
| Detail | 6E Rewards XL IndiGo HDFC Bank Credit Cardⓘ | Ashva Credit Cardⓘ |
|---|---|---|
| Annual fee | Rs 1,500 | Rs 2,999 |
| Joining fee | Rs 1,500 | Rs 2,999 |
| Fee waiver on spend | ||
| Reward rate | 1% base | 1.25% base |
| Reward type | points | points |
| Domestic lounge | 8 per year | 8 per year |
| International lounge | None | 4 per year |
| Forex markup | 3.5% | 1.5% |
| Best suited for | travel, lounge, rewards, fuel | premium, travel, lounge, rewards, shopping |
Rewards Compared
On a base spend of Rs 10,000, the 6E Rewards XL IndiGo HDFC Bank Credit Cardⓘ earns Rs 100 in rewards at its 1% base reward rate. However, it significantly increases returns on specific categories such as travel, dining, and grocery to 5%, 2.5%, and 2.5% respectively. This means Rs 500 back on travel spends and Rs 250 on dining and grocery per Rs 10,000 spent. This makes the 6E card highly rewarding for domestic travel and related expenses, especially for IndiGo flyers due to additional 5% rewards on IndiGo spends.
The Ashva Credit Cardⓘ offers a higher base reward rate of 1.25%, resulting in Rs 125 back on every Rs 10,000 spent. Its category rates are uniform at 2.5% for both travel and dining, providing Rs 250 back per Rs 10,000. While it does not reward grocery spending extra, its elevated base rate makes it better for general everyday use. The Ashva card’s rewards are more balanced for premium travelers who spend across travel and dining but less focused on grocery or fuel categories.
Fees Compared
The 6E Rewards XL IndiGo HDFC Bank Credit Cardⓘ charges Rs 1,500 as both joining and annual fees. There is no specified fee waiver on spend, meaning the fees are fixed. The card’s break-even on base rewards alone requires an annual spend of about Rs 1,50,000 to cover the Rs 1,500 annual fee through its 1% base reward.
The Ashva Credit Cardⓘ is more expensive with Rs 2,999 joining and annual fees. It also lacks a fee waiver threshold. Due to its higher 1.25% base reward rate, the break-even on base rewards to cover its Rs 2,999 annual fee is approximately Rs 2,39,920 annually. However, the Ashva card demands Rs 1,499 extra in fees compared to the 6E card, and to justify this by rewards alone would require an additional Rs 5,99,600 in spend, making it worthwhile only for very high spenders or those valuing premium benefits.
Which One Should You Pick
Choose the 6E Rewards XL IndiGo HDFC Bank Credit Cardⓘ if you are a frequent domestic traveler, especially with IndiGo Airlines, or if you want a cost-effective card with good rewards on travel, dining, and groceries. Its lower fees and complimentary IndiGo benefits make it ideal for value-conscious travelers focused on domestic trips and fuel spends.
Pick the Ashva Credit Cardⓘ if you are a premium user who values international lounge access, luxury hotel benefits, concierge services, and a higher base reward rate. Its better forex markup and broad travel perks suit international travelers and those wanting premium lifestyle privileges, despite the higher fees.
Skip the 6E Rewards XL IndiGo card if you primarily spend abroad or need international lounge access. Avoid the Ashva Credit Card if your annual spend is below Rs 2.4 lakh or you are not interested in premium perks, as the high fees may not justify the rewards.
What to Check Before You Apply
- Confirm if the 6E card’s welcome flight ticket aligns with your travel plans and if the 6E Prime Add-On is valuable to you.
- Review caps or limits on category rewards for both cards, especially for the high 5% travel rewards on the 6E card.
- Calculate your monthly spend to see if you cross the fee waiver or break-even thresholds, especially given the high fees of the Ashva card.
- Note the forex markup differences: 3.5% on 6E card vs 1.5% on Ashva card can significantly impact foreign currency spends.
- Check the airport lounge locations and gate access to ensure they match your typical travel routes.

Comments
No comments yet
Be the first to share your experience with this card.