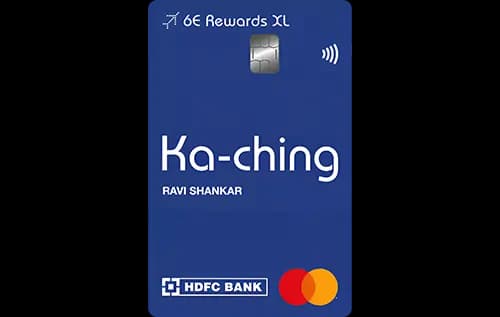
Quick Verdict
- The 6E Rewards XL IndiGo HDFC Bank Credit Cardⓘ wins for everyday spend with a higher base reward rate of 1% versus 0.8% on the Axis Bank Privilege Credit Cardⓘ.
- For travel and lounges, both cards offer 8 domestic lounge visits annually but the Axis Bank Privilege Credit Cardⓘ adds Mastercard-affiliated lounges and a quarterly spend gate, catering better to frequent domestic travelers.
- Both cards have the same joining and annual fees of Rs 1,500, but the Axis Bank Privilege Credit Cardⓘ offers a fee waiver on Rs 2.5 lakh annual spend, making it cheaper to hold for high spenders.
- Choose the 6E Rewards XL IndiGo HDFC Bank Credit Cardⓘ if you are a frequent IndiGo flyer or want stronger rewards in travel, dining, and grocery. Pick the Axis Bank Privilege Credit Cardⓘ if you want a more versatile rewards program with lounge access flexibility and a fee waiver on higher spend.
Side by Side
| Detail | 6E Rewards XL IndiGo HDFC Bank Credit Cardⓘ | Axis Bank Privilege Credit Cardⓘ |
|---|---|---|
| Annual fee | Rs 1,500 | Rs 1,500 |
| Joining fee | Rs 1,500 | Rs 1,500 |
| Fee waiver on spend | Rs 2.50 lakh | |
| Reward rate | 1% | 0.8% |
| Reward type | points | points |
| Domestic lounge | 8 per year | 8 per year |
| International lounge | None | None |
| Forex markup | 3.5% | 3.5% |
| Best suited for | travel, lounge, rewards, fuel | rewards, lounge, first-card, travel, shopping |
Rewards Compared
The 6E Rewards XL IndiGo HDFC Bank Credit Cardⓘ offers a base reward rate of 1%, which means you earn Rs 100 back on every Rs 10,000 spent. This base rate is stronger than the Axis Bank Privilege Credit Cardⓘ’s 0.8% base rate, which yields Rs 80 per Rs 10,000 spent. Where the IndiGo card truly shines is in category-specific rewards: 5% on travel spends (Rs 500 per Rs 10,000), and 2.5% on dining and grocery spends (Rs 250 per Rs 10,000). These elevated rates make it highly rewarding for those who spend heavily on travel, dining out, or groceries.
On the other hand, the Axis Bank Privilege Credit Cardⓘ offers a 2% rate on online spends, which translates to Rs 200 per Rs 10,000, but lacks the enhanced category multipliers for travel, dining, and grocery seen on the IndiGo card. This makes it less lucrative for category-specific rewards but still provides a decent base earning on all spends. Overall, for pure reward accumulation especially in travel and dining, the IndiGo card is the clear winner.
Fees Compared
Both cards charge a joining fee and annual fee of Rs 1,500 each. However, only the Axis Bank Privilege Credit Cardⓘ provides an annual fee waiver if you spend Rs 2.5 lakh or more in a year. This equates to spending roughly Rs 20,833 per month to avoid the fee, which is a substantial but achievable target for regular spenders. The 6E Rewards XL IndiGo HDFC Bank Credit Cardⓘ does not offer any fee waiver on spending, so cardholders must weigh the Rs 1,500 annual cost against their reward earnings.
The break-even spend for the IndiGo card to cover its fee based on base rewards alone is Rs 1,50,000 annually, whereas for the Axis Bank Privilege Credit Cardⓘ it is slightly higher at Rs 1,87,500. Those who spend below these thresholds will effectively pay a higher cost per reward earned. Hence, if you do not meet the waiver threshold on the Axis card, you may pay similar or higher fees compared to the IndiGo card.
Which One Should You Pick
Choose the 6E Rewards XL IndiGo HDFC Bank Credit Cardⓘ if you frequently fly IndiGo, spend heavily on travel, dining, or groceries, and want a simple but rewarding program without the need to meet a high waiver spend. The complimentary IndiGo flight ticket worth Rs 3,000 and 6E Prime add-on add tangible value for loyal flyers. However, skip this card if you want international lounge access or a fee waiver linked to spending.
The Axis Bank Privilege Credit Cardⓘ suits shoppers and travelers who spend at least Rs 2.5 lakh annually and want access to Mastercard-affiliated lounges with a quarterly spending gate. Its welcome benefits and fee waiver on Rs 2.5 lakh spend make it attractive for higher spenders who want to keep fees low. Avoid this card if your spend is irregular or below the waiver threshold, as the effective cost then rises.
In conclusion, frequent IndiGo travelers and category spenders will prefer the 6E Rewards XL IndiGo HDFC Bank Credit Cardⓘ for its superior rewards and benefits. Meanwhile, higher spenders who value lounge access flexibility and fee waivers should opt for the Axis Bank Privilege Credit Cardⓘ.
What to Check Before You Apply
- Confirm the quarterly spend gate of Rs 50,000 for domestic lounge access on the Axis Bank Privilege Credit Cardⓘ to avoid surprise restrictions.
- Check any caps or limits on category rewards, especially on the IndiGo card’s 5% travel rewards.
- Understand the redemption value of points as the cards earn points, not direct cashback.
- Factor in the 3.5% forex markup when planning international travel spends.
- Verify the availability of domestic lounges and their locations to ensure convenient access.

Comments
No comments yet
Be the first to share your experience with this card.