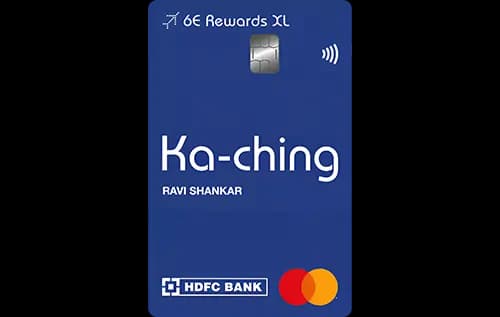
Quick Verdict
- For everyday spend, the 6E Rewards XL IndiGo HDFC Bank Credit Cardⓘ wins with a 1% base reward rate compared to 0.7% on the Eazydiner Indusind Bank Credit Cardⓘ.
- For dining and travel categories, the Eazydiner Indusind Bank Credit Cardⓘ offers a superior 10% return on dining spends, making it the better pick for food lovers.
- The 6E Rewards XL IndiGo card is cheaper to hold with a Rs 1,500 annual fee and a lower joining fee, while the Eazydiner card charges Rs 2,999 for both and requires Rs 2 lakh annual spend for fee waiver.
- Choose the 6E Rewards XL IndiGo cardⓘ if you prioritize travel rewards and domestic lounge access; pick the Eazydiner cardⓘ if you want maximum dining discounts and are a frequent restaurant-goer willing to meet the higher fee waiver threshold.
Side by Side
| Detail | 6E Rewards XL IndiGo HDFC Bank Credit Cardⓘ | Eazydiner Indusind Bank Credit Cardⓘ |
|---|---|---|
| Annual fee | Rs 1,500 | Rs 2,999 |
| Joining fee | Rs 1,500 | Rs 2,999 |
| Fee waiver on spend | Not recorded | Rs 2.00 lakh |
| Reward rate | 1% base, 5% travel, 2.5% dining, 2.5% grocery | 0.7% base, 10% dining |
| Reward type | points | points |
| Domestic lounge | 8 per year | 4 per year |
| International lounge | None | None |
| Forex markup | 3.5% | 3.5% |
| Best suited for | travel, lounge, rewards, fuel | dining, rewards, lounge, travel |
Rewards Compared
Spending Rs 10,000 on the 6E Rewards XL IndiGo HDFC Bank Credit Cardⓘ earns Rs 100 back at the base rate. However, this card shines in travel spends where the effective reward rate is 5%, yielding Rs 500 back on Rs 10,000 spent. Dining and groceries also return 2.5%, or Rs 250 for every Rs 10,000, making it a versatile card for multiple categories.
On the other hand, the Eazydiner Indusind Bank Credit Cardⓘ returns Rs 70 on Rs 10,000 at its base rate, which is noticeably lower. But in dining, it rewards a massive 10%, equating to Rs 1,000 on Rs 10,000 spent, which is double what the 6E Rewards XL card offers. This makes the Eazydiner card particularly lucrative for heavy dining spenders. Outside of dining, the Eazydiner card’s reward rate drops significantly, so it is less suited for broad everyday use.
Fees Compared
The 6E Rewards XL IndiGo HDFC Bank Credit Cardⓘ demands a joining fee and annual fee of Rs 1,500 each, with no fee waiver listed. The break-even spend for its base reward rate to cover the annual fee is about Rs 1,50,000.
The Eazydiner Indusind Bank Credit Cardⓘ charges a higher joining and annual fee of Rs 2,999 each. However, this fee can be waived by spending Rs 2 lakh annually, which translates to Rs 16,667 per month. The break-even spend for the base rate rewards to cover the fee is much higher at Rs 4,28,429, reflecting its lower base reward rate.
For users not meeting the Rs 2 lakh annual spend, the Eazydiner card’s higher fees may not be justified unless dining rewards are heavily utilized.
Which One Should You Pick
Pick the 6E Rewards XL IndiGo HDFC Bank Credit Cardⓘ if you frequently travel with IndiGo, want multiple domestic lounge accesses, and desire a reasonable rewards rate on travel, groceries, and fuel. It is also suitable if you prefer a lower fee and do not want to worry about fee waivers.
Choose the Eazydiner Indusind Bank Credit Cardⓘ if dining out is a major part of your spend and you can easily meet the Rs 2 lakh annual spend to waive the fees. The generous 10% dining rewards and complementary EazyDiner Prime membership add strong value for food enthusiasts and those who dine frequently at premium restaurants.
Overall, the 6E Rewards XL IndiGo cardⓘ is a better all-rounder for travel and general use, while the Eazydiner cardⓘ is a niche card excelling for premium dining spenders who meet the higher spend threshold. If you do not travel or dine out often, skip the Eazydiner card due to its high fees and lower base rewards. Conversely, if dining is not your priority, the 6E Rewards XL cardⓘ offers more balanced rewards and benefits.
What to Check Before You Apply
- Confirm the reward caps on dining and travel categories as some cards limit maximum rewards.
- Check the actual redemption value and ease for points earned, especially for third-party sourced rewards.
- Calculate fee waiver feasibility carefully based on your average monthly spend to avoid paying high fees unnecessarily.
- Be aware of the 3.5% forex markup on foreign currency spends which applies equally to both cards.
- Verify the domestic lounge network and access rules, as 6E Rewards XL offers 8 visits per year but no international lounges.

Comments
No comments yet
Be the first to share your experience with this card.