Quick Verdict
- The HDFC Bank UPI Rupay Credit Cardⓘ wins for everyday spend with a higher base cashback rate and better category returns.
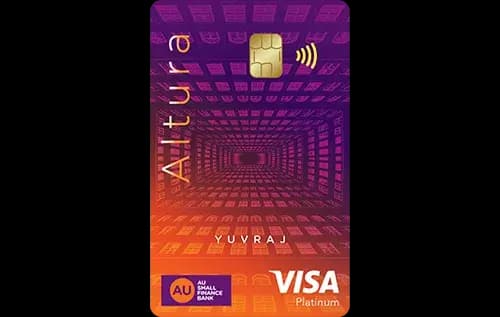
- The Altura Credit Cardⓘ offers domestic lounge access, making it preferable for occasional lounge users.
- The HDFC card is cheaper to hold with a lower joining and annual fee and no waiver threshold.
- Pick the Altura cardⓘ if you want lounge access and shop heavily in groceries and utilities; choose the HDFC cardⓘ for better cashback on groceries, dining, and UPI spends with minimal fees.
Side by Side
| Detail | Altura Credit Cardⓘ | HDFC Bank UPI Rupay Credit Cardⓘ |
|---|---|---|
| Annual fee | Rs 199 | Rs 99 |
| Joining fee | Rs 199 | Rs 99 |
| Fee waiver on spend | Rs 1.00 lakh | None |
| Reward rate | 0.5% base | 1% base |
| Reward type | Cashback | Cashback |
| Grocery category rate | 2% | 3% |
| Utilities category rate | 2% | Not recorded |
| Dining category rate | Not recorded | 3% |
| UPI category rate | Not recorded | 1% |
| Domestic lounge | 2 per year (Rs 60,000 quarterly spend gate) | None |
| International lounge | None | None |
| Forex markup | 3.5% | 3.5% |
| Best suited for | Cashback, first-card, UPI-Rupay, shopping | UPI-Rupay, lifetime-free, cashback, first-card, shopping |
Rewards Compared
On a Rs 10,000 spend, the Altura Credit Cardⓘ returns Rs 50 at its base rate, rising to Rs 200 when spent in groceries or utilities. This makes it a decent cashback card for those categories but less rewarding outside them. In contrast, the HDFC Bank UPI Rupay Credit Cardⓘ doubles the base cashback to Rs 100 per Rs 10,000 spent, with even more attractive 3% returns in groceries and dining, equating to Rs 300 back. It also provides 1% cashback on UPI spends, which is a unique category for the HDFC cardⓘ. Overall, the HDFC cardⓘ offers stronger rewards across more categories, making it more versatile for everyday spenders.
Fees Compared
The Altura cardⓘ charges Rs 199 for both joining and annual fees, which can be waived if you spend Rs 1,00,000 annually or about Rs 8,333 monthly. The break-even spend to cover the fee at the base rate is Rs 39,800, but this reduces with category spends. The HDFC cardⓘ is more affordable with Rs 99 joining and annual fees and no waiver condition, effectively making it lifetime free if you consider the low fee. The HDFC cardⓘ also requires only Rs 9,900 spend at base rate to cover its fee, making it easier to justify for low spenders. Both cards have a 3.5% forex markup, which is standard but costly for foreign currency transactions.
Which One Should You Pick
Choose the Altura Credit Cardⓘ if you value domestic lounge access and spend heavily on groceries and utilities. It suits first-time credit card users who want a simple cashback structure with some lounge perks. However, be prepared to meet the Rs 1,00,000 annual spend to waive fees and unlock full value.
The HDFC Bank UPI Rupay Credit Cardⓘ is ideal for those seeking a low-cost, lifetime-free card with solid cashback on groceries, dining, and UPI payments. It is well suited for everyday spenders who want straightforward rewards without worrying about fee waivers or lounge access.
In conclusion, the HDFC cardⓘ is the better all-rounder for cashback and cost-conscious users, while the Altura cardⓘ appeals to shoppers wanting lounge access and category-specific rewards. Skip the Altura cardⓘ if you do not spend enough to waive fees or need lounge benefits. Skip the HDFC cardⓘ if you prioritize lounge access or utilities cashback.
What to Check Before You Apply
- Confirm the quarterly Rs 60,000 spend gate for domestic lounges on the Altura cardⓘ.
- Check if your typical spends fall into the specified categories to maximize rewards.
- Understand the fee waiver threshold on the Altura cardⓘ and calculate if your spend justifies it.
- Beware of the 3.5% forex markup on both cards if you travel or shop abroad.
- Verify the availability of lounges at airports you frequent for the Altura cardⓘ.

Comments
No comments yet
Be the first to share your experience with this card.