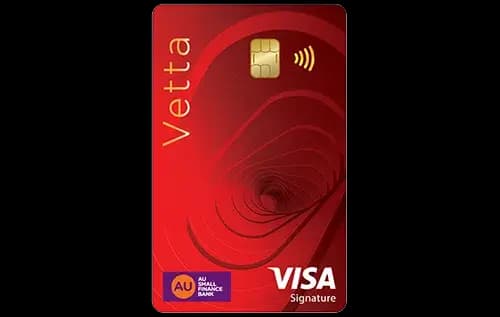
Quick Verdict
- The Vetta Credit Card ⓘ wins for dining and online spends with a higher 4% reward rate versus 3% on the HSBC Travelone Credit Card ⓘ.
- The HSBC Travelone Credit Card ⓘ offers better value for travel and forex transactions, including a lower 0.99% forex markup and more international lounge access.
- Vetta Credit Card ⓘ is cheaper to hold with an annual fee of Rs 2,999 versus Rs 4,999 on the HSBC Travelone ⓘ, and it has a lower waiver spend threshold.
- Pick Vetta Credit Card ⓘ if you prioritize dining rewards and premium lounge experiences domestically; go for HSBC Travelone Credit Card ⓘ if you travel internationally often and want better forex rates.
Side by Side
| Detail | Vetta Credit Card ⓘ | HSBC Travelone Credit Card ⓘ |
|---|---|---|
| Annual fee | Rs 2,999 | Rs 4,999 |
| Joining fee | Rs 2,999 | Rs 4,999 |
| Fee waiver on spend | Rs 5.00 lakh | Rs 8.00 lakh |
| Reward rate | 1% base; 4% online, dining | 1% base; 3% travel, dining |
| Reward type | points | points |
| Domestic lounge | 8 per year | 8 per year |
| International lounge | 4 per year | 6 per year |
| Forex markup | 1.99% | 0.99% |
| Best suited for | premium, rewards, lounge, dining, travel, shopping | travel, rewards, lounge, forex, shopping |
Rewards Compared
On a Rs 10,000 monthly spend, the Vetta Credit Card ⓘ yields Rs 100 back at the base rate of 1%, but this jumps to Rs 400 on online and dining spends due to its 4% category rates. This makes the Vetta card especially attractive for premium users who spend heavily on dining and online shopping, where the rewards quadruple compared to the base rate.
The HSBC Travelone Credit Card ⓘ also offers Rs 100 back per Rs 10,000 at the base 1% rate, but its category rewards peak at 3% on travel and dining, translating to Rs 300 back per Rs 10,000. While it does not match Vetta’s 4% in these categories, it still provides robust rewards for travelers and diners alike, with a balanced focus on travel perks.
Fees Compared
The Vetta Credit Card ⓘ charges an annual and joining fee of Rs 2,999 each, with a fee waiver threshold of Rs 5 lakh annual spend, equivalent to about Rs 41,667 per month. To cover the fee with base rewards alone, you need to spend roughly Rs 3 lakh annually.
In contrast, the HSBC Travelone Credit Card ⓘ levies higher fees at Rs 4,999 for both joining and annual fees. Its fee waiver is set at Rs 8 lakh annually, or about Rs 66,667 monthly. The break-even spend to cover the fee with base rewards is around Rs 5 lakh annually. Given the higher fee and waiver threshold, this card suits higher spenders or those who maximize the travel and forex benefits.
Which One Should You Pick
Choose the Vetta Credit Card ⓘ if you are a premium spender focused on dining and online shopping rewards. Its lower fees and easier waiver threshold make it a better fit for mid-to-high spends, especially if you value domestic and international lounge access along with curated Visa offers and comprehensive protection covers.
Opt for the HSBC Travelone Credit Card ⓘ if your priority is international travel and forex savings. It offers more international lounge visits, a significantly lower forex markup of 0.99%, and strong travel-related discounts, making it ideal for frequent travelers and those who spend heavily abroad.
Skip the Vetta Credit Card ⓘ if your spend is primarily travel abroad or if you want lower forex charges. Avoid the HSBC Travelone Credit Card ⓘ if you spend less than Rs 8 lakh annually or want stronger rewards in dining and online categories.
What to Check Before You Apply
- Caps on complimentary lounge visits and quarterly spend gates for lounge access on the Vetta Credit Card ⓘ.
- Redemption value and flexibility of reward points, especially since both cards use a points system.
- The exact spend required monthly to waive the annual fee and avoid paying the fee outright.
- Forex markup rates and any hidden foreign currency transaction fees beyond the stated percentages.
- Availability and convenience of lounges in your frequently visited airports, both domestic and international.

Comments
No comments yet
Be the first to share your experience with this card.