Quick Verdict
- The Ashva Credit Card ⓘ wins for everyday spend with a higher base reward rate and better category bonuses.
- For travel and lounge access, Ashva Credit Card ⓘ also leads, offering international lounge visits and lower forex markup.
- The American Express Gold Credit Card ⓘ is more expensive to hold with a higher annual fee and joining fee.
- Choose the American Express Gold Credit Card ⓘ if you value dining discounts and premium lifestyle benefits; pick Ashva Credit Card ⓘ for better rewards on travel and dining plus more lounge access.
Side by Side
| Detail | American Express Gold Credit Card ⓘ | Ashva Credit Card ⓘ |
|---|---|---|
| Annual fee | Rs 4,500 | Rs 2,999 |
| Joining fee | Rs 1,000 | Rs 2,999 |
| Fee waiver on spend | Rs 9,00,000 (about 9.00 lakh) | Rs 2,39,920 (about 2.40 lakh) |
| Reward rate | 0.5% | 1.25% |
| Reward type | points | points |
| Domestic lounge | 8 per year | 8 per year |
| International lounge | None | 4 per year |
| Forex markup | 3.5% | 1.5% |
| Best suited for | rewards, travel, shopping | premium, travel, lounge, rewards, shopping |
Rewards Compared
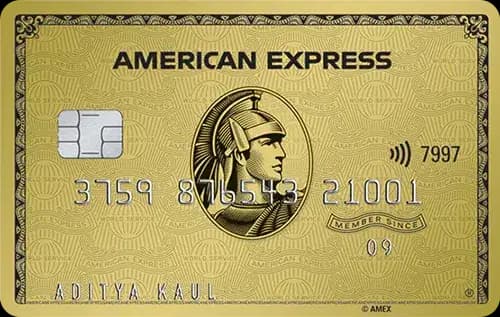
Spending Rs 10,000 on the American Express Gold Credit Card ⓘ earns Rs 50 in rewards at the base rate of 0.5%. This card focuses on lifestyle perks like dining discounts and hotel offers rather than high reward rates, which means the return on everyday spend is modest. The welcome benefit of 4,000 bonus Membership Rewards Points adds some upfront value but does not significantly boost the effective reward rate on regular spending.
The Ashva Credit Card ⓘ offers a much stronger base reward rate of 1.25%, translating to Rs 125 back on Rs 10,000 spent. For dining and travel categories, the card doubles the reward rate to 2.5%, giving Rs 250 back on Rs 10,000 in these spends. This makes Ashva Credit Card ⓘ a more lucrative choice for premium users who spend heavily on travel and dining, as it maximizes rewards in these categories.
Fees Compared
The American Express Gold Credit Card ⓘ charges a joining fee of Rs 1,000 and a hefty annual fee of Rs 4,500. To justify this cost purely from rewards at the base rate, a cardholder needs to spend about Rs 9,00,000 annually. This high break-even point means the card is best suited for heavy spenders who also value the premium benefits and discounts.
In contrast, the Ashva Credit Card ⓘ has a higher joining fee of Rs 2,999 but a lower annual fee of Rs 2,999. The fee waiver threshold is significantly lower at Rs 2,39,920 per year, making it easier to avoid fees with moderate spending. This card offers better rewards returns at lower spend levels, making it more accessible for users who want premium perks without the very high spend requirement.
Which One Should You Pick
Choose the American Express Gold Credit Card ⓘ if you prioritize lifestyle benefits such as dining discounts, hotel offers, and Apple Store cashback. It suits shoppers and travelers who can leverage these premium perks and are comfortable with a higher fee and a high spend threshold to break even. However, if your spend is below Rs 9,00,000 annually or you want more lounge access and better forex rates, this card may not be the best fit.
The Ashva Credit Card ⓘ is ideal for premium users who spend significantly on travel and dining. Its higher reward rate, international lounge access, and lower forex markup make it a strong contender for frequent travelers and those seeking luxury benefits like golf access and concierge services. It also has a more reasonable fee waiver threshold, making it suitable for mid to high spenders. Skip this card if you do not spend enough to cover the joining fee or if you prefer the specific lifestyle discounts offered by American Express.
Overall, the Ashva Credit Card ⓘ wins for most users due to its superior rewards, better travel benefits, and lower cost of ownership. The American Express Gold Credit Card ⓘ remains a niche choice for those who value its exclusive perks and can meet the high spend requirements.
What to Check Before You Apply
- Confirm if the rewards caps or category limits apply, as these can reduce effective returns.
- Check the redemption value of points, since the actual value may vary and affect your rewards.
- Understand the fee waiver math carefully; monthly spend requirements may be high.
- Consider the forex markup if you travel abroad frequently; Ashva Credit Card ⓘ offers a better rate.
- Verify the lounge access locations and the number of complimentary visits to ensure they match your travel patterns.

Comments
No comments yet
Be the first to share your experience with this card.