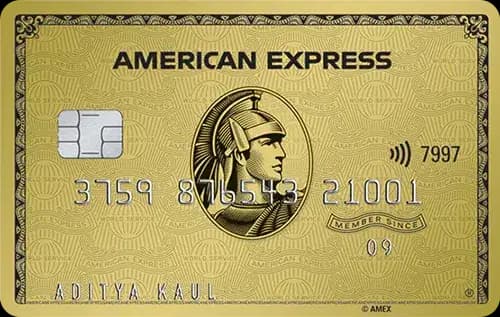
Quick Verdict
- For everyday spending and better reward rates, the ICICI Bank Sapphiro Credit Cardⓘ wins with a 1% base return and 2% on key categories.
- For travel perks, especially international lounge access, the ICICI Bank Sapphiro Credit Cardⓘ leads with 4 international lounge visits per year versus none on the Amex Gold.
- The American Express Gold Credit Cardⓘ is cheaper to hold in terms of joining plus annual fees but requires higher spend to cover fees through rewards.
- Pick the Amex Goldⓘ if you value lifestyle discounts and air accident insurance; choose ICICI Sapphiroⓘ if you want superior rewards, travel vouchers, and lounge access. Avoid Amex Goldⓘ if you spend below Rs 9 lakh annually and avoid ICICI Sapphiroⓘ if you cannot meet the Rs 6 lakh annual fee waiver threshold.
Side by Side
| Detail | American Express Gold Credit Cardⓘ | ICICI Bank Sapphiro Credit Cardⓘ |
|---|---|---|
| Annual fee | Rs 4,500 | Rs 3,500 |
| Joining fee | Rs 1,000 | Rs 6,500 |
| Fee waiver on spend | Rs 6.00 lakh | |
| Reward rate | 0.5% base | 1% base, 2% on online, dining, travel |
| Reward type | points | points |
| Domestic lounge | 8 per year | 8 per year |
| International lounge | None | 4 per year |
| Forex markup | 3.5% | 3.5% |
| Best suited for | rewards, travel, shopping | travel, lounge, rewards, shopping |
Rewards Compared
The American Express Gold Credit Cardⓘ offers a base reward rate of 0.5%, equating to Rs 50 back on every Rs 10,000 spent. This is a modest return better suited for those prioritizing lifestyle benefits and insurance coverage rather than pure cashback. Meanwhile, the ICICI Bank Sapphiro Credit Cardⓘ doubles this with a 1% base rate, giving Rs 100 back on Rs 10,000 spend, and further boosts returns to Rs 200 on Rs 10,000 spend in key categories like online shopping, dining, and travel. This makes it a stronger choice for those who want more immediate value from their everyday and category-specific spends.
The Sapphiro card's category rates significantly enhance rewards for targeted spends, which the Amex Gold card lacks. Therefore, for users with frequent dining, travel, or online shopping expenses, the ICICI Sapphiroⓘ can provide substantially more rewards per rupee spent.
Fees Compared
The Amex Goldⓘ has a joining fee of Rs 1,000 and an annual fee of Rs 4,500. It does not offer a fee waiver on spending, meaning cardholders must accept the fee or utilize the card’s benefits to justify the cost. To cover the Rs 4,500 fee at the 0.5% base return, one must spend about Rs 9 lakh annually.
The ICICI Sapphiroⓘ charges a higher joining fee of Rs 6,500 but a lower annual fee of Rs 3,500. This fee can be waived if the user spends Rs 6 lakh annually (about Rs 50,000 per month), which means the card can effectively cost zero in fees if the waiver threshold is met. The break-even spend to cover the fee at the base rate is Rs 3.5 lakh annually, significantly less than the Amex Goldⓘ.
Therefore, the ICICI Sapphiroⓘ offers a better fee waiver structure and more achievable break-even point for rewards, making it cheaper to hold for those who meet the spend criteria.
Which One Should You Pick
Choose the American Express Gold Credit Cardⓘ if you are a rewards-oriented shopper who also values lifestyle perks like air accidental insurance up to Rs 30 lakh, discounts at Lalit Hotels, dining discounts, and Apple Store cashback. It suits those who spend heavily on travel and shopping but do not prioritize international lounge access and prefer a modest annual fee.
Opt for the ICICI Bank Sapphiro Credit Cardⓘ if you want a high rewards return with 2% cashback on dining, travel, and online spends, plus access to both domestic and international lounges (8 and 4 visits respectively). It is ideal for frequent travelers and high spenders who can meet the Rs 6 lakh annual waiver threshold and want golf access and travel shopping vouchers worth more than Rs 9,500 as welcome benefits.
Skip the Amex Goldⓘ if your annual spend is below Rs 9 lakh, as the rewards will not cover the fees. Avoid the ICICI Sapphiroⓘ if you cannot maintain the Rs 6 lakh spending to waive fees or if the high joining fee of Rs 6,500 is prohibitive.
What to Check Before You Apply
- Confirm if your typical spends fall into the ICICI Sapphiroⓘ card’s bonus categories to maximize reward earnings.
- Check the redemption value and ease for both cards’ points to ensure you get good value for rewards.
- Verify the monthly spend requirement for the ICICI Sapphiroⓘ fee waiver and realistically assess if you can meet it.
- Be aware that both cards charge a 3.5% forex markup on international transactions, which can add significant cost on foreign spends.
- Consider the domestic and international lounge access locations and gates to ensure they align with your travel patterns.

Comments
No comments yet
Be the first to share your experience with this card.