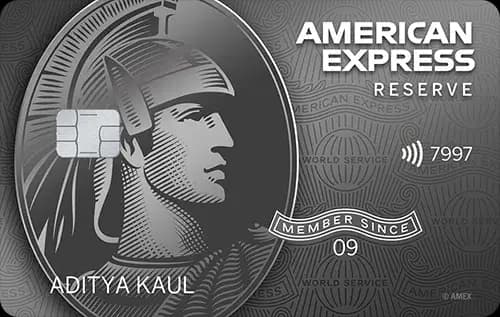
Quick Verdict
- The Standard Chartered Ultimate Credit Cardⓘ wins for everyday spend with a significantly higher base reward rate of 3.33% versus 0.5% on the American Express card.
- For travel and lounge access, the Standard Chartered Ultimate also leads with both domestic and international lounge entries, while the Amex Platinum Reserve offers only domestic lounges.
- The American Express Platinum Reserve Credit Card carries a higher joining and annual fee of Rs 10,000 each compared to Rs 5,000 on the Standard Chartered Ultimate, making it more expensive to hold.
- Choose the American Express Platinum Reserve if you value premium dining, exclusive memberships, and concierge services; pick the Standard Chartered Ultimate for better rewards on general spending and more comprehensive lounge access.
Side by Side
| Detail | American Express Platinum Reserve Credit Cardⓘ | Standard Chartered Ultimate Credit Cardⓘ |
|---|---|---|
| Annual fee | Rs 10,000 | Rs 5,000 |
| Joining fee | Rs 10,000 | Rs 5,000 |
| Fee waiver on spend | Rs 20,00,000 (about 20.00 lakh) | Rs 1,50,150 (about 1.50 lakh) |
| Reward rate | 0.5% | 3.33% |
| Reward type | points | points |
| Domestic lounge | 8 per year | 8 per year |
| International lounge | None | 4 per year |
| Forex markup | 3.5% | 2% |
| Best suited for | premium, dining, rewards, travel, shopping, lounge | rewards, travel, lounge, premium, shopping |
Rewards Compared
The American Express Platinum Reserve Credit Cardⓘ offers a base reward rate of 0.5%, which translates to Rs 50 in rewards on every Rs 10,000 spent. Its rewards are primarily points, which can be redeemed for various benefits. This card targets premium users who value exclusive dining offers, travel benefits, and memberships more than straightforward cashback or points accumulation.
In contrast, the Standard Chartered Ultimate Credit Cardⓘ delivers a much higher base reward rate of 3.33%, yielding Rs 333 in rewards per Rs 10,000 spent. This makes it substantially better for everyday spending and shopping. It also offers 5% cashback on duty-free spends, further enhancing its appeal for travelers. The category coverage is broader, making it a more versatile rewards card.
Fees Compared
The American Express Platinum Reserve Credit Card charges a joining fee and an annual fee of Rs 10,000 each, demanding a high annual spend of about Rs 20 lakh to break even purely on base rewards. Its fee waiver threshold is quite steep, making it suitable mostly for high-spending premium users who can leverage the card’s exclusive benefits.
The Standard Chartered Ultimate Credit Card, with Rs 5,000 joining and annual fees, is more accessible. Its fee waiver on spend is Rs 1.5 lakh annually, which is much easier to achieve, allowing more users to avoid fees. The break-even spend for base rewards is around Rs 1.5 lakh, making it a more cost-effective option for the average premium spender.
Which One Should You Pick
If you are a premium user focused on dining, travel perks, and exclusive memberships like Accor+ Explorer and EazyDiner Prime, the American Express Platinum Reserve Credit Cardⓘ is tailored for your needs. Its complimentary Priority Pass membership and concierge service add luxury, although you must be prepared for the higher fees and forex markup.
For those looking for superior rewards on everyday spend, better foreign exchange rates, and more extensive lounge access including international lounges, the Standard Chartered Ultimate Credit Cardⓘ is the smarter choice. It suits frequent travelers and shoppers who want to maximize rewards without incurring high fees.
Skip the American Express Platinum Reserve if you do not spend enough to justify its Rs 10,000 annual fees or if you want international lounge access. Avoid the Standard Chartered Ultimate if you prioritize premium dining discounts and concierge services over straightforward rewards.
What to Check Before You Apply
- Verify the caps on lounge visits and whether international lounges require prior-month spending.
- Understand the redemption value of points as both cards issue points but do not specify fixed rupee equivalence.
- Confirm if your monthly or annual spend realistically meets the fee waiver threshold to avoid paying hefty fees.
- Consider the forex markup percentage carefully if you travel abroad frequently, as this can add significant cost.
- Check the availability of lounges at your frequently used airports to ensure the lounge benefits are practical.

Comments
No comments yet
Be the first to share your experience with this card.