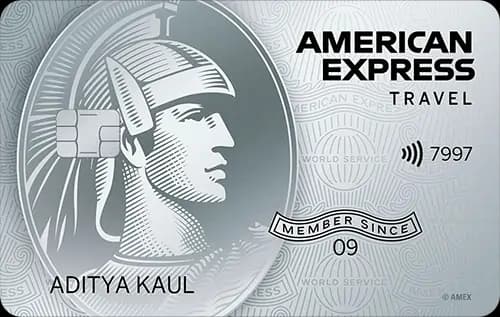
Quick Verdict
- For everyday spend, especially in dining, grocery, and utilities, the Bank of Maharashtra SBI Card PRIMEⓘ offers superior rewards.
- For travel benefits, including domestic lounge access and concierge services, the American Express Platinum Travel Credit Cardⓘ is the better pick.
- The SBI Card PRIMEⓘ is cheaper to hold with lower joining and annual fees.
- Choose the American Express Platinum Travel Credit Cardⓘ if you prioritize travel perks and concierge service; go for the SBI Card PRIMEⓘ if you want better rewards on essential categories and international lounge access.
Side by Side
| Detail | American Express Platinum Travel Credit Card | Bank of Maharashtra SBI Card PRIME |
|---|---|---|
| Annual fee | Rs 5,000 | Rs 2,999 |
| Joining fee | Rs 5,000 | Rs 2,999 |
| Reward rate | 0.5% | 0.5% base, up to 5% in categories |
| Reward type | points | points |
| Domestic lounge | 8 per year | 8 per year |
| International lounge | None | 4 per year |
| Forex markup | 3.5% | Not recorded |
| Best suited for | travel, rewards, shopping | rewards, dining, grocery, lounge |
Rewards Compared
The American Express Platinum Travel Credit Cardⓘ provides a flat reward rate of 0.5%, translating to Rs 50 earned on Rs 10,000 spent. Its rewards are in points, which can be valuable for travel redemptions but require understanding the redemption value. The card offers a welcome benefit of 10,000 Membership Rewards Points, which adds initial value for new users focused on travel.
On the other hand, the Bank of Maharashtra SBI Card PRIMEⓘ also has a base reward rate of 0.5%, yielding Rs 50 on Rs 10,000 spend. However, it shines in category spends with 2.5% returns in dining and grocery, equating to Rs 250 per Rs 10,000, and an impressive 5% return in utilities, which is Rs 500 on the same spend. This makes it highly rewarding for everyday essential expenses, far surpassing the flat rate of the Amex card in these categories.
Fees Compared
The American Express Platinum Travel Credit Cardⓘ demands a higher joining fee and annual fee of Rs 5,000 each. The card requires a spend of about Rs 10,00,000 annually to cover the fee through base rewards alone, which is quite steep. There is no fee waiver mentioned, so the fees are likely payable regardless of spend.
In contrast, the SBI Card PRIMEⓘ charges a lower joining and annual fee of Rs 2,999 each. It requires roughly Rs 5,99,800 annual spend at the base rate to cover these fees, which is more accessible for many users. No explicit fee waiver thresholds are stated, so fees are presumably fixed.
Between the two, the SBI Card PRIMEⓘ is more economical to hold, especially for moderate spenders who can benefit from category bonuses to offset fees faster.
Which One Should You Pick
Choose the American Express Platinum Travel Credit Cardⓘ if you are a frequent domestic traveler who values lounge access and concierge services. Its 8 domestic lounge visits per year and premium travel benefits make it suitable for those who prioritize travel comfort and assistance. However, the high fees and lack of international lounge access might deter occasional travelers or those on a budget.
The Bank of Maharashtra SBI Card PRIMEⓘ is ideal for users focused on maximizing everyday rewards, especially in dining, grocery, and utilities. Its international lounge access (4 visits annually) adds value for occasional international travelers. The lower fees make it a better option for budget-conscious users who want strong category returns without high costs.
In conclusion, if travel perks and concierge are your priority and you can afford higher fees, the Amex Platinum Travel Cardⓘ wins. For everyday rewards, lower fees, and some international lounge access, the SBI Card PRIMEⓘ is the smarter pick. Users who rarely travel or spend heavily in dining/grocery should skip the Amex, while those uninterested in category bonuses or lounges can skip the SBI Card PRIME.
What to Check Before You Apply
- Confirm any caps on reward points or lounge visits that might limit benefits.
- Understand the redemption value of points to ensure rewards translate to meaningful savings.
- Calculate the fee waiver or break-even spend carefully to avoid paying fees without sufficient rewards.
- Consider the 3.5% forex markup on the American Express card if you plan significant foreign currency spend.
- Check the availability and location of lounges, especially international ones, to ensure convenience.

Comments
No comments yet
Be the first to share your experience with this card.