Quick Verdict
- For everyday spend, especially dining and grocery, the BoM SBI Card ELITEⓘ wins due to its higher category reward rates.
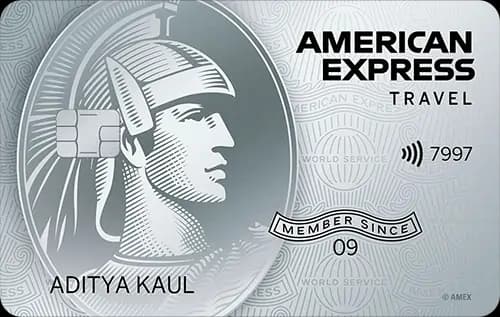
- For travel benefits focused on domestic lounge access and concierge service, the American Express Platinum Travel Credit Cardⓘ offers a more travel-centric experience.
- The BoM SBI Card ELITEⓘ is cheaper to hold in terms of forex markup and offers international lounge access.
- Choose the Amex Platinum Travel Card if you prioritize travel perks and concierge services; pick the BoM SBI Card ELITE if you want better rewards on dining, grocery, and international lounge access.
Side by Side
| Detail | American Express Platinum Travel Credit Cardⓘ | BoM SBI Card ELITEⓘ |
|---|---|---|
| Annual fee | Rs 5,000 | Rs 4,999 |
| Joining fee | Rs 5,000 | Rs 4,999 |
| Reward rate | 0.5% | 0.5% base; 2.5% dining, grocery |
| Reward type | points | points |
| Domestic lounge | 8 per year | 8 per year |
| International lounge | None | 6 per year |
| Forex markup | 3.5% | 1.99% |
| Best suited for | travel, rewards, shopping | rewards, dining, grocery, lounge |
Rewards Compared
With a base reward rate of 0.5%, both the American Express Platinum Travel Credit Cardⓘ and the BoM SBI Card ELITEⓘ earn Rs 50 per Rs 10,000 spent on general purchases. However, the BoM SBI Card ELITEⓘ shines in specific categories like dining and grocery, where it offers an effective return of 2.5%, translating to Rs 250 back on Rs 10,000 spent. This is a significant uplift compared to the flat 0.5% base rate of the Amex card, making the BoM SBI Card ELITEⓘ more rewarding for users who spend heavily in these categories.
The Amex Platinum Travel Credit Cardⓘ does not have category-specific higher rates but compensates with a welcome benefit of 10,000 Membership Rewards points and a focus on travel-related perks. Both cards use points as their reward type, but the Amex card’s points are branded Membership Rewards, which may have different redemption options not detailed here. Overall, for pure everyday rewards, especially in dining and groceries, the BoM SBI Card ELITEⓘ offers superior returns.
Fees Compared
Both cards carry nearly identical joining and annual fees, with the Amex Platinum Travel Credit Cardⓘ charging Rs 5,000 each and the BoM SBI Card ELITEⓘ charging Rs 4,999 each. Neither card specifies an annual fee waiver threshold based on spend, so these fees are effectively fixed costs. The break-even spend to cover the annual fee at the base reward rate is around Rs 10 lakh for both cards, meaning casual users may not fully recoup the fee through rewards alone.
However, the foreign exchange markup differs substantially. The Amex card charges 3.5%, which on Rs 1,00,000 spent abroad results in Rs 3,500 in forex fees, whereas the BoM SBI Card ELITEⓘ charges a much lower 1.99%, costing Rs 1,990 on the same foreign spend. This makes the BoM SBI Card ELITEⓘ more cost-effective for international travelers who spend abroad.
Which One Should You Pick
The American Express Platinum Travel Credit Cardⓘ is best suited for travelers who value concierge services and domestic lounge access without much emphasis on international lounges. Its welcome benefit and travel-oriented perks make it attractive for those who want a premium travel experience within India. However, it is less rewarding for everyday spends outside travel and comes with a higher forex markup.
The BoM SBI Card ELITEⓘ is ideal for users who want a balanced card offering strong rewards on dining and grocery spends, plus access to both domestic and international lounges. Its lower forex markup makes it a better choice for international travel spenders. Users who want maximum rewards on lifestyle categories and international lounge access should prefer this card.
In conclusion, pick the Amex Platinum Travel Credit Cardⓘ if your primary focus is domestic travel perks and concierge services. Choose the BoM SBI Card ELITEⓘ if you want better category rewards, international lounge access, and lower forex charges. Those who do not spend enough to justify the annual fees or do not travel frequently should skip both.
What to Check Before You Apply
- Confirm if the domestic lounge access has a quarterly spend gate, as the Amex card requires Rs 1 lakh quarterly spend to avail of lounges.
- Understand the redemption value of points, especially for the Amex card’s Membership Rewards points, before assuming their worth.
- Calculate whether your annual spend justifies the joining and annual fees since both cards require nearly Rs 10 lakh spend to cover fees at base rates.
- Consider forex markup carefully if you plan significant international spending; the Amex card’s 3.5% forex fee is steep compared to the BoM SBI Card ELITEⓘ.

Comments
No comments yet
Be the first to share your experience with this card.