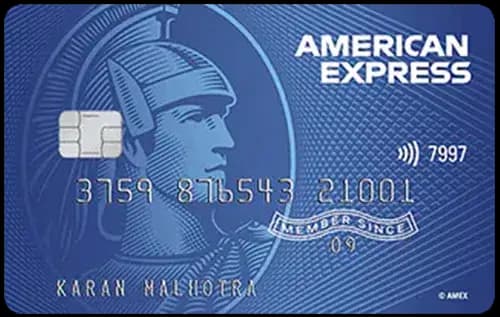
Quick Verdict
- For everyday spend, the Yes Bank Rupay Credit Cardⓘ wins with a higher base reward rate of 1% compared to the American Express Smartearn Credit Cardⓘ’s 0.5%.
- In travel benefits, Yes Bank Rupay Credit Cardⓘ offers 4 domestic lounge visits per year, whereas the Amex Smartearn Credit Cardⓘ provides no lounge access.
- The Yes Bank Rupay Credit Cardⓘ is cheaper to hold with no joining or annual fees, compared to the Smartearn’s Rs 495 fees.
- Choose the Amex Smartearn Credit Cardⓘ if you primarily shop online and want a modest welcome cashback; pick Yes Bank Rupay Credit Cardⓘ if you want ongoing rewards on groceries, dining and UPI spends plus lounge access.
Side by Side
| Detail | American Express Smartearn Credit Cardⓘ | Yes Bank Rupay Credit Cardⓘ |
|---|---|---|
| Annual fee | Rs 495 | Nil (lifetime free) |
| Joining fee | Rs 495 | Nil (lifetime free) |
| Fee waiver on spend | None | Rs 75,000 annually (Rs 6,250 monthly) |
| Reward rate | 0.5% base, 2.5% online | 1% base, 3% grocery and dining, 1% UPI |
| Reward type | Points | Points |
| Domestic lounge | None | 4 per year (Rs 50,000 quarterly spend gate) |
| International lounge | None | None |
| Forex markup | 3.5% | 3.5% |
| Best suited for | Shopping, first-card, rewards | UPI-Rupay, rewards, grocery, first-card, shopping |
Rewards Compared
With a Rs 10,000 spend, the American Express Smartearn Credit Cardⓘ returns Rs 50 at its base rate, but if that spend is online, it jumps to Rs 250 thanks to its 2.5% category rate. This makes it attractive for online shoppers who want to maximize rewards on digital purchases. However, outside online categories, the base 0.5% return is relatively low.
The Yes Bank Rupay Credit Cardⓘ offers Rs 100 on Rs 10,000 at its base 1% rate, doubling the Amex Smartearn’s base return. It further boosts rewards to Rs 300 on groceries and dining, reflecting a 3% return in these categories. Its 1% return on UPI transactions also adds value for users frequently transacting digitally. Overall, Yes Bank Rupay Credit Cardⓘ delivers a more consistent and higher reward across common spending categories.
Fees Compared
The American Express Smartearn Credit Cardⓘ charges Rs 495 each for joining and annual fees, with no waiver option. To break even on fees purely through base rewards, you would need to spend Rs 99,000 annually, which is quite high unless you shop heavily online to leverage the 2.5% category rate.
In contrast, the Yes Bank Rupay Credit Cardⓘ is free for life with no joining or annual fees. It does have a fee waiver threshold of Rs 75,000 annual spend (Rs 6,250 per month) to keep the card free. Given the lack of fees, this card is more cost-effective for users with moderate spending who want to avoid fee pressure. The waiver spend is reasonable and easy to hit for regular cardholders.
Which One Should You Pick
Pick the American Express Smartearn Credit Cardⓘ if your spending is mainly online shopping and you want a straightforward rewards structure with a welcome cashback of Rs 500. It suits those looking for a first credit card focused on rewards in the digital shopping space, despite the small fees.
Choose the Yes Bank Rupay Credit Cardⓘ if you want a no-fee card that rewards you well on groceries and dining while also offering limited domestic lounge access. It is ideal for everyday spenders who want consistent returns across categories and lounge benefits without worrying about fee waivers.
If you rarely shop online and dislike annual fees, skip the Amex Smartearn Credit Cardⓘ. Conversely, if you do not spend enough to meet the Rs 6,250 monthly waiver on the Yes Bank Rupay Credit Cardⓘ, or if you need international lounge access, then that card is less suitable.
What to Check Before You Apply
- Confirm the quarterly Rs 50,000 spend gate for domestic lounges on the Yes Bank Rupay Credit Cardⓘ to ensure eligibility.
- Verify the redemption value and flexibility of points for both cards since reward types are points and actual value can vary.
- Understand the fee waiver calculation on the Yes Bank Rupay Credit Cardⓘ if you aim to avoid any fees.
- Be aware that both cards charge a 3.5% forex markup, which is standard but costly for international spends.
- Check lounge availability and participating airports for the Yes Bank Rupay Credit Cardⓘ domestic lounges to avoid disappointment.

Comments
No comments yet
Be the first to share your experience with this card.