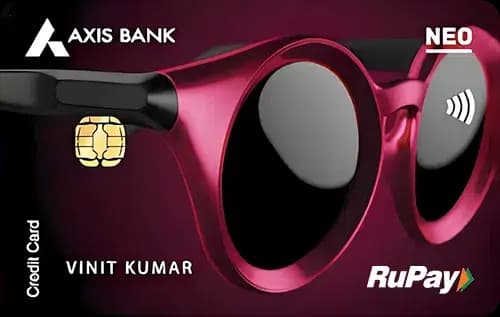
Quick Verdict
- For everyday spend, the HDFC Bank Freedom Credit Cardⓘ offers a higher base reward rate, making it the better choice for general purchases.
- For online and utilities categories, the Axis Bank Neo Credit Cardⓘ delivers superior rewards, ideal for those focused on these spends.
- The Axis Bank Neo Credit Card is cheaper to hold with no joining or annual fees, while the HDFC Freedom card charges Rs 500 for both but offers fee waivers on Rs 50,000 annual spend.
- Choose Axis Bank Neo if you want a no-fee card with great online and utility rewards; pick HDFC Freedom if you spend broadly and can meet the fee waiver criteria.
Side by Side
| Detail | Axis Bank Neo Credit Cardⓘ | HDFC Bank Freedom Credit Cardⓘ |
|---|---|---|
| Annual fee | Nil (lifetime free) | Rs 500 |
| Joining fee | Nil (lifetime free) | Rs 500 |
| Fee waiver on spend | Rs 50,000 annually | |
| Reward rate | 0.2% base | 0.33% base |
| Reward type | points | points |
| Domestic lounge | None | None |
| International lounge | None | None |
| Forex markup | 3.5% | 3.5% |
| Best suited for | first-card, shopping, cashback, dining | first-card, cashback, shopping |
Rewards Compared
Spending Rs 10,000 on the Axis Bank Neo Credit Cardⓘ earns Rs 20 back at the base rate of 0.2%. However, when spending in the online or utilities categories, the card significantly boosts rewards to Rs 500 per Rs 10,000 spent, reflecting a 5% effective return. This makes the card highly attractive for users who primarily transact online or pay utility bills regularly.
In contrast, the HDFC Bank Freedom Credit Cardⓘ offers a higher base reward rate of 0.33%, translating to Rs 33 back on Rs 10,000 of general spend. Its category bonus is more modest at 3.33% for online spends, yielding Rs 333 per Rs 10,000. While it does not match the Neo card’s category rewards, its stronger base rate benefits users with varied spending patterns beyond just online and utilities.
Fees Compared
The Axis Bank Neo Credit Card has a clear advantage in fees, with zero joining and annual fees for life. There is no minimum spend needed to avoid fees, making it a risk-free option for light spenders or those seeking a fee-free card.
The HDFC Bank Freedom Credit Card charges Rs 500 as a joining fee and Rs 500 annually. This fee is waived if the cardholder spends Rs 50,000 annually, which breaks down to about Rs 4,167 per month. For users unable to meet this threshold, the fees can add up, diluting the effective rewards. According to the head-to-head data, the higher base reward rate on the Freedom card requires an annual spend of approximately Rs 1.52 lakh just to cover the Rs 500 fee on rewards alone. For the rate difference to justify the fee, one would need to spend about Rs 3.85 lakh annually.
Which One Should You Pick
Choose the Axis Bank Neo Credit Cardⓘ if you want a completely free card with excellent rewards on online shopping and utilities. It suits first-time cardholders or those who want to avoid fees and maximize cashback on specific categories. Avoid this card if you spend mostly outside online and utility categories, as the base rewards are low.
Opt for the HDFC Bank Freedom Credit Cardⓘ if you have diverse spending habits and can comfortably spend over Rs 50,000 annually to waive the fees. It is better for users who want a higher base reward rate across all spends and do not mind paying a fee if they meet the waiver. Skip this card if you spend less than Rs 50,000 a year or want a no-fee card.
Overall, the Axis Bank Neo Credit Card is better for category-focused spenders and fee-conscious users, while the HDFC Freedom Credit Card wins for general spenders who can meet the fee waiver and want higher base rewards.
What to Check Before You Apply
- Confirm if your spending patterns align with the card’s category rewards to maximize returns.
- Understand the redemption value and process for points to ensure you get the best value.
- Calculate the monthly spend needed to waive fees and see if you can realistically meet it.
- Consider the 3.5% forex markup if you travel or shop internationally, as both cards charge the same rate.
- Check the availability and access rules for lounges if that is important to you; neither card offers lounge benefits.

Comments
No comments yet
Be the first to share your experience with this card.