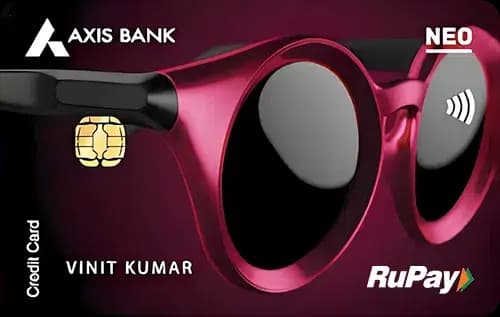
Quick Verdict
- The IDFC HPCL First Power Plus Credit Cardⓘ wins for everyday spend with a higher base reward rate and strong category benefits, especially on fuel and grocery.
- The Axis Bank Neo Credit Cardⓘ offers no lounges and no fees, making it cheaper to hold and better suited for those seeking a simple, no-cost cashback card.
- The IDFC card provides 4 domestic lounge visits per year, which the Axis Bank Neo card does not offer.
- Choose the Axis Bank Neoⓘ if you want a free, fuss-free cashback card for online and utilities spend. Pick the IDFC First Power Plusⓘ if you spend heavily on fuel and groceries and value free lounges with moderate annual fees.
Side by Side
| Detail | Axis Bank Neo Credit Cardⓘ | IDFC HPCL First Power Plus Credit Cardⓘ |
|---|---|---|
| Annual fee | Nil (lifetime free) | Rs 499 |
| Joining fee | Nil (lifetime free) | Rs 499 |
| Fee waiver on spend | Rs 1.50 lakh annually (Rs 12,500 monthly) | |
| Reward rate | 0.2% base | 0.75% base |
| Reward type | Points | Points |
| Domestic lounge | None | 4 per year (Rs 20,000 monthly spend gate) |
| International lounge | None | None |
| Forex markup | 3.5% | 3.5% |
| Best suited for | First-card, shopping, cashback, dining | Fuel, UPI-Rupay, grocery, lounge |
Rewards Compared
Spending Rs 10,000 on the Axis Bank Neo Credit Cardⓘ earns Rs 20 worth of points at the base rate, but ramps up to Rs 500 on online and utilities categories due to the 5% effective return. This makes it attractive for users who primarily shop online or pay utility bills. The card’s welcome benefit of 100% cashback up to Rs 300 on the first utility bill payment further sweetens the deal for utility spenders.
On the other hand, the IDFC HPCL First Power Plus Credit Cardⓘ yields Rs 75 at the base reward rate on Rs 10,000 spent, significantly higher than the Axis Neo’s base. Category-wise, it offers 6.5% (Rs 650) on fuel and 5% (Rs 500) on both grocery and utilities. This makes it ideal for those with fuel and grocery expenses, where the card’s rewards substantially outperform the Axis Neoⓘ. The IDFC card also offers a welcome gift voucher and up to 5% cashback on the first EMI transaction, adding to its value for new users.
Fees Compared
The Axis Bank Neo Credit Cardⓘ stands out with zero joining and annual fees for life, making it a no-cost option to hold indefinitely. It has no fee waiver conditions, so any cardholder pays nothing regardless of spend.
Conversely, the IDFC HPCL First Power Plus Credit Cardⓘ charges Rs 499 as a joining fee and Rs 499 annually. However, this fee is waived if the cardholder spends Rs 1.50 lakh annually, equating to Rs 12,500 monthly. The break-even analysis shows you need to spend about Rs 66,533 annually on the IDFC card at the base rate to cover the annual fee purely with rewards. Since the IDFC card has a higher base and category reward rate, frequent spenders in relevant categories can justify the fee and even get lounge access.
Which One Should You Pick
Choose the Axis Bank Neo Credit Cardⓘ if you are a first-time cardholder or someone who prefers a simple, fee-free card with decent cashback on online shopping and utility payments. It suits budget-conscious users who want to avoid annual fees and complicated fee waiver criteria. The lack of lounges and forex benefits means it is not ideal for frequent travelers.
Opt for the IDFC HPCL First Power Plus Credit Cardⓘ if you spend heavily on fuel, groceries, and utilities and want to enjoy domestic lounge visits. The Rs 499 fee is easily offset if you meet the Rs 1.50 lakh annual spend threshold, making it a rewarding choice for urban consumers with regular fuel and grocery expenses. The card’s higher base reward rate also benefits broader spending.
In conclusion, skip the Axis Neoⓘ if you want lounge access or higher rewards on fuel. Avoid the IDFC First Power Plusⓘ if you cannot meet the Rs 1.50 lakh spend or dislike annual fees. For everyone else, the IDFC card wins on rewards and perks, while the Axis Neoⓘ holds ground as a no-fee, no-frills cashback card.
What to Check Before You Apply
- Verify if your spending pattern aligns with the card’s category rewards to maximize value.
- Confirm the redemption value and ease of converting points to cashback or vouchers.
- Understand the fee waiver maths carefully for the IDFC card; missing the Rs 1.50 lakh annual spend means paying fees.
- Note the 3.5% forex markup on both cards, which can be costly for foreign currency transactions.
- Check the domestic lounge access details and monthly spend gate on the IDFC card to avoid surprises.

Comments
No comments yet
Be the first to share your experience with this card.