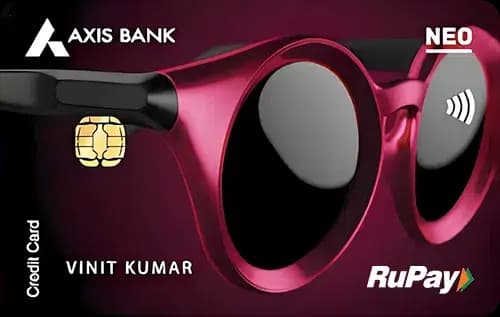
Quick Verdict
- For everyday spend, the ICICI Bank HPCL Coral Credit Cardⓘ wins with a higher base reward rate of 0.5% versus 0.2% on the Axis Bank Neo.
- For fuel spend, the ICICI HPCL Coral also leads, offering 5% back compared to no special fuel category on Axis Neo.
- The Axis Bank Neo Credit Cardⓘ is cheaper to hold since it has no joining or annual fees, making it ideal for low spenders.
- Pick the Axis Bank Neo for online shopping and utilities with no fees, and the ICICI HPCL Coral for fuel enthusiasts and those who can meet the Rs 1.5 lakh annual fee waiver.
Side by Side
| Detail | Axis Bank Neo Credit Cardⓘ | ICICI Bank HPCL Coral Credit Cardⓘ |
|---|---|---|
| Annual fee | Nil (lifetime free) | Rs 199 |
| Joining fee | Nil (lifetime free) | Rs 199 |
| Fee waiver on spend | Rs 1.50 lakh | |
| Reward rate | 0.2% base | 0.5% base |
| Reward type | points | points |
| Domestic lounge | None | 4 per year |
| International lounge | None | None |
| Forex markup | 3.5% | 3.5% |
| Best suited for | first-card, shopping, cashback, dining | fuel, first-card, shopping |
Rewards Compared
The Axis Bank Neo Credit Cardⓘ offers a base reward rate of 0.2%, which translates to Rs 20 for every Rs 10,000 spent. However, it shines in its online and utilities categories, where it provides a 5% return, meaning Rs 500 back on Rs 10,000 spent in these segments. This makes it a strong contender for users who primarily spend on utilities and online shopping.
On the other hand, the ICICI Bank HPCL Coral Credit Cardⓘ gives a higher base reward rate of 0.5%, or Rs 50 per Rs 10,000 spent, more than double the Axis Neo’s base rate. It also offers a 5% reward rate on fuel purchases, returning Rs 500 on Rs 10,000 spent on fuel. This card is tailored for fuel spenders and those looking for a solid base return across other spends.
Fees Compared
The Axis Bank Neo Credit Cardⓘ has no joining or annual fees, making it a zero-cost card to hold for life. In contrast, the ICICI Bank HPCL Coral Credit Cardⓘ charges Rs 199 as both joining and annual fees. The annual fee is waived if you spend Rs 1.5 lakh annually, which breaks down to Rs 12,500 per month. The ICICI card requires Rs 39,800 of spend at the base rate to cover the fee cost purely through rewards. Considering the higher base reward rate, the ICICI card can justify its fee if you are a moderate to heavy spender, especially on fuel.
Which One Should You Pick
Choose the Axis Bank Neo Credit Cardⓘ if you want a no-fee, straightforward cashback card with excellent rewards on online and utility spends. It is ideal for first-time credit card users or those who want to avoid fees altogether. However, it lacks lounge access and fuel benefits.
Opt for the ICICI Bank HPCL Coral Credit Cardⓘ if you regularly spend on fuel and want a higher base reward rate. The domestic lounge access is a nice perk for frequent travelers domestically, although there is a quarterly Rs 75,000 spend gate to unlock this benefit. You should be comfortable meeting the Rs 1.5 lakh annual spend to waive the fee and maximize value.
In conclusion, the ICICI HPCL Coral is better for fuel and moderate to high spenders who can leverage lounges and fee waivers. The Axis Bank Neo is the better choice for budget-conscious users seeking fee-free rewards on online and utility spends. Those who rarely spend on fuel or lounges should skip the ICICI HPCL Coral due to its fees.
What to Check Before You Apply
- Confirm if your typical spending categories match the card’s bonus categories to maximize rewards.
- Check if there are any caps on the 5% category rewards, especially for fuel or utilities.
- Understand the fee waiver threshold and calculate if your monthly spend meets it to avoid unexpected fees.
- Be aware of the 3.5% forex markup if you plan to use the card abroad, as both cards charge this standard fee.
- For lounge access on the ICICI HPCL Coral, verify if you can meet the quarterly Rs 75,000 spend gate to enjoy the 4 domestic lounge visits.

Comments
No comments yet
Be the first to share your experience with this card.