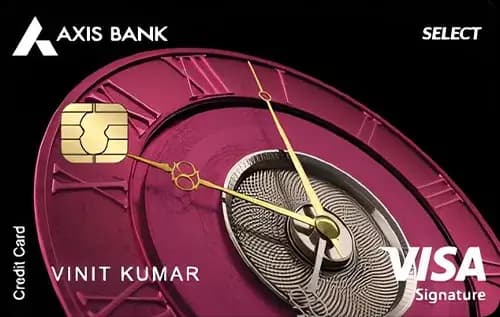
Quick Verdict
- For everyday spending, the Ashva Credit Cardⓘ wins with a higher base reward rate of 1.25% versus 1% on the Axis Bank Select Credit Cardⓘ.
- When it comes to travel perks and lounge access, both cards offer comparable benefits, including 8 domestic and 4 international lounge visits per year, but Ashva edges ahead with premium benefits like free stays at ITC Hotels and concierge services.
- The Axis Bank Select Credit Cardⓘ is slightly more expensive to hold with a Rs 3,000 annual fee and joining fee, compared to Rs 2,999 each for the Ashva Credit Cardⓘ.
- Choose the Axis Bank Select Credit Cardⓘ if you prioritize grocery and online shopping rewards; go for the Ashva Credit Cardⓘ if you want better base rewards and premium travel benefits.
Side by Side
| Detail | Axis Bank Select Credit Cardⓘ | Ashva Credit Cardⓘ |
|---|---|---|
| Annual fee | Rs 3,000 | Rs 2,999 |
| Joining fee | Rs 3,000 | Rs 2,999 |
| Fee waiver on spend | Rs 10.00 lakh | Not recorded |
| Reward rate | 1% base; 4% grocery; 2% online | 1.25% base; 2.5% dining & travel |
| Reward type | Points | Points |
| Domestic lounge | 8 per year | 8 per year |
| International lounge | 4 per year | 4 per year |
| Forex markup | 1.5% | 1.5% |
| Best suited for | Rewards, grocery, lounge, travel, shopping | Premium, travel, lounge, rewards, shopping |
| Golf access | Yes | Yes |
| Concierge | No | Yes |
| Premium benefits | None | Free ITC stays, dining discounts, 900+ hotel benefits |
Rewards Compared
If you spend Rs 10,000 on the Axis Bank Select Credit Cardⓘ, you earn Rs 100 back at the base reward rate of 1%. This increases significantly in specific categories such as groceries where the return is Rs 400 per Rs 10,000 spent, and Rs 200 for online purchases. This card suits those whose spending is concentrated in grocery and online shopping, offering targeted higher returns in these categories.
On the other hand, the Ashva Credit Cardⓘ delivers a superior base reward rate of 1.25%, translating to Rs 125 back on Rs 10,000 spent across general categories. It also offers 2.5% returns on dining and travel spends, which means Rs 250 back per Rs 10,000 spent in these categories. This card is better for users who spend more on travel and dining, providing more consistent rewards on these premium categories.
Fees Compared
The Axis Bank Select Credit Cardⓘ charges a joining fee and annual fee of Rs 3,000 each, with a waiver available if you spend Rs 10 lakh annually, which breaks down to about Rs 83,333 per month. This is a high threshold, making fee waiver difficult for moderate spenders. The break-even spend to cover the annual fee at the base rate is approximately Rs 3 lakh.
The Ashva Credit Cardⓘ has a slightly lower joining and annual fee of Rs 2,999 each. There is no specified fee waiver threshold, so the annual fee is generally payable. However, the higher base reward rate means the break-even spend is lower, at about Rs 2.40 lakh, making it somewhat easier to justify the fee through rewards.
Which One Should You Pick
Pick the Axis Bank Select Credit Cardⓘ if your spending is heavy on groceries and online shopping and you value access to domestic and international lounges. It is also suitable if you want golf access and can meet the high fee waiver spend threshold to avoid fees.
Choose the Ashva Credit Cardⓘ if you prefer a better base reward rate, spend more on dining and travel, and want premium benefits like free hotel stays, concierge services, and dining discounts. This card suits frequent travelers and those looking for luxury perks.
If you rarely spend on groceries or online shopping, skip the Axis Bank Select Credit Cardⓘ. Conversely, if you do not value premium travel benefits or concierge services, the Ashva Credit Cardⓘ might be more than you need.
What to Check Before You Apply
- Confirm if your typical monthly and category spend can meet the Axis Bank Select Credit Cardⓘ fee waiver threshold of Rs 83,333.
- Understand the redemption process for points on both cards and whether the stated reward rates translate directly into value.
- Consider the forex markup of 1.5% on both cards if you spend abroad frequently.
- Check the domestic lounge access gate for the Axis Bank Select Credit Cardⓘ, which requires Rs 50,000 annual spend on lounges.
- Verify the availability of lounge locations relevant to your travel patterns.

Comments
No comments yet
Be the first to share your experience with this card.