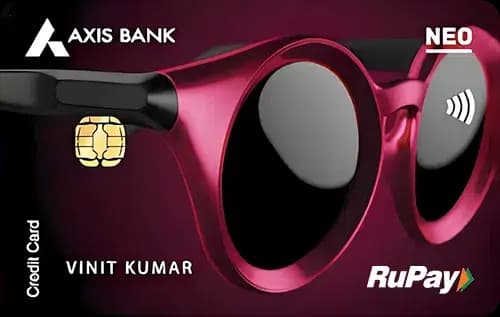
Quick Verdict
- The LIC Classic Credit Cardⓘ wins for everyday spend with a 0.5% reward rate compared to 0.2% on the Axis Bank Neo Credit Cardⓘ.
- The LIC Classic Credit Cardⓘ also leads for travel benefits by offering 2 domestic lounge visits per year, while Axis Bank Neo Credit Cardⓘ provides no lounge access.
- Both cards charge no joining or annual fees, making them equally cheap to hold.
- Pick the Axis Bank Neo Credit Cardⓘ if you want a simple cashback card with strong rewards on online and utilities spend and no fees ever.
- Choose the LIC Classic Credit Cardⓘ if you value higher base rewards, occasional domestic lounge access, and a card truly designed for lifetime-free usage.
Side by Side
| Detail | Axis Bank Neo Credit Cardⓘ | LIC Classic Credit Cardⓘ |
|---|---|---|
| Annual fee | Nil (lifetime free) | Nil (lifetime free) |
| Joining fee | Nil (lifetime free) | Nil (lifetime free) |
| Fee waiver on spend | None | None |
| Reward rate | 0.2% base, 5% on online & utilities | 0.5% base |
| Reward type | Points | Points |
| Domestic lounge | None | 2 per year |
| International lounge | None | None |
| Forex markup | 3.5% | 3.5% |
| Best suited for | First-card, shopping, cashback, dining | Lifetime-free, first-card, lounge |
Rewards Compared
The Axis Bank Neo Credit Cardⓘ offers a base reward rate of 0.2%, equating to Rs 20 back on Rs 10,000 spent. However, it shines in specific categories like online shopping and utilities, where it delivers 5% rewards or Rs 500 on Rs 10,000 spend. This makes it highly attractive for users who frequently pay bills online or shop digitally, providing substantial cashback in those focused areas.
On the other hand, the LIC Classic Credit Cardⓘ provides a straightforward base reward of 0.5%, translating to Rs 50 on every Rs 10,000 spent regardless of category. Although it lacks elevated category bonuses, this steady rate benefits users with diverse spending patterns who prefer consistent rewards without tracking categories. The Classic card’s rewards are more versatile for general everyday purchases.
Fees Compared
Neither card charges any joining or annual fees, making both lifetime free cards with no fee waiver thresholds required. This zero-fee structure means the cards are equally economical to hold, removing any pressure to meet minimum spends just to avoid charges. The Axis Bank Neo Credit Cardⓘ emphasizes no fees alongside category bonuses, while the LIC Classic Credit Cardⓘ combines no fees with lounge benefits.
With no fees or spend gates to worry about, the break-even point between these cards purely depends on your spending habits and preference for lounges or category rewards rather than cost concerns.
Which One Should You Pick
If you are a first-time credit card user seeking an absolutely free card that rewards your online and utility bill payments generously, the Axis Bank Neo Credit Cardⓘ is a smart choice. Its 5% cashback on these categories can save you a good amount if your spend is focused there. However, if you rarely shop online or pay utility bills through the card, its base rewards are minimal at just 0.2%.
The LIC Classic Credit Cardⓘ is better suited for those who want a simple, no-fee card with a better base reward rate of 0.5% and the added perk of two domestic lounge visits per year. It fits well if you value lounge access and want consistent rewards on all spends. However, if lounges or a higher base reward rate are not priorities, and you want higher returns on specific categories instead, this card may offer less value.
In conclusion, pick the Axis Bank Neo Credit Cardⓘ for category-focused cashback without any fees, and the LIC Classic Credit Cardⓘ for a higher flat reward rate plus lounge access. Skip the Neo card if you want lounge access or uniform rewards, and skip the Classic card if you spend mainly online or on utilities and want targeted cashback.
What to Check Before You Apply
- Verify if the Axis Bank Neo Credit Card’s 5% cashback categories suit your regular spending pattern.
- Confirm the LIC Classic Credit Card’s domestic lounge access is available at your preferred airports and limited to two visits annually.
- Understand that both cards have no fee waiver thresholds since they charge no annual or joining fees.
- Remember both cards have a 3.5% forex markup on foreign currency spend, so avoid overseas transactions if you want to minimize fees.

Comments
No comments yet
Be the first to share your experience with this card.