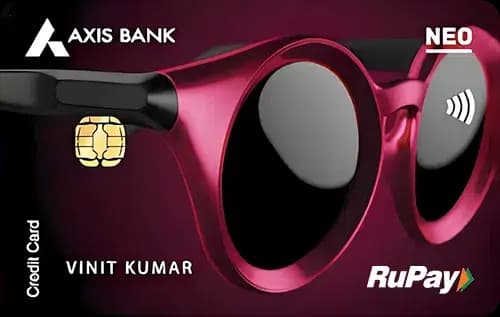
Quick Verdict
- For everyday spends, especially online and utility bills, the Axis Bank Neo Credit Cardⓘ wins with a strong 5% cashback in these categories.
- For travel benefits and lounge access, the Samsung Axis Bank Infinite Credit Cardⓘ clearly leads, offering multiple domestic and international lounge visits.
- Both cards have no joining or annual fees, but the Infinite card requires Rs 3 lakh annual spend for fee waiver, making the Neo card cheaper to hold for low spenders.
- Choose the Neo cardⓘ if you want no-fee, high cashback on online and utility spends without lounge needs. Pick the Infinite cardⓘ if you are a frequent traveler looking for lounges and higher rewards on online and dining spends.
Side by Side
| Detail | Axis Bank Neo Credit Cardⓘ | Samsung Axis Bank Infinite Credit Cardⓘ |
|---|---|---|
| Annual fee | Nil (lifetime free) | Nil (lifetime free) |
| Joining fee | Nil (lifetime free) | Nil (lifetime free) |
| Fee waiver on spend | Rs 3.00 lakh annually (Rs 25,000 per month) | |
| Reward rate | 0.2% base; 5% online, utilities | 1.5% base; 10% online, 3% dining |
| Reward type | points | points |
| Domestic lounge | None | 8 per year |
| International lounge | None | 4 per year |
| Forex markup | 3.5% | 3.5% |
| Best suited for | first-card, shopping, cashback, dining | shopping, lounge, rewards, travel |
Rewards Compared
Spending Rs 10,000 on the Axis Bank Neo Credit Cardⓘ yields Rs 20 back as base rewards, but if the spend is in online or utilities categories, the reward jumps to Rs 500. This makes it an excellent choice for those who frequently pay utility bills or shop online, translating to a significant 5% effective return. Other spends earn a modest 0.2% return.
In contrast, the Samsung Axis Bank Infinite Credit Cardⓘ offers a much higher base reward of Rs 150 on Rs 10,000 spent. This increases to Rs 1,000 for online spends and Rs 300 for dining, reflecting 10% and 3% returns respectively. This card is more rewarding for diversified spending patterns, especially online shopping and dining out, providing enhanced rewards in these categories over the Neo cardⓘ.
Fees Compared
Neither card charges a joining or annual fee, making both attractive for fee-conscious users. However, the Samsung Axis Bank Infinite Credit Cardⓘ has a fee waiver condition requiring Rs 3 lakh annual spend (about Rs 25,000 monthly) to maintain the fee-free status. The Axis Bank Neo Credit Cardⓘ has no such conditions, being lifetime free with no spend threshold.
For users who cannot meet the Rs 3 lakh annual spend on the Infinite cardⓘ, the effective cost could arise, but since the annual fee is nil when waived, the break-even point depends on whether the user values the lounge access and higher rewards enough to justify spending Rs 25,000 monthly. For low to moderate spenders, the Neo cardⓘ remains cheaper to hold without any fee concerns.
Which One Should You Pick
The Axis Bank Neo Credit Cardⓘ suits first-time credit card users and those focused on maximising cashback on online shopping and utility bill payments without worrying about fees or lounge access. It is ideal if you want a simple, no-fee card that rewards everyday spends in specific categories.
The Samsung Axis Bank Infinite Credit Cardⓘ is designed for high spenders who travel frequently and can benefit from lounge access and superior reward rates, especially on online purchases and dining. If you can comfortably spend Rs 3 lakh annually, this card offers greater value through rewards and privileges.
In conclusion, skip the Neo cardⓘ if you want travel perks or higher rewards on dining, and avoid the Infinite cardⓘ if you do not meet the high spend threshold or have no use for lounges. For general cashback and no fees, the Neo cardⓘ is the safer pick; for premium benefits and higher returns at scale, the Infinite cardⓘ wins.
What to Check Before You Apply
- Verify if the 5% or 10% reward rates have caps or category restrictions.
- Confirm the redemption value and process for points to ensure you get full value.
- Understand the fee waiver condition on the Infinite cardⓘ to avoid unexpected costs.
- Be aware both cards charge a 3.5% forex markup on foreign currency spends.
- Check which lounges are accessible and their locations to ensure they match your travel routes.

Comments
No comments yet
Be the first to share your experience with this card.