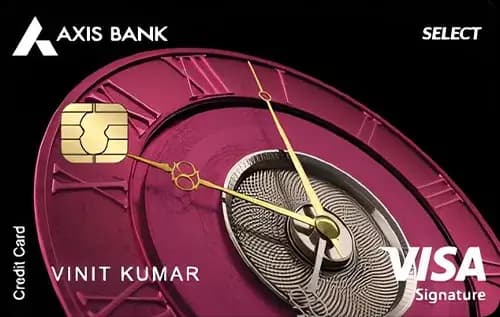
Quick Verdict
- The Axis Bank Select Credit Cardⓘ wins for everyday spend with a higher base reward rate and strong category bonuses, especially in grocery and online shopping.
- For travel and lounge access, the Axis Bank Select Credit Cardⓘ again leads with more international lounge visits and a lower forex markup.
- The ICICI Bank Rubyx Credit Cardⓘ is cheaper to hold annually due to a lower annual fee and a lower waiver threshold.
- Choose the Axis Bank Select Credit Cardⓘ if you prioritize rewards and travel perks and can meet a higher spend; pick the ICICI Bank Rubyx Credit Cardⓘ if you want a lower fee card with decent travel benefits and welcome vouchers.
Side by Side
| Detail | Axis Bank Select Credit Cardⓘ | ICICI Bank Rubyx Credit Cardⓘ |
|---|---|---|
| Annual fee | Rs 3,000 | Rs 2,000 |
| Joining fee | Rs 3,000 | Rs 3,000 |
| Fee waiver on spend | Rs 10.00 lakh | Rs 5.00 lakh |
| Reward rate | 1% base, 4% grocery, 2% online | 0.5% base, 1% dining, 1% online |
| Reward type | points | points |
| Domestic lounge | 8 per year | 8 per year |
| International lounge | 4 per year | 2 per year |
| Forex markup | 1.5% | 3.5% |
| Best suited for | rewards, grocery, lounge, travel, shopping | travel, rewards, lounge, shopping |
| Golf access | Yes | Yes |
| Concierge | No | Yes |
Rewards Compared
Spending Rs 10,000 on the Axis Bank Select Credit Cardⓘ earns Rs 100 at the base rate, with category bonuses boosting returns to Rs 400 for groceries and Rs 200 for online spends. This makes it highly rewarding for everyday categories like grocery shopping and online purchases. The card’s 4% return on grocery spend is particularly attractive for those with regular supermarket expenses.
In contrast, the ICICI Bank Rubyx Credit Cardⓘ offers a base reward of Rs 50 on Rs 10,000 spend, with category returns of Rs 100 on dining and online spends. While these rates are lower than the Axis Bank Select Credit Cardⓘ, the ICICI Rubyxⓘ provides a broader set of welcome benefits and travel-related perks, making it suitable for users prioritizing experiential rewards and travel vouchers.
Fees Compared
The Axis Bank Select Credit Cardⓘ charges an annual fee of Rs 3,000 plus a joining fee of Rs 3,000, with a waiver threshold at Rs 10 lakh annual spend, which translates to about Rs 83,333 per month. This high waiver limit means only heavy spenders will avoid the fee. The card requires approximately Rs 3 lakh in annual spend to cover the fee through base rewards alone.
The ICICI Bank Rubyx Credit Cardⓘ has a lower annual fee of Rs 2,000 and the same joining fee of Rs 3,000, with a waiver threshold at Rs 5 lakh annual spend or Rs 41,667 monthly. This makes it more accessible for moderate spenders to avoid the fee. The break-even spend to cover the base rate fee is around Rs 4 lakh annually, reflecting its lower base reward rate.
In head-to-head terms, the Axis Bank Select Credit Cardⓘ demands Rs 1,000 more annually but compensates with a higher base rate. The extra Rs 2 lakh spend needed to justify this fee difference is substantial, so only users with significant spend in high-reward categories will benefit.
Which One Should You Pick
Pick the Axis Bank Select Credit Cardⓘ if you are a heavy spender on groceries and online shopping, frequently travel, and value international lounge access with a lower forex markup. Its higher reward rates and travel benefits justify the higher fee if you can meet the waiver threshold or spend enough to cover it.
Choose the ICICI Bank Rubyx Credit Cardⓘ if you prefer a card with a lower annual fee and welcome benefits including vouchers and memberships. It suits moderate spenders who want travel perks like domestic lounges and concierge service but do not want to commit to a very high spend for fee waivers.
Skip the Axis Bank Select Credit Cardⓘ if your spend is below Rs 3 lakh annually or you rarely shop in its high-reward categories. Avoid the ICICI Bank Rubyx Credit Cardⓘ if you want maximum reward returns on everyday spends or international lounge access.
What to Check Before You Apply
- Confirm the exact spend categories and caps for reward rates, especially grocery and dining.
- Verify the redemption value of points and vouchers to ensure they meet your usage needs.
- Calculate the monthly spend needed to waive the annual fee and assess if you can comfortably meet it.
- Check the forex markup percentage if you travel internationally frequently.
- Review the domestic and international lounge access details, including any spend gates or visit limits.

Comments
No comments yet
Be the first to share your experience with this card.