Quick Verdict
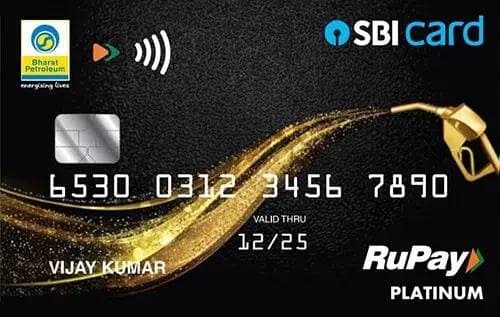
- The Yes Prosperity Edge Credit Cardⓘ wins for everyday spend due to its higher base reward rate of 0.8% compared to 0.25% on the BPCL SBI Credit Cardⓘ.
- The BPCL SBI Credit Cardⓘ is the clear winner for fuel purchases with a 4.25% reward rate versus no special fuel rate on the Yes card.
- The Yes Prosperity Edge Credit Cardⓘ offers domestic lounge access, making it better for lounge users, while the BPCL SBI Credit Cardⓘ has no lounge benefits.
- Both cards have the same forex markup of 3.5%, but the BPCL SBI Credit Cardⓘ is slightly cheaper to hold with Rs 499 annual and joining fees versus Rs 599 each on the Yes card.
- Choose the BPCL SBI Credit Cardⓘ if you primarily spend on fuel and want a low-fee first card. Opt for the Yes Prosperity Edge Credit Cardⓘ if your spending is more general, especially on dining and groceries, and you value lounge access.
Side by Side
| Detail | BPCL SBI Credit Cardⓘ | Yes Prosperity Edge Credit Cardⓘ |
|---|---|---|
| Annual fee | Rs 499 | Rs 599 |
| Joining fee | Rs 499 | Rs 599 |
| Fee waiver on spend | Rs 1.00 lakh | Rs 1.00 lakh |
| Reward rate | 0.25% base | 0.8% base |
| Reward type | points | points |
| Fuel category rate | 4.25% | Not recorded |
| Online category rate | 1.25% | Not recorded |
| Dining category rate | Not recorded | 2% |
| Grocery category rate | Not recorded | 2% |
| Domestic lounge | None | 4 per year (Rs 50,000 quarterly spend gate) |
| International lounge | None | None |
| Forex markup | 3.5% | 3.5% |
| Best suited for | fuel, first-card | rewards, dining, first-card, lounge, shopping |
Rewards Compared
On a Rs 10,000 general spend, the BPCL SBI Credit Cardⓘ earns Rs 25 in rewards at its base rate of 0.25%, while the Yes Prosperity Edge Credit Cardⓘ earns Rs 80 at 0.8%. This makes the Yes card more rewarding for typical everyday purchases excluding categories.
For category spends, the BPCL SBI Credit Cardⓘ shines on fuel with a 4.25% rate, yielding Rs 425 back on Rs 10,000 spent. It also offers 1.25% on online spends. The Yes Prosperity Edge Credit Cardⓘ does not have a fuel category bonus but gives 2% back on dining and groceries, equating to Rs 200 for each Rs 10,000 spent. This means the BPCL card is best for fuel-heavy spenders, while the Yes card benefits those spending on dining and groceries.
Fees Compared
The BPCL SBI Credit Cardⓘ charges Rs 499 each for joining and annual fees, while the Yes Prosperity Edge Credit Cardⓘ charges Rs 599 for each. Both cards waive fees with Rs 1.00 lakh annual spend, which breaks down to about Rs 8,333 per month.
Considering the higher base reward rate on the Yes card but its Rs 100 higher fees, the break-even spend to justify the extra cost is Rs 18,182 annually. Users spending more than this amount benefit from the Yes card’s better rewards despite the higher fees. Otherwise, the BPCL SBI Credit Cardⓘ is more cost-effective.
Which One Should You Pick
Choose the BPCL SBI Credit Cardⓘ if you are a fuel-focused spender or a first-time credit card user looking for a low-cost card with good fuel rewards. It is not suitable for those who want lounge access or better rewards on dining and groceries.
The Yes Prosperity Edge Credit Cardⓘ suits users who spend broadly on dining, groceries, and shopping, and who value domestic lounge access. It is also a good first card but less ideal if fuel is your main category or if you want the cheapest fees.
Overall, if your spend is mostly fuel, pick the BPCL SBI Credit Cardⓘ. For diversified spending with lounge perks, the Yes Prosperity Edge Credit Cardⓘ is the better choice. Skip the BPCL card if you want lounge access or higher base rewards. Skip the Yes card if you want the lowest fees or focus on fuel.
What to Check Before You Apply
- Verify any caps on category rewards to ensure your spend qualifies fully.
- Understand the redemption value of points or vouchers to confirm the effective return.
- Calculate the monthly spend needed to waive the annual fee and if it fits your budget.
- Beware of the 3.5% forex markup on foreign transactions, which is standard but costly for frequent travelers.
- For the Yes Prosperity Edge Credit Cardⓘ, note the Rs 50,000 quarterly spend gate to access domestic lounges.

Comments
No comments yet
Be the first to share your experience with this card.