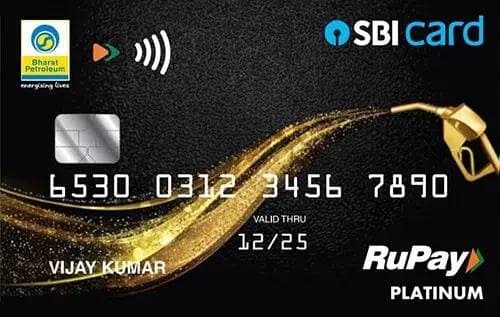
Quick Verdict
- The Yes Bank Rupay Credit Cardⓘ wins for everyday spend with a higher base reward rate of 1% compared to 0.25% on the BPCL SBI Credit Cardⓘ.
- For fuel spend, the BPCL SBI Credit Cardⓘ dominates, offering a 4.25% reward rate, making it ideal for regular fuel buyers.
- The Yes Bank Rupay Credit Cardⓘ offers domestic lounge access (4 per year) subject to quarterly spend, while the BPCL SBI Credit Cardⓘ has no lounge benefits.
- The Yes Bank Rupay Credit Cardⓘ is cheaper to hold with no joining or annual fees, whereas the BPCL SBI Credit Cardⓘ charges Rs 499 for both, waived only above Rs 1 lakh annual spend.
- Choose the BPCL SBI Credit Cardⓘ if you prioritize fuel rewards and are comfortable paying fees or meeting waiver criteria. Opt for the Yes Bank Rupay Credit Cardⓘ if you want a fee-free card with better rewards on groceries, dining, UPI, and some lounge access.
Side by Side
| Detail | BPCL SBI Credit Cardⓘ | Yes Bank Rupay Credit Cardⓘ |
|---|---|---|
| Annual fee | Rs 499 | Nil (lifetime free) |
| Joining fee | Rs 499 | Nil (lifetime free) |
| Fee waiver on spend | Rs 1.00 lakh | Rs 75,000 |
| Reward rate | 0.25% base; 4.25% fuel; 1.25% online | 1% base; 3% grocery; 3% dining; 1% UPI |
| Reward type | points | points |
| Domestic lounge | None | 4 per year (Rs 50,000 quarterly spend gate) |
| International lounge | None | None |
| Forex markup | 3.5% | 3.5% |
| Best suited for | fuel, first-card | UPI-Rupay, rewards, grocery, first-card, shopping |
Rewards Compared
On a Rs 10,000 spend, the BPCL SBI Credit Cardⓘ yields Rs 25 at the base rate, which is significantly lower than the Rs 100 earned on the Yes Bank Rupay Credit Cardⓘ. However, category rewards tell a different story. For fuel expenses, the BPCL SBI Credit Cardⓘ offers a stellar 4.25% return, translating to Rs 425 on Rs 10,000 spent, which is unmatched by the Yes Bank Rupay Credit Cardⓘ that does not provide fuel-specific rewards.
Conversely, the Yes Bank Rupay Credit Cardⓘ shines in grocery and dining categories, offering 3% rewards or Rs 300 on Rs 10,000 spend in each category. It also provides a 1% return on UPI transactions, making it versatile for everyday shopping and bill payments. The BPCL SBI Credit Cardⓘ offers a modest 1.25% return on online spends, equivalent to Rs 125 per Rs 10,000, which is lower than Yes Bank’s base and category rates.
Fees Compared
The BPCL SBI Credit Cardⓘ charges Rs 499 as both joining and annual fees. These fees can be waived if the cardholder spends Rs 1,00,000 annually, which breaks down to Rs 8,333 per month. The break-even spend to cover the annual fee at the base reward rate is approximately Rs 1,99,600, or about Rs 2 lakh. This means if you spend less than this amount without focusing on fuel rewards, the fee may not justify the returns.
In contrast, the Yes Bank Rupay Credit Cardⓘ is free for life with no joining or annual fees. It does have a fee waiver threshold of Rs 75,000 annual spend, but since there are no fees to waive, this is likely related to lounge access eligibility. The card also requires Rs 50,000 quarterly spend to access domestic lounges. Overall, Yes Bank Rupay Credit Cardⓘ is more cost-effective for low to moderate spenders.
Which One Should You Pick
Choose the BPCL SBI Credit Cardⓘ if you are a fuel-heavy spender and can meet or exceed the Rs 1 lakh annual spend to waive fees. It is also suitable as a first credit card for those who want a focused reward on fuel purchases. However, skip this card if you rarely spend on fuel or want lounge access.
The Yes Bank Rupay Credit Cardⓘ is ideal for shoppers who spend regularly on groceries, dining, and UPI payments and want a fee-free card with some domestic lounge access. It suits first-time cardholders and those who prefer no-fee credit cards. Avoid this card if you need international lounge access or if fuel spend is your priority.
Overall, the Yes Bank Rupay Credit Cardⓘ offers a better everyday reward profile and lower cost of ownership, making it the preferred choice for most users. The BPCL SBI Credit Cardⓘ remains a niche option for fuel spenders willing to pay or meet waiver thresholds.
What to Check Before You Apply
- Confirm the fee waiver math carefully: Rs 1 lakh annual spend for BPCL SBI Credit Cardⓘ and Rs 75,000 for Yes Bank Rupay Credit Cardⓘ.
- Understand the redemption value of points, as both cards award points but differ in value and ease of redemption.
- Check the quarterly Rs 50,000 spend gate for domestic lounge access on the Yes Bank Rupay Credit Cardⓘ.
- Be aware of the 3.5% forex markup on both cards, which can be costly for international transactions.

Comments
No comments yet
Be the first to share your experience with this card.