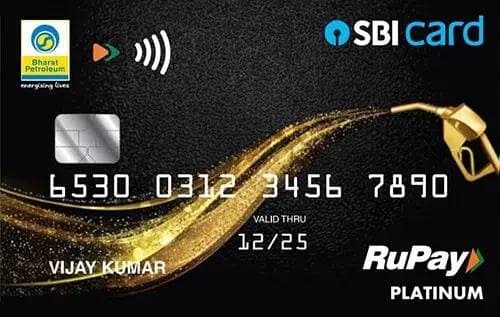
Quick Verdict
- For everyday spend rewards, the Standard Chartered Priority Visa Infinite Credit Cardⓘ wins with a 1% base reward rate versus just 0.25% from the BPCL SBI Credit Cardⓘ.
- The Standard Chartered card also leads for travel and lounge benefits, offering unlimited domestic lounge access and six international lounge visits annually.
- The BPCL SBI Credit Card has a low annual and joining fee of Rs 499 each but requires Rs 1.00 lakh annual spend to waive fees; the Standard Chartered card is lifetime free with no fees.
- Choose the BPCL SBI card if you primarily want fuel rewards and a simple first card. Opt for the Standard Chartered Priority card if you want premium travel perks, lounge access, and better reward rates without fees.
Side by Side
| Detail | BPCL SBI Credit Card | Standard Chartered Priority Visa Infinite Credit Card |
|---|---|---|
| Annual fee | Rs 499 | Nil (lifetime free) |
| Joining fee | Rs 499 | Nil (lifetime free) |
| Fee waiver on spend | Rs 1.00 lakh | None |
| Reward rate | 0.25% base; 4.25% fuel; 1.25% online | 1% base; 2% online; 2% travel |
| Reward type | Points | Points |
| Domestic lounge | None | Unlimited |
| International lounge | None | 6 per year |
| Forex markup | 3.5% | 2% |
| Best suited for | Fuel, first-card | Premium, lounge, travel, lifetime-free, shopping |
Rewards Compared
Spending Rs 10,000 on the BPCL SBI Credit Cardⓘ earns Rs 25 back at the base rate, but that jumps significantly to Rs 425 on fuel spend and Rs 125 on online purchases. This makes it very attractive for those prioritizing fuel expenses, where the effective return is 4.25%. However, outside fuel and online categories, the returns drop sharply to just 0.25%, which is quite low for general daily spending.
In contrast, the Standard Chartered Priority Visa Infinite Credit Cardⓘ offers a solid 1% base return, translating to Rs 100 per Rs 10,000 spent, four times higher than the BPCL SBI card’s base rate. It also provides 2% rewards on online and travel spends, giving Rs 200 back on Rs 10,000 in these categories. This card is clearly geared towards a more premium user who spends across categories including travel, with consistently better returns than the BPCL SBI card except for fuel.
Fees Compared
The BPCL SBI Credit Cardⓘ charges Rs 499 as a joining fee and an annual fee of Rs 499. These fees are waived if the cardholder spends Rs 1.00 lakh annually, which breaks down to about Rs 8,333 per month. To even cover the annual fee purely through base rewards, a cardholder would need to spend approximately Rs 1,99,600 (about Rs 2 lakh) annually at the base rate, which is a high bar unless most spending is on fuel.
The Standard Chartered Priority Visa Infinite Credit Cardⓘ is lifetime free with no joining or annual fees. This immediately eliminates any fee recovery considerations, making it easier to accumulate rewards without worrying about break-even spends or fee waivers.
Which One Should You Pick
Choose the BPCL SBI Credit Cardⓘ if your primary spend category is fuel and you want a straightforward, low-fee credit card option with decent rewards in that segment. It also makes sense for first-time credit card users looking for a simple card with low upfront costs. However, if your spend is more diversified or you travel frequently, this card may feel limited and costly if you cannot meet the fee waiver spend.
The Standard Chartered Priority Visa Infinite Credit Cardⓘ is ideal for premium customers who want a no-fee card that rewards a range of categories including travel and shopping, and offers excellent lounge access benefits. It suits those with a Priority Banking relationship and a taste for international travel and lifestyle perks. Avoid this card if you do not qualify for Priority Banking or if you want a card focused on fuel rewards.
For a decisive call, the Standard Chartered Priority Visa Infinite Credit Card is the better all-rounder in 2026, offering superior reward rates, no fees, and premium benefits. The BPCL SBI Credit Card is a niche choice for budget-conscious fuel spenders or credit card beginners.
What to Check Before You Apply
- Confirm the Rs 1.00 lakh annual spend requirement to waive BPCL SBI card fees and ensure you can meet it comfortably.
- Understand the redemption values and reward point expiry policies for both cards, as points may have different usability.
- Consider the forex markup: BPCL SBI charges 3.5% on foreign currency spends, while Standard Chartered charges a lower 2%, important if you travel internationally.
- Check the lounge network and access terms: unlimited domestic lounges and six international visits with Standard Chartered vs none with BPCL SBI.

Comments
No comments yet
Be the first to share your experience with this card.