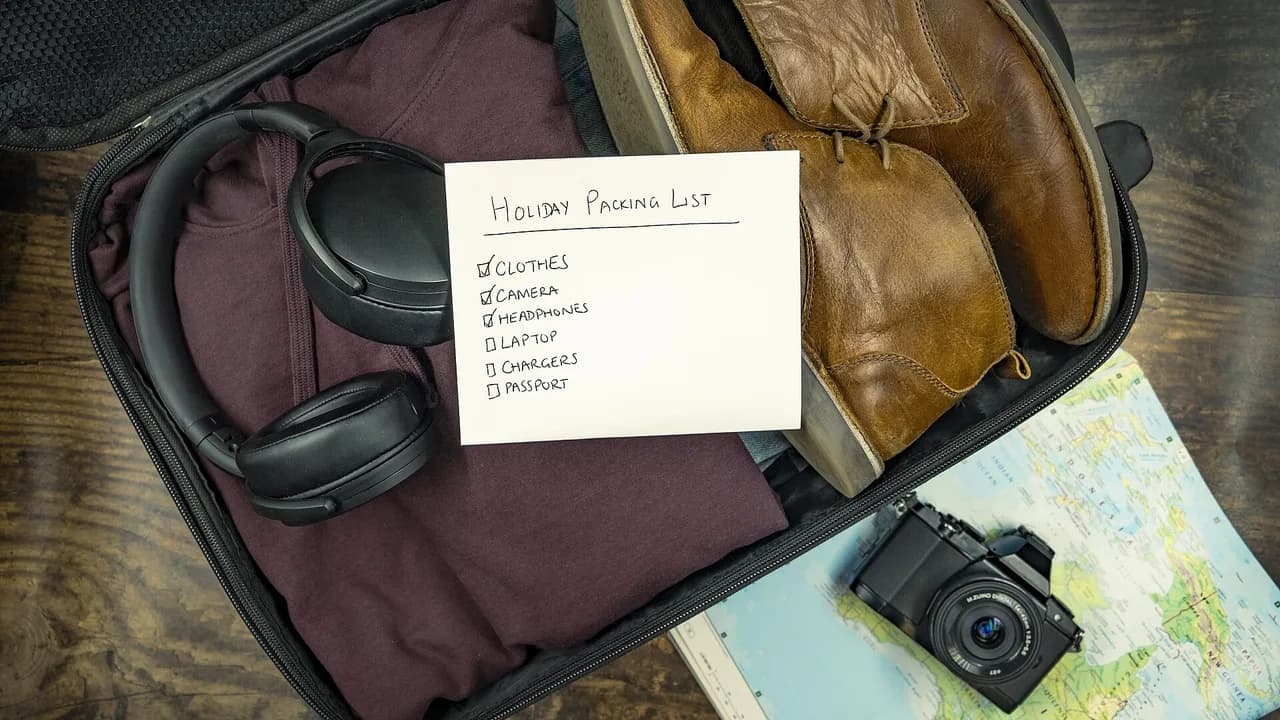
Buying a Suitcase on EMI or Full Payment: The Real Math on ₹8,000–15,000 Luggage
Published: 18 October 2026 Category: buying-guides | cardbuzz
A decent hard-shell suitcase in India costs roughly ₹8,000 to ₹15,000 at full price, which puts luggage in the awkward middle: too expensive to be an impulse buy, too cheap for the tenured planning that goes into a laptop purchase. That is exactly why the payment decision matters — most buyers pick EMI or full payment on instinct, and instinct is usually wrong about which one costs less.
How the choice actually works
At the checkout of most Indian luggage retailers — offline chains, brand stores, and big marketplaces — the card payment screen typically offers two options for the same bill: pay the full amount now, or convert it into EMI, either no-cost EMI (where the interest is offset as an upfront discount by the merchant or bank) or standard EMI at the bank's prevailing rate.
Full payment is the simplest route. The buyer earns the card's standard reward points or cashback on the entire amount in one shot, and there is no interest, no processing fee, and no locked credit limit to think about. EMI splits the bill into 3, 6, 9 or 12 monthly instalments. No-cost EMI on paper costs nothing extra — but it often displaces something else: the discount that the merchant would otherwise offer, or the extra reward points the card would earn at full rates on non-EMI transactions. Some cards also award fewer reward points on EMI conversions.
A worked example
Consider an illustrative suitcase priced at ₹12,000. Suppose the card earns 1% effective value in rewards on full payment, and a no-cost EMI option is available at 6 months.
| Option | Paid to merchant | Rewards value | Extra cost | Net cost |
|---|---|---|---|---|
| Full payment | ₹12,000 | ≈ ₹120 | Nil | ≈ ₹11,880 |
| No-cost EMI × 6 | ₹12,000 | Possibly reduced or zero | Nil interest, possible processing fee | ≈ ₹12,000 (or + fee) |
| Standard EMI × 12 at 16% p.a. | ₹12,000 | Usually excluded | ≈ ₹1,050 interest (approx.) | ≈ ₹13,050 |
These figures are illustrative — the EMI conversion fee (often ₹99–199 plus GST where applicable) and the interest rate vary by bank, so checking the exact conversion terms before confirming is essential. The broader point is robust: no-cost EMI is genuinely attractive when rewards are also earned; standard EMI on a ₹12,000 suitcase adds a meaningful surcharge for no reason other than spreading a manageable bill.
When EMI makes sense
EMI earns its place in three situations. First, when a buyer is purchasing luggage for the whole family — two or three suitcases at once can cross ₹30,000, and splitting that into 3 or 6 no-cost instalments smooths the month without a surcharge. Second, when the no-cost EMI offer comes bundled with a bank discount that is not available on full payment — some marketplace sale events apply an extra card-offer discount only to EMI transactions, and that can genuinely beat the rewards lost. Third, when cash flow is genuinely tight before a trip — a last-minute luggage buy plus visa fees plus flights can collide in one billing cycle.
When full payment wins
For a single suitcase, full payment usually wins. The bill is small enough that most cardholders absorb it in one cycle, the reward points land at full rates, and there is no processing fee or credit-limit lock-in to manage. It also keeps the next statement clean, which matters if the card is going to be used for the trip itself — hotels and flight bookings abroad benefit from a fully available limit.
A practical checklist before paying
- Confirm whether the no-cost EMI on offer also earns reward points — some issuers exclude EMI from rewards.
- Ask about the conversion fee and whether GST applies on it.
- Compare the all-in EMI total (principal + interest + fees) against the full-payment price minus rewards value.
- Check whether the merchant's bank-offer discount requires EMI or applies to full payment too.
- If travelling internationally soon, keep enough free credit limit for the trip.
The luggage itself lasts a decade; the payment method affects the bill for months. Running the numbers takes two minutes and is worth every second of it.
Comments
No comments yet
Be the first to share your experience with this card.