Quick Verdict
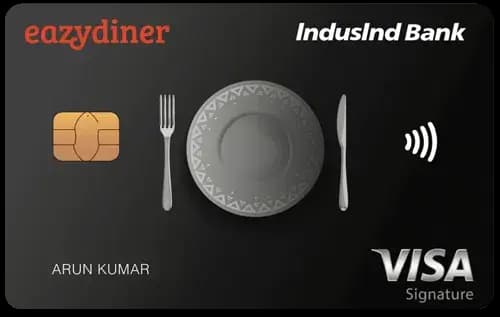
- The Eazydiner Indusind Bank Credit Cardⓘ wins for everyday dining spend with a 10% reward rate, significantly higher than SBI Prime.
- The SBI Prime Credit Cardⓘ is better for travel and lounge access, offering more domestic and international lounge visits plus golf access.
- Both cards have the same joining and annual fee of Rs 2,999, but Eazydiner offers a lower waiver threshold of Rs 2.00 lakh annual spend versus Rs 3.00 lakh for SBI Prime.
- Pick Eazydiner Indusind if your focus is dining rewards and restaurant discounts; choose SBI Prime if you value premium travel privileges and broader category rewards.
Side by Side
| Detail | Eazydiner Indusind Bank Credit Card ⓘ | SBI Prime Credit Card ⓘ |
|---|---|---|
| Annual fee | Rs 2,999 | Rs 2,999 |
| Joining fee | Rs 2,999 | Rs 2,999 |
| Fee waiver on spend | Rs 2.00 lakh | Rs 3.00 lakh |
| Reward rate | 0.7% base, 10% dining | 0.5% base, 2.5% dining/grocery/utilities |
| Reward type | points | points |
| Domestic lounge | 4 per year | 8 per year |
| International lounge | None | 4 per year |
| Forex markup | 3.5% | 3.5% |
| Best suited for | dining, rewards, lounge, travel | rewards, dining, lounge, grocery, travel, shopping |
Rewards Compared
Spending Rs 10,000 on the Eazydiner Indusind Bank Credit Cardⓘ earns a base return of Rs 70, but this jumps dramatically to Rs 1,000 when spent on dining, thanks to its 10% category rate. This card is especially rewarding for users who frequently dine out or spend on restaurants and bars, leveraging its 25-50% dining discounts and bonus points on hotels, travel, entertainment, and shopping.
In contrast, the SBI Prime Credit Cardⓘ yields Rs 50 on a generic Rs 10,000 spend and Rs 250 in dining, grocery, or utilities categories at 2.5%. It offers a more diversified rewards spread across categories and is suitable for users with varied spending habits including groceries and utilities, but with a noticeably lower dining rate compared to Eazydiner. The SBI Prime also provides birthday spend bonuses, enhancing rewards for specific occasions.
Fees Compared
Both cards charge Rs 2,999 for joining and annual fees. The Eazydiner Indusind Bank Credit Cardⓘ requires Rs 2.00 lakh annual spend, or approximately Rs 16,667 monthly, to waive the annual fee. The SBI Prime Credit Cardⓘ demands a higher Rs 3.00 lakh annual spend, about Rs 25,000 each month, for fee waiver.
In terms of break-even, Eazydiner’s higher base and category rates mean you need to spend around Rs 4.28 lakh annually to cover its fees with rewards, whereas SBI Prime requires a heftier Rs 6.00 lakh due to its lower reward rates. This makes Eazydiner more accessible for fee waiver and value extraction at moderate to high spend levels.
Which One Should You Pick
Choose the Eazydiner Indusind Bank Credit Cardⓘ if your primary spend is on dining and you want strong rewards and discounts in that category. Its complimentary EazyDiner Prime membership and hotel stay voucher add value for food lovers and occasional travelers. It’s less suited for those who frequently travel internationally or seek extensive lounge access.
The SBI Prime Credit Cardⓘ is ideal for premium travelers who value multiple domestic and international lounge visits, golf access, and a broader rewards spread including groceries and utilities. Its rich premium benefits like Priority Pass membership and Club ITC Silver Tier Membership cater well to lifestyle and travel enthusiasts. However, if you mainly want dining rewards or lower fee waiver thresholds, SBI Prime may not be the best fit.
Overall, for dining-centric users with moderate spending, Eazydiner is the clear winner. For travel-focused cardholders wanting lounge privileges and wider category rewards, SBI Prime holds the edge. Those uninterested in lounge access or with low annual spend should skip SBI Prime due to its higher waiver bar.
What to Check Before You Apply
- Verify if the dining discount and rewards have monthly or annual caps that limit benefits.
- Understand the redemption process and value of points especially since both cards use points, which may differ in actual worth.
- Calculate if your monthly spend comfortably meets the fee waiver threshold to avoid paying Rs 2,999 annually.
- Consider the 3.5% forex markup on foreign currency spends, common on both cards, which can impact cost during overseas usage.
- Check the locations of domestic and international lounges accessible, ensuring they align with your travel routes and preferences.

Comments
No comments yet
Be the first to share your experience with this card.