Quick Verdict
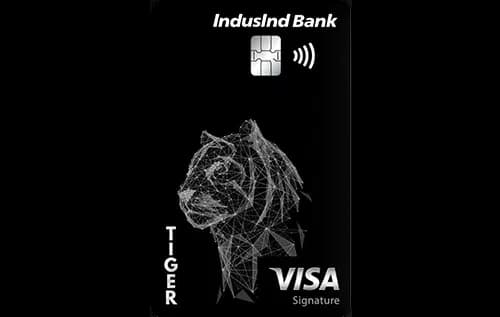
- The IndusInd Bank Tiger Credit Cardⓘ wins for everyday spend with a higher base reward rate of 1%, compared to 0.5% on the HDFC card.
- For travel and domestic lounge access, the HDFC Bank Rupay IRCTC Credit Cardⓘ stands out, offering 5% rewards on travel and 8 domestic lounge visits annually.
- The IndusInd Tiger card is cheaper to hold with no joining or annual fees, while the HDFC IRCTC card has a Rs 500 joining fee.
- Choose the IndusInd Tiger card if you want a lifetime-free card with solid online rewards and occasional lounge access. Pick the HDFC IRCTC card if you prioritize travel rewards and more lounge visits and don’t mind the joining fee.
Side by Side
| Detail | IndusInd Bank Tiger Credit Cardⓘ | HDFC Bank Rupay IRCTC Credit Cardⓘ |
|---|---|---|
| Annual fee | Nil (lifetime free) | Nil (lifetime free) |
| Joining fee | Nil (lifetime free) | Rs 500 |
| Fee waiver on spend | Rs 1.50 lakh annually (Rs 12,500/month) | |
| Reward rate | 1% base, 2.5% online, 1% UPI | 0.5% base, 5% travel, 1% UPI |
| Reward type | Points | Points |
| Domestic lounge | 4 per year (Rs 40,000 quarterly spend gate) | 8 per year (Rs 75,000 quarterly spend gate) |
| International lounge | None | None |
| Forex markup | 3.5% | 3.5% |
| Best suited for | Lifetime-free, UPI-Rupay, rewards, lounge, travel | Travel, UPI-Rupay, first card |
Rewards Compared
The IndusInd Bank Tiger Credit Cardⓘ offers a base reward rate of 1%, which means Rs 100 back on Rs 10,000 spent. It excels with a 2.5% reward rate on online spends, returning Rs 250 on the same Rs 10,000, making it attractive for digital shoppers. UPI transactions yield the base 1% rate. This card’s rewards lean towards consistent returns on everyday and online spending, fitting users who want steady benefits without complex category tracking.
The HDFC Bank Rupay IRCTC Credit Cardⓘ, however, has a lower base rate of 0.5%, yielding Rs 50 on Rs 10,000 spent overall. It compensates by offering a significant 5% reward rate on travel spends, giving Rs 500 back on Rs 10,000, which is double the Tiger card’s best category return. UPI transactions earn 1%, matching the Tiger card’s UPI rewards. This card suits travel enthusiasts who concentrate their spend in travel categories to maximize rewards.
Fees Compared
The IndusInd Bank Tiger Credit Cardⓘ stands out with no joining or annual fees ever, making it truly lifetime free. There is no fee waiver threshold to meet, so cardholders pay zero fees regardless of spending patterns.
The HDFC Bank Rupay IRCTC Credit Cardⓘ charges a Rs 500 joining fee upfront. While its annual fee is nil, this fee can be waived if you spend Rs 1.50 lakh annually, which translates to Rs 12,500 monthly. This waiver threshold is quite high, so casual or low spenders will effectively pay the joining fee without any fee relief. The Tiger card is simpler and cheaper to hold for low or moderate spenders.
Which One Should You Pick
Pick the IndusInd Bank Tiger Credit Cardⓘ if you want a no-fee card that rewards online and UPI spends well. It is ideal for those who dislike fees, want a straightforward rewards structure, and appreciate some domestic lounge access with a reasonable quarterly spend of Rs 40,000. Its lifetime free status and golf access add to its appeal for lifestyle benefits without cost.
Go for the HDFC Bank Rupay IRCTC Credit Cardⓘ if you are a frequent traveller focused on travel rewards and want more domestic lounge visits, up to 8 per year. If you regularly spend over Rs 12,500 a month, you can waive the joining fee, and the 5% travel reward rate will deliver superior returns. This card also suits first-time credit card users who want a modest welcome benefit and travel-focused perks.
Skip the Tiger card if you need more lounge visits or higher travel rewards. Skip the HDFC IRCTC card if you want a genuinely free card or do not meet the spending required for fee waiver, as the joining fee then becomes a sunk cost.
What to Check Before You Apply
- Confirm the quarterly spend gates for lounge access (Rs 40,000 for Tiger, Rs 75,000 for HDFC IRCTC) to ensure you can unlock these benefits.
- Check if the reward redemption options suit your preferences and if points expire or have caps.
- Understand the fee waiver criteria and compare your typical spend to avoid paying unnecessary fees.
- Be aware of the 3.5% forex markup on foreign currency spends, which is standard but costly for frequent international travelers.
- Verify the locations of the domestic lounges and whether they are convenient for your travel routes.

Comments
No comments yet
Be the first to share your experience with this card.