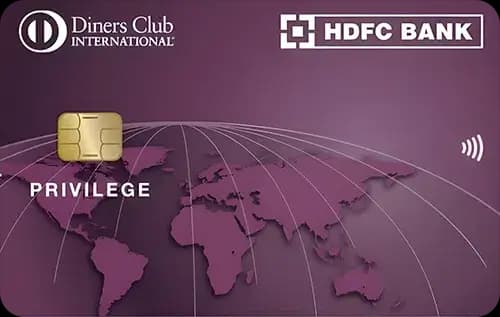
Quick Verdict
- The HDFC Bank Diners Club Privilege Credit Cardⓘ wins for everyday spend due to its higher base reward rate and excellent online category returns.
- For travel and lounge access, the HDFC Diners Club Privilege card offers better value with more domestic and international lounge visits and concierge services.
- The Standard Chartered Rewards Credit Cardⓘ is cheaper to hold initially with no joining fee and a lower waiver spend requirement.
- Choose the HDFC Bank Diners Club Privilege if you spend heavily in online, travel, and dining categories and want premium benefits. Opt for Standard Chartered Rewards if you want a straightforward, no-joining-fee card with decent rewards and occasional lounge access.
Side by Side
| Detail | HDFC Bank Diners Club Privilege Credit Cardⓘ | Standard Chartered Rewards Credit Cardⓘ |
|---|---|---|
| Annual fee | Rs 1,000 | Rs 1,000 |
| Joining fee | Rs 1,000 | Nil (lifetime free) |
| Fee waiver on spend | Rs 3.00 lakh | Rs 1.00 lakh |
| Reward rate | 2.67% base, 13.33% online | 1% base, 4% online and dining |
| Reward type | points | points |
| Domestic lounge | 8 per year | 4 per year (1 per calendar quarter, spend-gated) |
| International lounge | 4 per year | None |
| Forex markup | 2% | 3.5% |
| Best suited for | rewards, dining, lounge, shopping, travel | rewards, dining, first-card, shopping, lounge |
Rewards Compared
The HDFC Bank Diners Club Privilege Credit Cardⓘ offers a strong base reward rate of 2.67%, which translates to Rs 267 back on Rs 10,000 spent. Its online spend category is particularly lucrative, with a 13.33% effective return, giving Rs 1,333 back on Rs 10,000 spent in that category. This makes it highly attractive for users with significant online shopping or dining expenses who want to maximize rewards.
On the other hand, the Standard Chartered Rewards Credit Cardⓘ provides a base reward rate of 1%, yielding Rs 100 on Rs 10,000 spend. It offers 4% rewards on both online and dining categories, which means Rs 400 back on Rs 10,000 spent in those segments. While this is better than its base rate, it still falls short of the HDFC Diners Club Privilege card’s category rewards, especially online. The Standard Chartered card is better suited for moderate spenders who prefer simplicity and occasional category boosts.
Fees Compared
The HDFC Bank Diners Club Privilege card charges an annual fee of Rs 1,000 and a joining fee of Rs 1,000. To waive the annual fee, you need to spend Rs 3.00 lakh annually or about Rs 25,000 per month. The break-even spend to cover the annual fee through base rewards alone is approximately Rs 37,453. This means frequent spenders will find the fee justifiable given the high rewards.
The Standard Chartered Rewards Credit Card has no joining fee and an annual fee of Rs 1,000. The fee waiver requires a lower annual spend of Rs 1.00 lakh or about Rs 8,333 per month, making it easier to keep the card fee-free if you spend moderately. However, the spend needed to cover the fee through base rewards alone is about Rs 1.00 lakh, reflecting its lower reward rates. For low to medium spenders, this card offers a simpler and cheaper option.
Which One Should You Pick
Choose the HDFC Bank Diners Club Privilege Credit Cardⓘ if you are a heavy spender on online shopping, dining, and travel. It suits those who value premium benefits such as multiple domestic and international lounge accesses, concierge services, and complimentary memberships to Swiggy One and Times Prime. The card’s higher forex fee of 2% is reasonable given the rewards and lounge access. Avoid this card if your spend is below Rs 25,000 per month, as the fee waiver threshold is high.
The Standard Chartered Rewards Credit Cardⓘ is ideal for first-time credit card users or those who prefer a simple, no-joining-fee option with decent rewards on everyday spends. It benefits users who want a lower fee waiver threshold and occasional domestic lounge visits without much fuss. However, avoid this card if you travel internationally often or want richer rewards in premium categories, as its forex markup is high and international lounge access is absent.
In conclusion, for high spenders seeking premium travel and dining rewards, the HDFC Diners Club Privilege card stands out. For budget-conscious or occasional users prioritizing no joining fee and easier fee waivers, the Standard Chartered Rewards card is a better fit.
What to Check Before You Apply
- Confirm the quarterly or annual caps on lounge visits, especially for Standard Chartered’s spend-gated domestic lounges.
- Understand the redemption values and how points convert to actual benefits, as reward types for both cards are points.
- Calculate your monthly spend realistically to see if you can meet the fee waiver thresholds of Rs 25,000 and Rs 8,333 respectively.
- Check the forex markup fees carefully if you plan to use the card abroad, as HDFC charges 2% and Standard Chartered 3.5%.
- Verify the locations and partner airports of lounges you can access to ensure they fit your travel patterns.

Comments
No comments yet
Be the first to share your experience with this card.