Quick Verdict
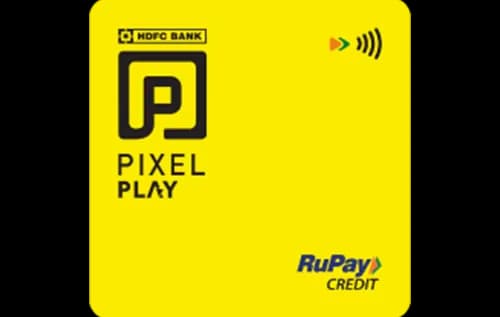
- For everyday spend, especially online and utility bills, the HDFC Bank Pixel Play Credit Card ⓘ offers superior cashback rates.
- For a zero-fee, no-commitment card, the Yes Bank Pop Club Credit Card ⓘ wins as it comes with no joining or annual fees.
- Neither card provides domestic or international lounge access, and both charge a 3.5% forex markup.
- Pick the Pixel Play for higher category rewards if you spend heavily online or on utilities; choose the Pop Club if you want a simple, lifetime-free cashback card with no fees.
Side by Side
| Detail | HDFC Bank Pixel Play Credit Card ⓘ | Yes Bank Pop Club Credit Card ⓘ |
|---|---|---|
| Annual fee | Rs 500 | Nil (lifetime free) |
| Joining fee | Rs 500 | Nil (lifetime free) |
| Fee waiver on spend | Rs 1.00 lakh | None |
| Reward rate | 1% base | 1% base |
| Reward type | Cashback | Cashback |
| Domestic lounge | None | None |
| International lounge | None | None |
| Forex markup | 3.5% | 3.5% |
| Best suited for | Cashback, first-card, shopping | Lifetime-free, cashback, UPI, shopping |
Rewards Compared
The HDFC Bank Pixel Play Credit Card ⓘ delivers a base cashback of Rs 100 per Rs 10,000 spent, aligned with the Yes Bank Pop Club Credit Card ⓘ which also offers Rs 100 per Rs 10,000 in base cashback. However, Pixel Play clearly excels in category spending with 5% cashback on online spends, yielding Rs 500 per Rs 10,000, and 3% on utilities, providing Rs 300 per Rs 10,000. This makes it highly rewarding for users who shop online or pay utility bills through the card. In contrast, the Pop Club card offers a flat 1% cashback on UPI spends and does not differentiate reward rates by category, limiting upside in specific spend areas.
Fees Compared
The Pixel Play card carries a joining fee of Rs 500 and an annual fee of Rs 500. These fees are waived if the cardholder spends Rs 1.00 lakh annually, which breaks down to Rs 8,333 per month. For base cashback alone to cover the annual fee without relying on category bonuses, a spend of Rs 50,000 per year is required. Meanwhile, the Pop Club card is truly lifetime free, with no joining or annual fees and no waiver conditions. For users wary of fees, the Pop Club card offers a clear cost advantage, especially for lower spenders who may find it hard to meet the waiver threshold on the Pixel Play.
Which One Should You Pick
Choose the HDFC Bank Pixel Play Credit Card ⓘ if you are an online shopper or pay significant utility bills and can comfortably spend over Rs 8,333 per month to waive the fees. This card maximizes cashback in these categories and offers a modest welcome benefit, making it suitable as a first credit card for those who want to earn more on targeted spends. However, if you prefer a no-fee, no-hassle card with decent flat cashback and you frequently use UPI for payments, the Yes Bank Pop Club Credit Card ⓘ is a solid choice. It suits casual spenders and those who dislike fee structures altogether.
Skip the Pixel Play if you do not spend enough monthly to waive fees or if you want a simple lifetime-free card without spending commitments. Avoid the Pop Club if you want to maximize rewards on specific categories like online shopping and utilities, where the Pixel Play clearly outperforms.
What to Check Before You Apply
- Ensure your monthly spend meets or exceeds Rs 8,333 if you want to avoid annual fees on the Pixel Play card.
- Note that both cards charge a 3.5% foreign exchange markup, making them expensive for international spends.
- Confirm the redemption options for cashback and any caps on category rewards, especially for Pixel Play.
- Neither card offers lounge access, so if airport lounge visits are important, look elsewhere.

Comments
No comments yet
Be the first to share your experience with this card.