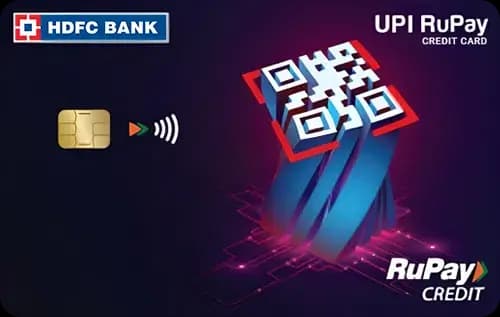
Quick Verdict
- For everyday spend, the HDFC Bank UPI Rupay Credit Cardⓘ wins with higher cashback rates in grocery and dining categories.
- Neither card offers domestic or international lounge access, so travel perks are not a differentiator here.
- The Rupay card is cheaper to hold with just Rs 99 annual and joining fee, compared to Rs 499 each on the Standard Chartered Smart Credit Cardⓘ.
- Choose the Rupay cardⓘ if you want a simple, low-cost cashback card with no fee worries and spend mainly on groceries or dining. Opt for Standard Chartered Smartⓘ only if you spend heavily online and can meet the Rs 1.20 lakh annual fee waiver.
Side by Side
| Detail | HDFC Bank UPI Rupay Credit Cardⓘ | Standard Chartered Smart Credit Cardⓘ |
|---|---|---|
| Annual fee | Rs 99 | Rs 499 |
| Joining fee | Rs 99 | Rs 499 |
| Fee waiver on spend | None | Rs 1.20 lakh per year (Rs 10,000 per month) |
| Reward rate | 1% base, 3% on grocery and dining, 1% on UPI | 1% base, 2% on online spend |
| Reward type | Cashback | Cashback |
| Domestic lounge | None | None |
| International lounge | None | None |
| Forex markup | 3.5% | 3.5% |
| Best suited for | UPI-Rupay, lifetime-free, cashback, first card, shopping | Cashback, shopping, first card |
Rewards Compared
Spending Rs 10,000 on the HDFC Bank UPI Rupay Credit Cardⓘ nets Rs 100 cashback at the base rate. However, the Rupay card shines in grocery and dining categories, offering Rs 300 back per Rs 10,000 spent in each. If your spend is concentrated in groceries or dining, this card delivers significantly better returns than the Standard Chartered Smart Credit Cardⓘ, which offers 2% cashback (Rs 200) on online spending and 1% (Rs 100) otherwise.
Thus, the Rupay card is better for offline everyday categories like groceries and dining, while Standard Chartered Smartⓘ is more rewarding if your spend is largely online. Both cards yield Rs 100 cashback on generic spend of Rs 10,000.
Fees Compared
The HDFC Bank UPI Rupay Credit Cardⓘ charges a mere Rs 99 for joining and annual fee, with no fee waiver conditions, making it effectively lifetime free for low spenders. The card breaks even on fee versus base rewards at around Rs 9,900 annual spend.
In contrast, the Standard Chartered Smart Credit Cardⓘ demands Rs 499 for joining and annual fees but offers a waiver if you spend Rs 1.20 lakh annually, or Rs 10,000 monthly. The Rupay card requires much less spend to cover fees, so it is better for light to moderate spenders, while Standard Chartered Smartⓘ suits high spenders who can easily meet the waiver threshold.
Neither card offers lounge access to justify the fee difference.
Which One Should You Pick
The HDFC Bank UPI Rupay Credit Cardⓘ is ideal if you want a low-fee, no-frills cashback card that rewards grocery and dining spend handsomely. Its lifetime free nature and low break-even spend make it great as a first credit card or for those who prefer offline shopping categories. Avoid this card if you are a heavy online spender or plan significant foreign currency transactions.
The Standard Chartered Smart Credit Cardⓘ is better suited for online shoppers who can spend at least Rs 1.20 lakh annually to waive fees. Its 2% cashback on online spend rewards digital buyers more than the Rupay card. However, the higher fees and lack of lounge access mean it only pays off for high spenders. Skip it if you spend less than Rs 10,000 monthly or want rewards in offline categories.
Overall, the HDFC Bank UPI Rupay Credit Cardⓘ is the better pick for most everyday users due to its low cost and strong category cashback. Choose Standard Chartered Smartⓘ only if you are a heavy online spender.
What to Check Before You Apply
- Confirm your monthly spend patterns match the fee waiver thresholds, especially for Standard Chartered Smartⓘ.
- Check if your preferred spend categories align with the card’s higher cashback rates such as grocery/dining or online.
- Understand that forex markup is 3.5% on both cards, so avoid foreign currency spend if possible.
- Neither card offers domestic or international lounge access, so don’t expect travel perks.

Comments
No comments yet
Be the first to share your experience with this card.