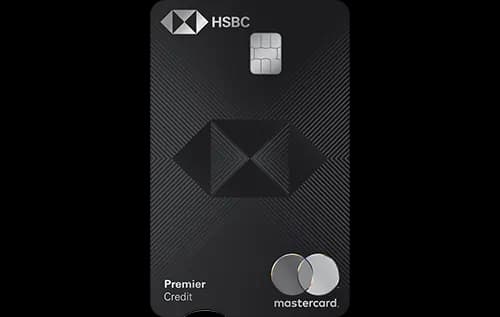
Quick Verdict
- For everyday spend, the ICICI Bank Emeralde Private Metal Credit Cardⓘ wins with a higher base reward rate of 3% versus 1% on the HSBC card.
- For travel and lounge access, both cards offer unlimited domestic and international lounge visits and a 3% reward rate on travel spend, making them equally strong.
- The HSBC Premier Metal Credit Cardⓘ is more expensive to hold, with an annual fee of Rs 20,000 and joining fee of Rs 12,000, compared to Rs 12,499 for both on the ICICI Emeralde.
- Choose the HSBC card if you prioritize lower forex markup and premium concierge/golf access with a lifetime-free feel. Opt for the ICICI Emeralde if you want higher rewards on all spends and lower fees.
Side by Side
| Detail | HSBC Premier Metal Credit Cardⓘ | ICICI Bank Emeralde Private Metal Credit Cardⓘ |
|---|---|---|
| Annual fee | Rs 20,000 | Rs 12,499 |
| Joining fee | Rs 12,000 | Rs 12,499 |
| Fee waiver on spend | Not recorded | Not recorded |
| Reward rate | 1% base, 3% on online & travel | 3% base, 3% on online, dining & travel |
| Reward type | Points | Points |
| Domestic lounge | Unlimited | Unlimited |
| International lounge | Unlimited | Unlimited |
| Forex markup | 0.99% | 2% |
| Best suited for | Premium, travel, forex, lounge, lifetime-free, shopping | Premium, travel, lounge, rewards, forex, shopping |
Rewards Compared
Spending Rs 10,000 on the HSBC Premier Metal Credit Cardⓘ earns Rs 100 back at the base rate of 1%. However, if you spend in online or travel categories, the effective reward rate rises to 3%, or Rs 300 per Rs 10,000 spent. This makes it attractive for those who focus purchases in these categories but less rewarding on general spending.
The ICICI Bank Emeralde Private Metal Credit Cardⓘ delivers a uniform 3% reward rate on almost all spends, including online, dining, and travel, translating to Rs 300 per Rs 10,000 spent across these categories. This consistent high rate makes it superior for everyday spending and rewards maximization without needing to concentrate spending in select categories.
Fees Compared
The HSBC Premier Metal Credit Cardⓘ carries a hefty annual fee of Rs 20,000 and a joining fee of Rs 12,000. There is no specified fee waiver threshold, so the cardholder must consider if the rewards and benefits offset these costs. The break-even spend to cover the base fee at 1% rewards rate is Rs 20,00,000, a substantial amount indicating this card suits very high spenders or those valuing premium perks.
In contrast, the ICICI Emeralde Private Metal Credit Cardⓘ charges Rs 12,499 for both joining and annual fees, significantly cheaper than HSBC’s fees. Its higher 3% base reward rate means the break-even spend to offset the fee is about Rs 4,16,633, much more achievable for affluent spenders aiming for strong rewards on a wider range of categories.
Which One Should You Pick
Choose the HSBC Premier Metal Credit Cardⓘ if you are a premium traveler who values very low forex markup at 0.99%, unlimited lounge access worldwide, and enjoy golf and concierge services. This card suits those who can afford to spend heavily or want a card offering exclusivity with lifetime-free style benefits. Skip it if your spend is average or you want better reward returns on everyday purchases.
The ICICI Bank Emeralde Private Metal Credit Cardⓘ is ideal for reward seekers who want a high 3% return on most spends including dining, travel, and online shopping. Its lower fees and decent forex markup at 2% make it a practical choice for premium users who want to maximize value without a very high spend requirement. Avoid this card if you prioritize the lowest forex cost or exclusive lifetime membership perks.
Overall, if your priority is rewards and fee efficiency, the ICICI Emeralde Private Metal Credit Cardⓘ wins. If you seek premium travel perks and forex savings, the HSBC Premier Metal Credit Cardⓘ is preferable.
What to Check Before You Apply
- Verify if there are any caps on the 3% category rewards as these can limit actual returns.
- Confirm the redemption value of the points for each card, as poor redemption rates can reduce reward worth.
- Understand the exact spend required monthly to waive any fees if applicable; none are specified here.
- Check the forex markup especially if you travel frequently; 0.99% vs 2% can add up significantly.
- Confirm lounge access details, including partner lounges and airport coverage to ensure suitability.

Comments
No comments yet
Be the first to share your experience with this card.