Quick Verdict
- For everyday spend, the Tata Neu Plus HDFC Credit Cardⓘ wins with a higher base reward rate of 1% and strong category bonuses.
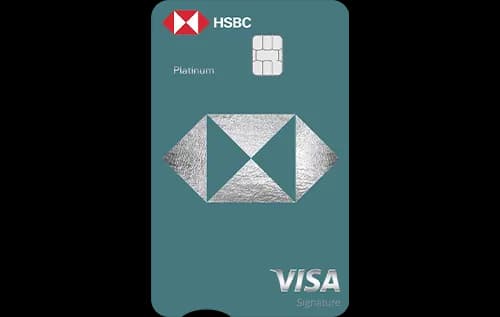
- For dining and offline shopping, the HSBC Visa Platinum Credit Cardⓘ offers competitive dining rewards with no fees.
- The HSBC Visa Platinum Credit Cardⓘ is cheaper to hold as it carries no joining or annual fee for a lifetime.
- Pick Tata Neu Plus HDFC Credit Cardⓘ if you spend heavily online, on groceries, or want domestic lounge access. Choose HSBC Visa Platinum Credit Cardⓘ if you want a simple, fee-free card focused on dining and shopping.
Side by Side
| Detail | HSBC Visa Platinum Credit Cardⓘ | Tata Neu Plus HDFC Credit Cardⓘ |
|---|---|---|
| Annual fee | Nil (lifetime free) | Rs 499 |
| Joining fee | Nil (lifetime free) | Rs 499 |
| Fee waiver on spend | Rs 1.00 lakh annually (Rs 8,333 per month) | |
| Reward rate | 0.67% | 1% |
| Reward type | points | points |
| Domestic lounge | None | 4 per year (Rs 50,000 quarterly spend gate) |
| International lounge | None | None |
| Forex markup | 3.5% | 3.5% |
| Best suited for | lifetime-free, first-card, dining, shopping | upi-rupay, shopping, first-card, grocery, lounge |
Rewards Compared
Spending Rs 10,000 on the HSBC Visa Platinum Credit Cardⓘ returns Rs 67 in value at the base rate of 0.67%. Its standout category is dining, where it offers a 2% reward rate, equating to Rs 200 on Rs 10,000 spent, making it an attractive option for food lovers and casual shoppers. However, for other spends, the returns are modest.
The Tata Neu Plus HDFC Credit Cardⓘ delivers a more generous base reward rate of 1%, which means Rs 100 back per Rs 10,000 spent. It also excels in categories like online shopping and groceries, offering 2% returns (Rs 200 per Rs 10,000 spent) in these segments, plus a 1% rate on UPI transactions. This card is clearly designed for those who spend heavily on digital and grocery platforms, providing a broader spectrum of high-value rewards.
Fees Compared
The HSBC Visa Platinum Credit Cardⓘ boasts a clean slate with zero joining and annual fees for life, making it a cost-effective option for users who prioritize fee-free usage over reward maximization. There is no need to meet any spend criteria to avoid fees.
Conversely, the Tata Neu Plus HDFC Credit Cardⓘ charges Rs 499 as both joining and annual fees. However, these fees are waived if you spend Rs 1.00 lakh annually, which is Rs 8,333 per month. The break-even spend to cover the extra Rs 499 annual fee with the higher base reward rate is approximately Rs 49,900. If you do not meet this threshold, the card’s fee can outweigh its rewards advantage.
Which One Should You Pick
Choose the HSBC Visa Platinum Credit Cardⓘ if you want a fee-free, straightforward card with a focus on dining rewards and occasional shopping. It is ideal for first-time credit card users or those who prefer simplicity and no cost of ownership. Avoid it if you want higher base rewards or lounge access.
Opt for the Tata Neu Plus HDFC Credit Cardⓘ if you are a regular online shopper, grocery buyer, or UPI payer who can meet the Rs 8,333 monthly spend threshold to waive the fees. It is also the better choice if you want access to domestic lounges, provided you spend Rs 50,000 quarterly. Avoid this card if you do not meet the fee waiver spend or do not value lounge benefits.
In a decisive call, the Tata Neu Plus HDFC Credit Cardⓘ is best for active spenders who can leverage category rewards and lounge access. The HSBC Visa Platinum Credit Cardⓘ suits those who want a no-fee, dining-focused card without fuss.
What to Check Before You Apply
- Confirm if your spending pattern aligns with the category rewards to maximize returns.
- Understand the value of reward points and whether redemption options suit your needs.
- Carefully assess the fee waiver criteria and whether you can realistically meet the spend thresholds.
- Note that both cards have a 3.5% forex markup, so foreign spend is expensive.
- Check the lounge access gates on the Tata Neu Plus HDFC Credit Cardⓘ to ensure you qualify for free entries.

Comments
No comments yet
Be the first to share your experience with this card.