Quick Verdict
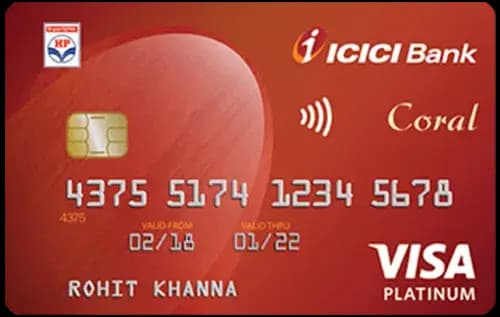
- For everyday fuel and shopping spend, the ICICI Bank HPCL Coral Credit Cardⓘ wins with a strong 5% rewards rate on fuel.
- For travel spends and UPI transactions, the HDFC Bank Rupay IRCTC Credit Cardⓘ offers better category bonuses, especially 5% on travel and 1% on UPI.
- The HDFC Rupay IRCTC card is cheaper to hold with no annual fee, while the ICICI HPCL Coral charges Rs 199 annually but offers fee waiver beyond Rs 1.50 lakh annual spend.
- Choose ICICI HPCL Coralⓘ if you prioritize fuel rewards and occasional domestic lounge access; pick HDFC Rupay IRCTCⓘ if you want a no-fee card focused on travel and UPI payments.
Side by Side
| Detail | ICICI Bank HPCL Coral Credit Cardⓘ | HDFC Bank Rupay IRCTC Credit Cardⓘ |
|---|---|---|
| Annual fee | Rs 199 | Nil (lifetime free) |
| Joining fee | Rs 199 | Rs 500 |
| Fee waiver on spend | Rs 1.50 lakh | Rs 1.50 lakh |
| Reward rate | 0.5% base; 5% fuel | 0.5% base; 5% travel; 1% UPI |
| Reward type | points | points |
| Domestic lounge | 4 per year | 8 per year |
| International lounge | None | None |
| Forex markup | 3.5% | 3.5% |
| Best suited for | fuel, first-card, shopping | travel, upi-rupay, first-card |
Rewards Compared
Both cards offer a base reward rate of 0.5%, which translates to Rs 50 back on every Rs 10,000 spent. This baseline is identical, making the category-specific rates the decisive factor. The ICICI Bank HPCL Coral Credit Cardⓘ stands out in the fuel category, rewarding 5% back, or Rs 500 on Rs 10,000 spent on fuel purchases. This is significant for those who spend heavily on petrol or diesel. Other categories follow the base 0.5% rate, making the Coral card particularly attractive for fuel-centric spenders.
On the other hand, the HDFC Bank Rupay IRCTC Credit Cardⓘ brings 5% rewards on travel-related expenses, also Rs 500 per Rs 10,000 spent, and 1% on UPI payments, or Rs 100 on Rs 10,000 spent. This card’s tailored rewards are suited to users who frequently book travel or use UPI transactions, adding value beyond the base rate. Both cards use a points system for rewards, but the category-specific returns differ to cater to distinct spending habits.
Fees Compared
The ICICI Bank HPCL Coral Credit Cardⓘ has a modest joining fee and annual fee of Rs 199 each. Both fees are waived if you spend Rs 1.50 lakh annually, which breaks down to about Rs 12,500 per month. The card’s break-even on base reward rate alone is at Rs 39,800 spend, after which the rewards surpass the cost of holding the card. This makes it attractive for moderate to heavy spenders who can meet the waiver threshold.
Conversely, the HDFC Bank Rupay IRCTC Credit Cardⓘ charges a higher joining fee of Rs 500 but has no annual fee thereafter, making it effectively lifetime free. It shares the same fee waiver threshold of Rs 1.50 lakh annual spend, which is relevant only if the customer seeks to avoid the joining fee cost in the first year. The no annual fee structure makes the HDFC Rupay IRCTC card a low-maintenance option, especially for users wary of recurring fees.
Which One Should You Pick
Select the ICICI Bank HPCL Coral Credit Cardⓘ if you are a driver or commuter who regularly spends on fuel and wants a card that rewards this category handsomely. Its fuel-linked 5% rewards and moderate fees with waiver options are compelling for first-time cardholders who value simple, category-focused benefits. Additionally, its four free domestic lounge accesses per year are a nice perk for occasional travellers.
The HDFC Bank Rupay IRCTC Credit Cardⓘ is best suited for travellers who book regularly on travel platforms and use UPI payments frequently. Its 5% travel rewards and 1% on UPI spend, combined with eight domestic lounge visits annually, make it a versatile no-annual-fee card. This card also appeals to those who want a lifetime free credit card without worrying about annual fees.
In conclusion, fuel spenders and first-time card users should lean towards the ICICI HPCL Coralⓘ, while frequent travellers and digital payment enthusiasts should pick the HDFC Rupay IRCTCⓘ. Those who do not spend heavily on fuel or travel might skip both as their rewards are category-specific.
What to Check Before You Apply
- Confirm the Rs 75,000 quarterly spend gate for domestic lounge access to avoid surprises.
- Understand the actual redemption value of points since both cards use points but with differing category returns.
- Calculate the monthly spend needed for fee waiver (Rs 12,500) and assess if you can meet it comfortably.
- Remember the 3.5% forex markup applies on foreign currency transactions, making these cards less ideal for frequent international spends.
- Check if your preferred airports have lounges that accept these cards, especially the ICICI Coral’s limited domestic lounge entries.

Comments
No comments yet
Be the first to share your experience with this card.