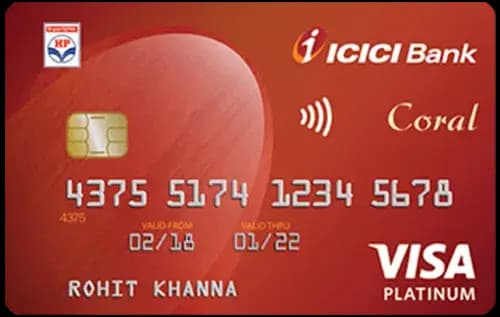
Quick Verdict
- The IDFC HPCL First Power Plus Credit Card ⓘ wins for everyday spend with a higher base reward rate and more category bonuses.
- For travel or lounges, both cards offer 4 domestic lounge visits per year, but the IDFC card has a lower spend gate for lounge access, making it slightly better for lounge users.
- The ICICI Bank HPCL Coral Credit Card ⓘ is cheaper to hold with a lower joining and annual fee of Rs 199 compared to Rs 499 on the IDFC card.
- Choose the ICICI card if you want a low-fee option focused on fuel and shopping as a first card. Pick the IDFC card if you spend across fuel, grocery, and utilities and want better reward rates and easier lounge access.
Side by Side
| Detail | ICICI Bank HPCL Coral Credit Card ⓘ | IDFC HPCL First Power Plus Credit Card ⓘ |
|---|---|---|
| Annual fee | Rs 199 | Rs 499 |
| Joining fee | Rs 199 | Rs 499 |
| Fee waiver on spend | Rs 1.50 lakh | Rs 1.50 lakh |
| Reward rate | 0.5% base, 5% fuel category | 0.75% base, 6.5% fuel, 5% grocery, 5% utilities |
| Reward type | points | points |
| Domestic lounge | 4 per year | 4 per year |
| International lounge | None | None |
| Lounge spend gate | Rs 75,000 quarterly | Rs 20,000 monthly |
| Forex markup | 3.5% | 3.5% |
| Best suited for | fuel, first-card, shopping | fuel, upi-rupay, grocery, lounge |
Rewards Compared
Spending Rs 10,000 on the ICICI Bank HPCL Coral Credit Card ⓘ yields Rs 50 at the base rate and Rs 500 in the fuel category, reflecting a strong 5% return on fuel spends. This card is tailored for fuel and shopping, making it attractive for those focused on these categories but offers only a modest 0.5% base rate on other spends.
On the other hand, the IDFC HPCL First Power Plus Credit Card ⓘ rewards Rs 75 at the base rate per Rs 10,000 spent, a 0.75% return, which is 50% higher than the ICICI card’s base rate. It further boosts rewards to Rs 650 on fuel spends (6.5%), and Rs 500 on grocery and utilities, matching the ICICI card’s fuel returns but extending similar benefits to more categories. This makes the IDFC card more versatile for everyday spending beyond just fuel.
Fees Compared
The ICICI Bank HPCL Coral Credit Card ⓘ charges a joining and annual fee of Rs 199 each, which can be waived by spending Rs 1.50 lakh annually, translating to about Rs 12,500 per month. The IDFC HPCL First Power Plus Credit Card ⓘ has higher fees at Rs 499 for both joining and annual fees, with the same waiver threshold of Rs 1.50 lakh per year or Rs 12,500 monthly.
To justify the Rs 300 extra annual fee on the IDFC card, a cardholder would need to spend approximately Rs 1,20,000 more annually to cover the reward rate gap. For those not spending this much more, the ICICI card is the more economical choice.
Which One Should You Pick
Choose the ICICI Bank HPCL Coral Credit Card ⓘ if you want a low-cost card focused on fuel and shopping rewards with a modest base rate. It is ideal for first-time cardholders or those with moderate spending who want to keep fees low while still enjoying decent fuel category rewards. Skip this card if you want higher returns on a broader range of everyday categories or easier lounge access.
Opt for the IDFC HPCL First Power Plus Credit Card ⓘ if you spend regularly on fuel, grocery, and utilities and want a higher base reward rate. Its more accessible lounge access with a lower Rs 20,000 monthly spend gate adds value for frequent travelers. However, consider the higher fees and ensure your spending justifies them. Avoid this card if your spending is low or very focused on fuel only, as the fee premium may not pay off.
Overall, the IDFC HPCL First Power Plus Credit Card ⓘ suits those seeking broader rewards and lounge benefits willing to pay higher fees, while the ICICI Bank HPCL Coral Credit Card ⓘ is better for fee-conscious users focused on fuel and shopping.
What to Check Before You Apply
- Confirm the quarterly Rs 75,000 spend gate on the ICICI card for domestic lounge access versus the Rs 20,000 monthly gate on the IDFC card.
- Review redemption values carefully since both cards use points, and the effective value depends on how you redeem.
- Calculate if your monthly spend of Rs 12,500 or Rs 1.50 lakh annually realistically meets the fee waiver to avoid paying fees unnecessarily.
- Both cards have a 3.5% forex markup, so consider alternatives if you travel abroad often.

Comments
No comments yet
Be the first to share your experience with this card.