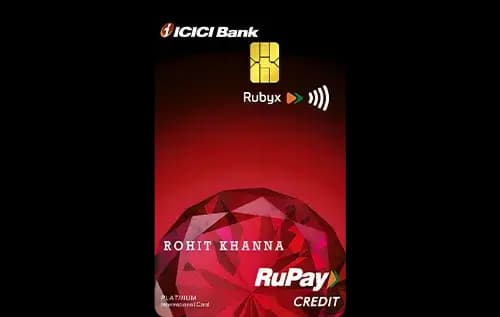
Quick Verdict
- The Eazydiner Indusind Bank Credit Cardⓘ wins for everyday spend, with a higher base reward rate and exceptional dining rewards.
- The ICICI Bank Rubyx Credit Cardⓘ is better for travel and lounge access, offering more domestic and international lounge visits plus premium travel benefits.
- The Rubyx card is cheaper to hold if you can meet its higher waiver spend, but the Eazydiner has a lower waiver threshold making it more accessible.
- Choose the Rubyx if you prioritise travel perks and premium services; pick the Eazydiner for dining rewards and a lower spend requirement for fee waiver.
Side by Side
| Detail | ICICI Bank Rubyx Credit Cardⓘ | Eazydiner Indusind Bank Credit Cardⓘ |
|---|---|---|
| Annual fee | Rs 2,000 | Rs 2,999 |
| Joining fee | Rs 3,000 | Rs 2,999 |
| Fee waiver on spend | Rs 5.00 lakh | Rs 2.00 lakh |
| Reward rate | 0.5% base, 1% dining/online | 0.7% base, 10% dining |
| Reward type | points | points |
| Domestic lounge | 8 per year | 4 per year |
| International lounge | 2 per year | None |
| Forex markup | 3.5% | 3.5% |
| Best suited for | travel, rewards, lounge, shopping | dining, rewards, lounge, travel |
Rewards Compared
On a Rs 10,000 spend, the ICICI Bank Rubyx Credit Cardⓘ offers Rs 50 back at the base rate, increasing to Rs 100 if spent on dining or online categories. This makes it a modest earner for most spends, with a focus on reward points that can be redeemed later. Its category boost for dining and online is double the base but still low compared to its competitor.
The Eazydiner Indusind Bank Credit Cardⓘ returns Rs 70 at base, rising significantly to Rs 1,000 on dining alone, reflecting its strong emphasis on dining rewards. This 10% effective return on dining makes it extremely lucrative for frequent restaurant-goers and lifestyle spenders. The base rate advantage also means more consistent earnings on everyday expenses, providing better overall value for a broader range of spending.
Fees Compared
The Rubyx card charges Rs 3,000 joining and Rs 2,000 annual fees, with a waiver on spending Rs 5.00 lakh annually (Rs 41,667 monthly). This higher waiver threshold means only heavy spenders avoid fees. The base reward rate covers the fee at about Rs 4,00,000 spent annually, slightly lower than the Eazydiner.
The Eazydiner card has a Rs 2,999 joining and Rs 2,999 annual fee, with a much lower waiver spend threshold of Rs 2.00 lakh annually (Rs 16,667 monthly), making fee waiver easier for moderate spenders. Its base rate covers the fee only after about Rs 4,28,429 annual spend. Despite a Rs 999 higher annual fee, the Eazydiner’s lower spend requirement to waive fees may appeal to mid-level spenders.
The head-to-head break-even excessive spend needed to justify the Eazydiner’s higher annual fee due to its better rewards is about Rs 4,99,500, indicating only very high spenders will benefit from that gap.
Which One Should You Pick
Choose the ICICI Bank Rubyx Credit Cardⓘ if you are a premium traveller who values lounge access, travel vouchers, and concierge services. Its higher domestic and international lounge visits plus golf access and air accident insurance make it suited for those who want a luxury travel experience. This card is less ideal if you do not spend enough to waive the fee or if dining rewards are your priority.
The Eazydiner Indusind Bank Credit Cardⓘ suits heavy diners and lifestyle spenders who want maximum returns on dining and everyday spend with a lower barrier to waive fees. Its strong dining rewards and complimentary EazyDiner Prime membership add significant value for food lovers. Avoid this card if you travel frequently and require international lounge access or premium travel perks.
Overall, pick the Rubyx for travel and premium benefits, and the Eazydiner for dining rewards and a lower spend threshold. Those who do not fit either profile should explore other options.
What to Check Before You Apply
- Verify the quarterly Rs 75,000 spend gate to access domestic lounges on Rubyx; it may restrict usage.
- Check redemption options and point expiry for both cards to ensure rewards suit your preferences.
- Confirm how monthly spend is tracked and calculated for fee waiver eligibility to avoid surprises.
- Beware of the 3.5% forex markup if you spend frequently abroad; it impacts overseas transaction costs.
- Check the list of lounges accessible to avoid disappointment due to limited or inconvenient locations.

Comments
No comments yet
Be the first to share your experience with this card.