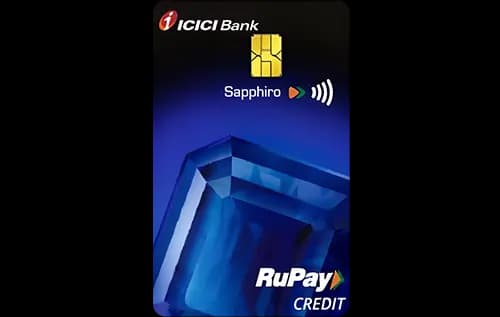
Quick Verdict
- For everyday spend, the Ashva Credit Cardⓘ offers a higher base reward rate of 1.25%, making it the better choice for general purchases.
- When it comes to travel and lounge benefits, both cards provide similar access with 8 domestic and 4 international lounge visits per year, but the Ashva card’s premium benefits and lower forex markup give it an edge for frequent travelers.
- The Ashva Credit Card has a lower joining fee and annual fee compared to the ICICI Bank Sapphiro Credit Cardⓘ, making it cheaper to hold.
- Choose the ICICI Bank Sapphiro Credit Cardⓘ if you prioritize exclusive travel and shopping vouchers and are comfortable with a higher spend to waive fees. Opt for the Ashva Credit Cardⓘ if you want better rewards on dining and travel, lower fees, and premium perks like hotel stays and concierge service.
Side by Side
| Detail | ICICI Bank Sapphiro Credit Cardⓘ | Ashva Credit Cardⓘ |
|---|---|---|
| Annual fee | Rs 3,500 | Rs 2,999 |
| Joining fee | Rs 6,500 | Rs 2,999 |
| Fee waiver on spend | Rs 6.00 lakh | Not recorded |
| Reward rate | 1% base, 2% on online, dining, travel | 1.25% base, 2.5% on dining, travel |
| Reward type | Points | Points |
| Domestic lounge | 8 per year | 8 per year |
| International lounge | 4 per year | 4 per year |
| Forex markup | 3.5% | 1.5% |
| Best suited for | Travel, lounge, rewards, shopping | Premium, travel, lounge, rewards, shopping |
| Golf access | Yes | Yes |
| Concierge | No | Yes |
Rewards Compared
Spending Rs 10,000 on the ICICI Bank Sapphiro Credit Cardⓘ earns Rs 100 back at the base rate of 1%. For categories like online shopping, dining, and travel, the card doubles the reward rate to 2%, resulting in Rs 200 back on Rs 10,000 spent. This makes it attractive for users who spend heavily in these categories. The welcome benefit includes travel and shopping vouchers worth more than Rs 9,500, adding value for new cardholders.
The Ashva Credit Cardⓘ outperforms on rewards with a base rate of 1.25%, yielding Rs 125 back on Rs 10,000 spent. Its category rates are even higher at 2.5% for dining and travel, giving Rs 250 back on Rs 10,000 in these segments. This makes it a stronger choice for premium spenders focusing on dining and travel. Additionally, the card offers up to 7,500 reward points as a welcome benefit, complementing its higher ongoing rewards.
Fees Compared
The ICICI Bank Sapphiro Credit Cardⓘ charges a joining fee of Rs 6,500 and an annual fee of Rs 3,500. The annual fee can be waived if you spend Rs 6.00 lakh annually, which translates to Rs 50,000 per month. The break-even spend to cover the annual fee at the base reward rate is approximately Rs 3.50 lakh. This means you need to spend significantly to justify the fees purely from rewards.
The Ashva Credit Cardⓘ has a lower joining fee and annual fee of Rs 2,999 each. There is no specified fee waiver threshold, so the fees are generally payable. However, its higher base reward rate means the break-even spend to cover the annual fee is about Rs 2.40 lakh, which is lower than the Sapphiro card. This makes the Ashva card more cost-effective for moderate to high spenders.
Which One Should You Pick
Choose the ICICI Bank Sapphiro Credit Cardⓘ if you are a frequent traveler who values exclusive travel and shopping vouchers and can meet the high spend requirement to waive the annual fee. It suits those who want balanced rewards across online, dining, and travel categories along with golf access and decent lounge benefits. However, skip this card if you do not spend enough to cover the fees or want lower forex charges.
The Ashva Credit Cardⓘ is ideal for premium users who want higher rewards on dining and travel, lower fees, and additional perks like concierge service and luxury hotel benefits. Its lower forex markup makes it better for international spenders. Avoid this card if you do not value premium benefits or if you prefer a card with a fee waiver on spend.
Overall, the Ashva Credit Cardⓘ offers better rewards and value for most users, especially those who travel internationally and dine out often. The ICICI Bank Sapphiro Credit Cardⓘ is a solid choice for heavy spenders focused on travel and shopping vouchers.
What to Check Before You Apply
- Confirm if the fee waiver on the ICICI Bank Sapphiro Credit Cardⓘ is achievable based on your monthly spend habits.
- Understand the redemption process and value of points for both cards to ensure rewards translate into real savings.
- Be aware of the forex markup differences: 3.5% on Sapphiro versus 1.5% on Ashva, which impacts foreign currency transactions.
- Check the lounge access locations and whether the lounges match your travel routes to maximize the benefit.

Comments
No comments yet
Be the first to share your experience with this card.