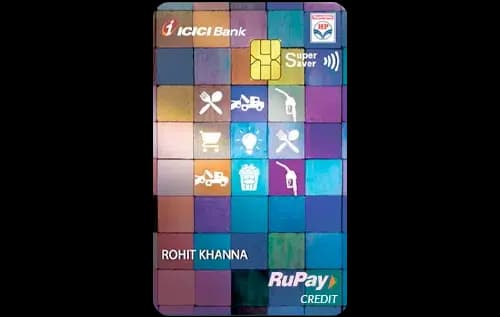
Quick Verdict
- The ICICI HPCL Super Saver Credit Cardⓘ offers a higher base reward rate, making it better for everyday spend, especially in fuel, grocery, and utilities categories.
- The IndusInd Legend Credit Cardⓘ provides more domestic lounge visits per year and is lifetime free, giving it an edge for lounge access and cost-conscious users.
- The ICICI card charges a combined joining and annual fee of Rs 1,000 with waiver at Rs 1.5 lakh annual spend, while the IndusInd Legend card is free forever.
- Pick the ICICI HPCL Super Saverⓘ if you spend heavily on fuel, utilities, and groceries and can meet the fee waiver. Choose the IndusInd Legendⓘ if you want a no-fee card with good lounge access and moderate dining rewards.
Side by Side
| Detail | ICICI HPCL Super Saver Credit Cardⓘ | IndusInd Legend Credit Cardⓘ |
|---|---|---|
| Annual fee | Rs 500 | Nil (lifetime free) |
| Joining fee | Rs 500 | Nil (lifetime free) |
| Fee waiver on spend | Rs 1.50 lakh | None |
| Reward rate | 1% base | 0.7% base |
| Reward type | points | points |
| Domestic lounge | 4 per year | 8 per year |
| International lounge | None | None |
| Forex markup | 3.5% | 3.5% |
| Best suited for | fuel, grocery, cashback, shopping, lounge | rewards, lifetime-free, lounge, shopping |
Rewards Compared
Spending Rs 10,000 on the ICICI HPCL Super Saver Credit Cardⓘ earns Rs 100 back at the base reward rate of 1%. However, this card offers a lucrative 5% effective return in fuel, grocery, and utilities categories, which means Rs 500 back on Rs 10,000 spent in these areas. This makes it highly rewarding for everyday essentials and fuel expenses.
In contrast, the IndusInd Legend Credit Cardⓘ provides a lower base reward rate of 0.7%, translating to Rs 70 on Rs 10,000 spent. It has a slightly higher category rate of 1.75% for dining, yielding Rs 175 for Rs 10,000 spent in that category. While it lacks fuel or grocery category boosts, it appeals to users looking for lifetime free membership and moderate dining rewards.
Fees Compared
The ICICI HPCL Super Saver Credit Cardⓘ charges an annual fee of Rs 500 and a joining fee of Rs 500, totaling Rs 1,000 upfront. This fee is waived if you spend Rs 1.5 lakh annually, which breaks down to Rs 12,500 per month. The card’s base reward rate means you need to spend about Rs 50,000 in a year to cover the Rs 500 annual fee purely through rewards at base rates, but the gap over the IndusInd card’s lower base rate requires Rs 1.67 lakh annual spend to justify the extra fee fully.
The IndusInd Legend Credit Cardⓘ is lifetime free with no joining or annual fees, making it attractive for those avoiding fees altogether. However, its lower reward rates mean you earn less on everyday spending compared to the ICICI card when fees are not a concern.
Which One Should You Pick
Choose the ICICI HPCL Super Saver Credit Cardⓘ if you frequently spend on fuel, groceries, and utilities and can meet the Rs 1.5 lakh annual spend threshold to waive the fees. It suits shoppers wanting higher returns in these categories and some domestic lounge access, making the fee worthwhile.
The IndusInd Legend Credit Cardⓘ is ideal for users seeking a fee-free card with decent lounge access and rewards on dining. It is a good fit for those who prefer no annual costs and moderate rewards without the pressure to meet high waiver spends.
Overall, if you prioritize rewards and spend heavily in fuel and groceries, the ICICI HPCL Super Saverⓘ wins despite the fees. If fee avoidance and more lounge visits matter more, the IndusInd Legendⓘ is the better choice. Avoid the ICICI card if you cannot meet the waiver spend, and skip the IndusInd card if you want higher rewards on fuel and utilities.
What to Check Before You Apply
- Confirm if the quarterly Rs 75,000 spend gate for domestic lounges on the ICICI card fits your spending pattern.
- Understand the redemption process and value for points on both cards; points are not direct cashback and may vary.
- Carefully calculate if your monthly spend comfortably exceeds Rs 12,500 to waive fees on the ICICI HPCL Super Saver card.
- Be aware both cards apply a 3.5% forex markup, which is standard but costly when using abroad.
- Check which airports support the domestic lounge access as the number of visits allowed differs significantly.

Comments
No comments yet
Be the first to share your experience with this card.