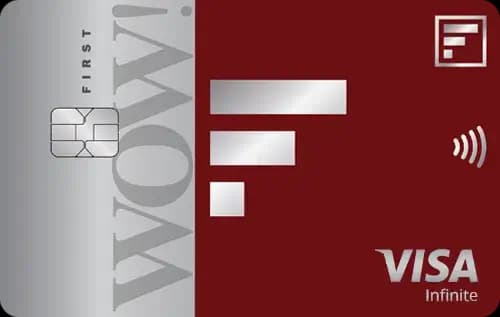
Quick Verdict
- For everyday online spend, the IndusInd Bank Tiger Credit Cardⓘ wins with a higher 2.5% reward rate.
- For forex transactions abroad, the IDFC First Wow Credit Cardⓘ is unbeatable due to zero forex markup.
- Both cards have zero joining and annual fees, making them equally cheap to hold.
- Choose the IDFC First Wow for students, forex spenders, and those wanting a simple lifetime-free card; pick the IndusInd Tiger for better online rewards and domestic lounge access if you meet the spend gates.
Side by Side
| Detail | IDFC First Wow Credit Cardⓘ | IndusInd Bank Tiger Credit Cardⓘ |
|---|---|---|
| Annual fee | Nil (lifetime free) | Nil (lifetime free) |
| Joining fee | Nil (lifetime free) | Nil (lifetime free) |
| Fee waiver on spend | Not recorded | Not recorded |
| Reward rate | 1% base; 1% on online spend | 1% base; 2.5% on online; 1% on UPI |
| Reward type | Points | Points |
| Domestic lounge | None | 4 per year (domestic) |
| International lounge | None | None |
| Forex markup | 0% | 3.5% |
| Best suited for | Lifetime-free, first card, student, forex, dining, shopping | Lifetime-free, UPI-RuPay users, rewards seekers, lounge, travel |
| Lounge spend gate | Rs 40,000 quarterly for domestic lounges | |
| Golf access | Yes |
Rewards Compared
Spending Rs 10,000 on the IDFC First Wow Credit Cardⓘ earns Rs 100 back in points, reflecting its flat 1% reward rate including online spend. It is straightforward with no category boosts. This makes it a consistent, simple rewards card ideal for all-round use but with modest returns.
In contrast, the IndusInd Bank Tiger Credit Cardⓘ earns Rs 250 on Rs 10,000 spent online, thanks to a 2.5% category rate, and Rs 100 on UPI spend at 1%. Its base reward rate is also 1%. This card is clearly designed to reward digital payments and online shopping more generously, appealing to users who maximize category spends.
Fees Compared
Neither card charges any joining or annual fee, both being lifetime free. There is no fee waiver threshold to meet; the cost of holding each card is zero regardless of spend. The IndusInd Tiger does have a spend gate of Rs 40,000 quarterly to unlock domestic lounge access, which users must consider to fully benefit. The IDFC Wow card has no hidden fee conditions.
Which One Should You Pick
Pick the IDFC First Wow Credit Cardⓘ if you want a simple, no-frills lifetime free card that does not charge forex markup, making it ideal for students, first-time cardholders, and international travelers who want to avoid forex fees. It is also good for dining and shopping with moderate rewards.
Choose the IndusInd Bank Tiger Credit Cardⓘ if you shop extensively online or use UPI frequently and want higher rewards. It suits those who value domestic lounge access and golf benefits, provided they can meet the Rs 40,000 quarterly spend for lounges. However, beware of the 3.5% forex markup if you travel abroad.
Skip the IDFC Wow if you want higher rewards on online spends or lounge privileges. Skip the IndusInd Tiger if you travel internationally often and want zero forex fees or if you dislike spending thresholds for lounge access.
What to Check Before You Apply
- Confirm the quarterly Rs 40,000 spend required to access domestic lounges with the IndusInd Tiger.
- Understand that reward rates are category-specific: online for Tiger, flat for IDFC Wow.
- Note the reward redemption value and process to ensure points convert to worthwhile benefits.
- Be aware of forex markup: zero for IDFC Wow, 3.5% for IndusInd Tiger, affecting overseas spend.
- Check which airports the domestic lounges cover for IndusInd Tiger to confirm suitability.

Comments
No comments yet
Be the first to share your experience with this card.