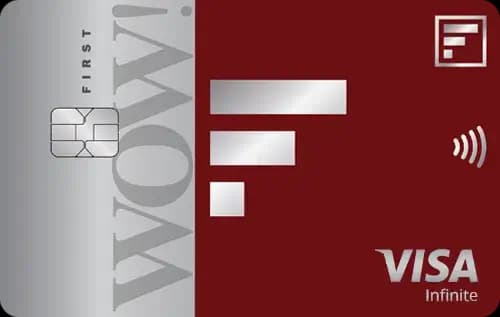
Quick Verdict
- The IDFC First Wow Credit Cardⓘ wins for everyday spending with a higher base reward rate of 1%.
- The RBL Bank ShopRite Credit Cardⓘ excels for grocery and fuel expenses, offering 5% rewards in these categories.
- Both cards are lifetime free with no joining or annual fees, but the ShopRite card requires Rs 2 lakh annual spend for fee waiver benefits.
- Pick the IDFC First Wow if you want a simple, no-fee forex-friendly card with decent rewards. Choose the RBL ShopRite if your spend is heavy on groceries and fuel and you can meet the waiver spend.
Side by Side
| Detail | IDFC First Wow Credit Cardⓘ | RBL Bank ShopRite Credit Cardⓘ |
|---|---|---|
| Annual fee | Nil (lifetime free) | Nil (lifetime free) |
| Joining fee | Nil (lifetime free) | Nil (lifetime free) |
| Fee waiver on spend | Rs 2.00 lakh annually (Rs 16,667 per month) | |
| Reward rate | 1% base, 1% online category | 0.4% base, 5% grocery & fuel categories |
| Reward type | Points | Points |
| Domestic lounge | None | None |
| International lounge | None | None |
| Forex markup | 0% | 3.5% |
| Best suited for | Lifetime-free, first-card, student, forex, dining, shopping | Cashback, grocery, fuel, shopping |
Rewards Compared
The IDFC First Wow Credit Cardⓘ provides a straightforward reward of Rs 100 for every Rs 10,000 spent, reflecting its 1% base reward rate. Its online category also matches this 1% return, making it consistent for general and online spending alike. The card's reward structure is simple and predictable, ideal for users looking for steady returns on all spends without category constraints.
The RBL Bank ShopRite Credit Cardⓘ, by contrast, offers a lower base reward of Rs 40 per Rs 10,000 spent (0.4%). However, it shines in the grocery and fuel categories, delivering Rs 500 back on Rs 10,000 spent (5%). This makes it highly rewarding for users with significant expenses in these areas. Outside these categories, the rewards dip, so the card is best optimized for targeted category spending rather than general use.
Fees Compared
Both cards boast no joining or annual fees, making them attractive for fee-conscious users. The IDFC First Wow Credit Cardⓘ is entirely fee-free for life with no conditions, appealing especially to students and first-time credit card users.
The RBL Bank ShopRite Credit Cardⓘ also has no upfront fees but includes a fee waiver threshold requiring Rs 2 lakh annual spend, which breaks down to Rs 16,667 monthly. While the card is technically free, users who fall short of this spend may face fees or reduced benefits, making it more suitable for high-spending households focused on grocery and fuel.
Which One Should You Pick
Choose the IDFC First Wow Credit Cardⓘ if you want a no-hassle, no-fee credit card with a solid 1% rewards rate on all spending and zero forex markup. It is well-suited for students, first-card holders, and travelers who make forex transactions without incurring extra charges. The lack of lounge access may not matter for casual spenders focused on everyday benefits.
Opt for the RBL Bank ShopRite Credit Cardⓘ if your spending is concentrated in groceries and fuel, where you can maximize the attractive 5% returns. It is a good fit for families and working professionals aiming for cashback on essential purchases. However, be prepared to meet the Rs 2 lakh annual spend requirement to truly benefit from the card’s fee waiver and rewards.
In conclusion, the IDFC First Wow Credit Cardⓘ is the better all-rounder with no fees and zero forex markup, ideal for moderate spenders and forex users. The RBL ShopRite Credit Cardⓘ is a niche winner for heavy grocery and fuel spenders who can meet the waiver threshold. Skip the IDFC card if you want category-focused rewards, and skip the RBL card if you do not meet the high spend requirement or want forex-friendly usage.
What to Check Before You Apply
- Confirm any caps or limits on the 5% grocery and fuel rewards on the RBL ShopRite card.
- Understand the redemption value and ease of converting points into usable rewards for both cards.
- Calculate if your monthly spends comfortably meet the Rs 16,667 waiver threshold on the RBL ShopRite card.
- Consider the forex markup: zero on IDFC First Wow, but a costly 3.5% on RBL ShopRite, impacting travel expenses.
- Check which domestic and international lounges are accessible, as neither card offers complimentary lounge access.

Comments
No comments yet
Be the first to share your experience with this card.