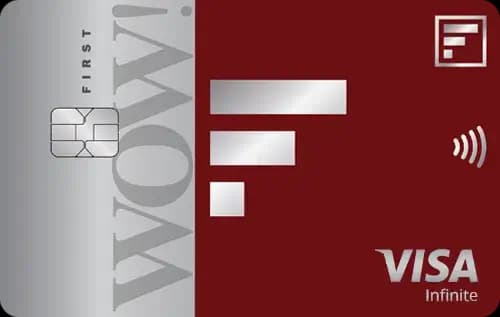
Quick Verdict
- For everyday spend, the Yes Bank Rupay Credit Cardⓘ wins with higher rewards on groceries and dining.
- For travel or lounge access, Yes Bank Rupayⓘ offers four domestic lounge visits annually, while IDFC First Wowⓘ offers none.
- Both cards are lifetime free, but IDFC First Wowⓘ has zero forex markup, making it cheaper for foreign transactions.
- Choose IDFC First Wowⓘ if you want a no-annual-fee card with zero forex fees and decent online rewards. Pick Yes Bank Rupayⓘ if you prioritize higher rewards in groceries and dining plus domestic lounge access.
Side by Side
| Detail | IDFC First Wow Credit Cardⓘ | Yes Bank Rupay Credit Cardⓘ |
|---|---|---|
| Annual fee | Nil (lifetime free) | Nil (lifetime free) |
| Joining fee | Nil (lifetime free) | Nil (lifetime free) |
| Fee waiver on spend | Rs 75,000 annually (Rs 6,250 monthly) | |
| Reward rate | 1% base, 1% online | 1% base, 3% grocery, 3% dining, 1% UPI |
| Reward type | Points | Points |
| Domestic lounge | None | 4 per year (Rs 50,000 quarterly spend gate) |
| International lounge | None | None |
| Forex markup | 0% | 3.5% |
| Best suited for | Lifetime-free, first-card, student, forex, dining, shopping | UPI-Rupay, rewards, grocery, first-card, shopping |
Rewards Compared
The IDFC First Wow Credit Cardⓘ offers a straightforward 1% reward rate on all spends, including an additional 1% on online transactions, effectively earning you Rs 100 on every Rs 10,000 spent generally and the same Rs 100 on online spends. This consistent earning aligns well with users who prefer simple reward structures and want to maximize returns on online shopping and dining without worrying about categories.
The Yes Bank Rupay Credit Cardⓘ has a base reward rate of 1%, matching IDFC Wow for general spends at Rs 100 per Rs 10,000. However, it excels in key categories like groceries and dining, where it offers a 3% return, earning Rs 300 on Rs 10,000 spent. For UPI transactions, it offers the base 1% rate. These elevated category rates make it ideal for cardholders who spend heavily on groceries and dining and want to maximize rewards in those areas.
Fees Compared
Both cards carry no joining or annual fees, making them attractive for lifetime free usage. The Yes Bank Rupay Credit Cardⓘ does have a fee waiver condition based on Rs 75,000 annual spending, or approximately Rs 6,250 monthly. Despite this, the annual fee is nil, so it is effectively free regardless of spend but the lounge access is gated by quarterly spend of Rs 50,000 for domestic lounges. The IDFC First Wow Credit Cardⓘ has no fee waiver threshold, as it is free with no conditions. For forex transactions, IDFC Wow is clearly cheaper with zero markup, while Yes Bank Rupay charges a 3.5% forex fee, adding Rs 3,500 on Rs 1,00,000 foreign spend.
Which One Should You Pick
Choose the IDFC First Wow Credit Cardⓘ if you seek a truly lifetime free card with no forex markup, making it excellent for students, frequent online shoppers, and those who travel abroad but want to avoid forex fees. Its simple 1% return on spend is consistent and easy to understand, especially for first-time card users.
Opt for the Yes Bank Rupay Credit Cardⓘ if you want higher category rewards on groceries and dining, plus domestic lounge access for Rs 50,000 quarterly spenders. It suits shoppers who prefer rewards in everyday essential categories and also want occasional lounge visits but are okay with paying forex markup on international spends.
Skip IDFC Wowⓘ if you rely heavily on grocery and dining spends and want lounge access. Skip Yes Bank Rupayⓘ if you want zero forex markup and no fuss with spend-based lounge access gates.
What to Check Before You Apply
- Confirm if the 3.5% forex markup on Yes Bank Rupayⓘ applies to all foreign transactions including online payments.
- Verify the exact redemption value of points as it can vary and impact effective rewards.
- Understand the fee waiver math carefully for Yes Bank Rupayⓘ, especially the Rs 50,000 quarterly lounge spend gate.
- Check which domestic lounges are accessible with Yes Bank Rupayⓘ and how easy it is to avail the four free visits annually.

Comments
No comments yet
Be the first to share your experience with this card.