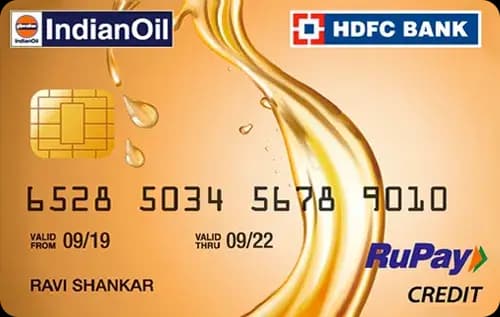
Quick Verdict
- The Indianoil HDFC Bank Credit Cardⓘ wins for everyday spend, especially if you spend on fuel or groceries, thanks to its higher base and category reward rates.
- The Shoppers Stop HDFC Bank Credit Cardⓘ edges out for online shopping due to its superior category reward rate and welcome benefits.
- The Shoppers Stop card is cheaper to hold with a lower joining and annual fee and no fee waiver requirement.
- Pick the Indianoil card if you frequently spend on fuel or groceries and can meet the Rs 50,000 annual spend waiver. Choose the Shoppers Stop card if you want a lifetime-free card with added shopping perks and lower fees.
Side by Side
| Detail | Indianoil HDFC Bank Credit Cardⓘ | Shoppers Stop HDFC Bank Credit Cardⓘ |
|---|---|---|
| Annual fee | Rs 500 | Rs 299 |
| Joining fee | Rs 500 | Rs 299 |
| Fee waiver on spend | Rs 50,000 | (No waiver specified) |
| Reward rate | 1% base | 0.5% base |
| Reward type | points | points |
| Domestic lounge | None | None |
| International lounge | None | None |
| Forex markup | 3.5% | 3.5% |
| Best suited for | fuel, first-card, upi-rupay | shopping, lifetime-free |
Rewards Compared
On a spend of Rs 10,000, the Indianoil HDFC Bank Credit Cardⓘ returns Rs 100 at its base rate of 1 percent. However, in its key categories, fuel and grocery, it offers a rewarding 5 percent rate, which translates to Rs 500 back for every Rs 10,000 spent. This makes it highly attractive for users who channel a significant portion of their expenses into these categories.
The Shoppers Stop HDFC Bank Credit Cardⓘ offers a lower base reward rate of 0.5 percent, resulting in Rs 50 back per Rs 10,000 spent generally. Yet, it boasts a strong 6 percent return on online spends, equating to Rs 600 for every Rs 10,000 spent online, which is higher than Indianoil's category returns in its focus areas. This makes the Shoppers Stop card more rewarding for online shopping enthusiasts despite its lower base rate.
Fees Compared
The Indianoil card charges a joining fee and annual fee of Rs 500 each, with a fee waiver if you spend Rs 50,000 annually, which breaks down to Rs 4,167 monthly. This means you need to maintain moderate spending to avoid fees. The Shoppers Stop card demands a lower joining and annual fee of Rs 299 each, with no fee waiver condition specified, effectively making it cheaper to hold if your spend is inconsistent or low.
In head-to-head terms, the Indianoil card’s higher annual fee means you must spend Rs 40,200 more annually to justify the better base reward rate. If you spend less than about Rs 59,800 annually, the Shoppers Stop card’s lower fees and decent category rewards make it the more economical choice.
Which One Should You Pick
Choose the Indianoil HDFC Bank Credit Cardⓘ if you are a regular spender on fuel or groceries and can comfortably meet the Rs 50,000 annual spend to waive fees. Its superior category rewards and decent base rate will maximize your returns on everyday essential spends. It is also suitable as a first card or if you prefer a Rupay and UPI-linked credit option.
The Shoppers Stop HDFC Bank Credit Cardⓘ is ideal for shoppers who prefer online spending and want a card with a lower annual fee and no fee waiver hassle. Its welcome benefit of a Rs 500 voucher and complimentary Silver Edge membership adds value for frequent Shoppers Stop customers. It suits those wanting a lifetime-free card with focused shopping rewards.
If you do not spend significantly on fuel or groceries, skip the Indianoil card to avoid paying fees without adequate rewards. Conversely, if you are not a regular online shopper or prefer higher base rewards across categories, the Shoppers Stop card may not be the best fit.
What to Check Before You Apply
- Confirm if your spending pattern matches the card’s category rewards to maximize value and avoid paying fees unnecessarily.
- Check any caps on reward points or maximum cashback in fuel, grocery, or online categories to avoid surprises.
- Understand the fee waiver mechanics: Indianoil requires Rs 50,000 annual spend, so calculate if you can realistically meet this.
- Be aware of the 3.5 percent forex markup if you plan to use the card abroad; neither card offers lounge access to offset this cost.
- Verify the availability and convenience of lounges since neither card provides domestic or international lounge access.

Comments
No comments yet
Be the first to share your experience with this card.