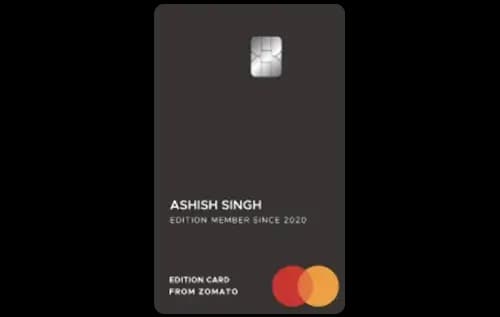
Quick Verdict
- This card is best for diners and occasional travelers who want simple cashback without fuss.
- The strongest reason to hold it is the straightforward 1% cashback on all spends plus a complimentary Zomato Pro membership.
- The biggest drawback is the absence of lounge access and a relatively low forex markup benefit, which limits its appeal to frequent international travelers.
- The Rs 2,000 annual fee is justifiable only if you spend around Rs 2,00,000 annually to break even on cashback.
Card at a Glance
| Detail | Value |
|---|---|
| Joining fee | Rs 2,000 |
| Annual fee | Rs 2,000 |
| Reward rate | 1% cashback |
| Reward type | Cashback |
| Best suited for | Dining, Lounge |
| Domestic lounge | None |
| International lounge | None |
| Forex markup | 1.5% |
| Welcome benefit | Complimentary Zomato Pro membership |
Rewards and How They Add Up
The RBL Bank Edition Credit Card ⓘ offers a flat 1% cashback on all spends. This means for every Rs 10,000 you spend, you earn Rs 100 back. There are no category-specific bonuses beyond this base rate, so the value proposition is simple and consistent.
At Rs 10,000 spent, the return is Rs 100. To cover the Rs 2,000 annual fee purely through cashback, you would need to spend about Rs 2,00,000 in a year. Since there are no additional multipliers or caps mentioned, heavy spenders might find this straightforward cashback more predictable, but light spenders will find it hard to justify the fee.
Fees and What They Demand
The card charges a joining fee of Rs 2,000 and an annual fee of Rs 2,000. There is no mention of any fee waiver on minimum spends, so the fee is unavoidable each year.
To realistically justify the Rs 2,000 annual fee, cardholders need to spend at least Rs 2,00,000 annually so that their 1% cashback offsets the fee. For those spending less, the fee becomes a cost rather than an investment, reducing the card’s attractiveness significantly.
Who Should Hold This Card
This card suits consumers who prioritize simplicity in rewards and enjoy dining, especially with the complimentary Zomato Pro membership enhancing food delivery or dining experiences. If you spend regularly on dining and can comfortably reach the Rs 2,00,000 annual spend threshold, the cashback and benefits can justify the fees. It is also suitable for those who want a no-fuss cashback card without the need to track category bonuses.
However, frequent international travelers or those who value lounge access should look elsewhere. The forex markup of 1.5% is average and higher than some premium cards offering zero markup or lower rates. The lack of any airport lounge benefits domestically or internationally makes this card less valuable for travelers. For such users, cards offering lounge access and stronger travel benefits would be more appropriate.
What to Check Before You Apply
- Verify there is no waiver on the annual fee since none is advertised.
- Confirm that the 1% cashback applies uniformly without caps or category exclusions.
- Understand that the complimentary Zomato Pro membership is a welcome benefit and may have a limited validity.
- Consider the 1.5% forex markup which is standard but higher than premium travel cards, check if you spend heavily abroad.
Bottom Line
The RBL Bank Edition Credit Card ⓘ is a straightforward cashback card best for diners and moderate spenders who can surpass Rs 2,00,000 in annual spending. Its simple rewards and Zomato Pro membership add value, but the lack of lounge access and modest forex benefits make it less suitable for frequent travelers. The Rs 2,000 annual fee is reasonable only if you maximize the cashback potential.

Comments
No comments yet
Be the first to share your experience with this card.