Quick Verdict
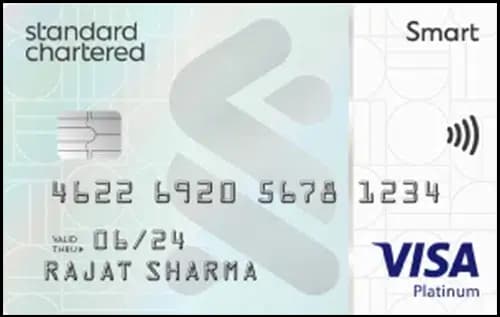
- For everyday spending, the Standard Chartered Smart Credit Cardⓘ offers a higher base cashback rate, making it the better choice.
- For specific categories like fuel and utilities, the Standard Chartered Super Value Titanium Credit Cardⓘ wins with superior category rates.
- The Smart Credit Card is cheaper to hold if you meet the higher waiver spend of Rs 1.20 lakh annually; otherwise, the Super Value Titanium card’s lower fee waiver threshold of Rs 60,000 may be easier to achieve.
- Choose the Smart Credit Cardⓘ if you want a straightforward cashback card with better online rewards, and pick the Super Value Titaniumⓘ if your expenses are heavy on fuel or utilities.
Side by Side
| Detail | Standard Chartered Smart Credit Cardⓘ | Standard Chartered Super Value Titanium Credit Cardⓘ |
|---|---|---|
| Annual fee | Rs 499 | Rs 750 |
| Joining fee | Rs 499 | Rs 750 |
| Fee waiver on spend | Rs 1.20 lakh | Rs 60,000 |
| Reward rate | 1% | 0.5% |
| Reward type | cashback | cashback |
| Domestic lounge | None | None |
| International lounge | None | None |
| Forex markup | 3.5% | 3.5% |
| Best suited for | cashback, shopping, first-card | fuel, cashback, shopping |
Rewards Compared
The Standard Chartered Smart Credit Cardⓘ offers a base cashback rate of 1%, translating to Rs 100 cashback on Rs 10,000 spent. It also doubles this rate to 2% for online spending, yielding Rs 200 cashback per Rs 10,000 online spend. This makes it particularly attractive for users who shop frequently online or want a consistent cashback reward on all purchases.
In contrast, the Standard Chartered Super Value Titanium Credit Cardⓘ provides a lower base cashback rate of 0.5%, resulting in Rs 50 cashback on Rs 10,000 general spend. However, it shines in key categories such as fuel and utilities, where it offers 5% cashback, equating to Rs 500 cashback on Rs 10,000 spent in these categories. This card suits users whose spending is concentrated in these specific areas, delivering much higher value compared to the Smart Credit Cardⓘ in those segments.
Fees Compared
The Smart Credit Cardⓘ charges a joining and annual fee of Rs 499 each. These fees can be waived if you spend Rs 1.20 lakh annually, which breaks down to Rs 10,000 per month. If you spend less than Rs 49,900 per year, the cashback earned at the base rate will not cover the fees, making it less cost-effective for low spenders.
The Super Value Titanium Credit Cardⓘ has a higher joining and annual fee of Rs 750 each but requires a much lower annual spend of Rs 60,000 (Rs 5,000 per month) to waive these. Given its lower base cashback rate, you need to spend around Rs 1.50 lakh annually to earn cashback that covers the fees at the base rate. However, the high category rates in fuel and utilities can help offset this for users with targeted spending.
Which One Should You Pick
Choose the Standard Chartered Smart Credit Cardⓘ if you are a frequent online shopper or someone seeking a straightforward cashback card with a lower fee and decent rewards on all spends. It is well suited for first-time cardholders looking for simplicity and value. However, if your monthly spending is below Rs 10,000, this card may not be cost-effective.
Opt for the Standard Chartered Super Value Titanium Credit Cardⓘ if a significant portion of your expenses is on fuel or utility bills, as the 5% cashback in these categories is compelling. The higher fees are manageable if you regularly meet the Rs 60,000 annual spend threshold. Avoid this card if your spending is diversified and does not focus on the fuel or utilities categories.
In conclusion, the Smart Credit Cardⓘ is the better all-rounder for everyday and online spenders, while the Super Value Titaniumⓘ offers superior rewards for category-specific users. Low spenders or those not focused on fuel and utilities should skip the Super Value Titaniumⓘ.
What to Check Before You Apply
- Confirm if the fee waiver category includes your typical spending categories to ensure you can meet the threshold comfortably.
- Check if the cashback redemption process has any minimum limits or expiry periods that could reduce value.
- Calculate your monthly spend carefully to determine if you can realistically waive the annual fee on each card.
- For international travelers, consider the 3.5% forex markup, which is the same for both cards and can add significant costs on foreign spends.
- Neither card offers lounge access, so if airport lounge benefits are important, look elsewhere.

Comments
No comments yet
Be the first to share your experience with this card.