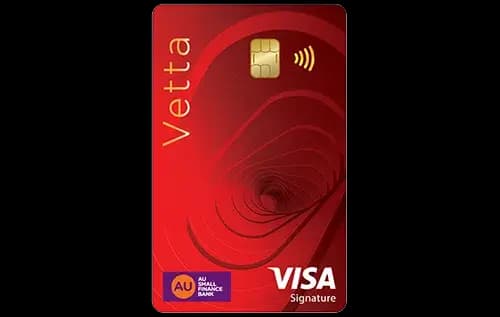
Quick Verdict
- For everyday spend, the Standard Chartered Ultimate Credit Cardⓘ wins with a higher base reward rate of 3.33% compared to 1% on the Vetta Credit Cardⓘ.
- For travel and lounge access, both cards offer similar domestic and international lounge visits, but the Vetta Credit Cardⓘ has a lower forex markup fee, making it slightly better for foreign travel.
- The Vetta Credit Cardⓘ is cheaper to hold with an annual fee of Rs 2,999 versus Rs 5,000 on the Standard Chartered Ultimate Credit Cardⓘ, but requires a higher spend to waive fees.
- Pick the Vetta Credit Cardⓘ if you prioritize premium travel benefits and lower fees with curated offers; choose the Standard Chartered Ultimate Credit Cardⓘ if you want higher rewards on everyday spend and additional perks like golf access and fuel surcharge waivers.
Side by Side
| Detail | Vetta Credit Cardⓘ | Standard Chartered Ultimate Credit Cardⓘ |
|---|---|---|
| Annual fee | Rs 2,999 | Rs 5,000 |
| Joining fee | Rs 2,999 | Rs 5,000 |
| Fee waiver on spend | Rs 5.00 lakh | Not recorded |
| Reward rate | 1% base; 4% online & dining | 3.33% base |
| Reward type | Points | Points |
| Domestic lounge | 8 per year | 8 per year |
| International lounge | 4 per year | 4 per year |
| Forex markup | 1.99% | 2% |
| Best suited for | Premium, rewards, lounge, dining, travel, shopping | Rewards, travel, lounge, premium, shopping |
Rewards Compared
The Vetta Credit Cardⓘ offers a base reward of 1%, which translates to Rs 100 back on Rs 10,000 spent. However, it shines in specific categories like online shopping and dining where the reward rate increases to 4%, yielding Rs 400 on the same spend. This makes it attractive for users who frequently spend in these categories and want to maximize returns there.
In contrast, the Standard Chartered Ultimate Credit Cardⓘ provides a much higher base reward rate of 3.33%, equating to Rs 333 on Rs 10,000 spent across all categories. This straightforward, higher base rate benefits users with diverse spending patterns who want consistent rewards without category restrictions. The lack of specific category boosts means it is simpler but generally more rewarding for everyday purchases.
Fees Compared
The Vetta Credit Cardⓘ charges Rs 2,999 each for joining and annual fees, with a fee waiver threshold at Rs 5 lakh annual spend. This works out to about Rs 41,667 monthly spend to avoid the fee. The break-even spend for the base reward rate to cover the annual fee is around Rs 3 lakh.
The Standard Chartered Ultimate Credit Cardⓘ has a higher joining and annual fee of Rs 5,000 each. The fee waiver condition is not specified, so the user must consider the fee as a fixed cost. However, its higher base reward rate means the break-even spend to cover the fee is approximately Rs 1.5 lakh, significantly lower than Vetta’s.
The extra Rs 2,001 annual fee on the Standard Chartered card requires an additional Rs 85,880 in spend to justify purely on base rate rewards, making it worthwhile only for higher spenders.
Which One Should You Pick
Choose the Vetta Credit Cardⓘ if you are a premium user who values curated travel and dining benefits, lower forex markup fees, and can meet the high spend requirement to waive fees. Its quarterly spend gate of Rs 50,000 for lounge access is manageable for frequent travellers, and the comprehensive protection cover adds peace of mind.
Opt for the Standard Chartered Ultimate Credit Cardⓘ if you want a simple, high base reward rate without worrying about category restrictions. It suits users who spend moderately to high amounts and want perks like golf access, fuel surcharge waiver, and a strong welcome benefit. The lifetime free supplementary cards also appeal to family users.
Skip the Vetta Credit Cardⓘ if you spend less than Rs 3 lakh annually or do not shop much online or dine out. Avoid the Standard Chartered Ultimate Credit Cardⓘ if you cannot justify the higher fee or do not utilize its premium benefits like lounges and golf.
What to Check Before You Apply
- Lounge access caps and quarterly or monthly spend gates can limit free visits; verify your travel frequency matches these.
- Redemption value of points and any restrictions on converting or using them can affect your actual returns.
- Fee waiver spend thresholds can be high; calculate if your monthly and annual spends realistically meet these to avoid fees.
- Forex markup fees differ; consider your foreign travel habits as even small percentage differences add up on large spends.
- Lounge network coverage and gates (Priority Pass vs Visa offers) impact convenience; check if your airports are included.

Comments
No comments yet
Be the first to share your experience with this card.