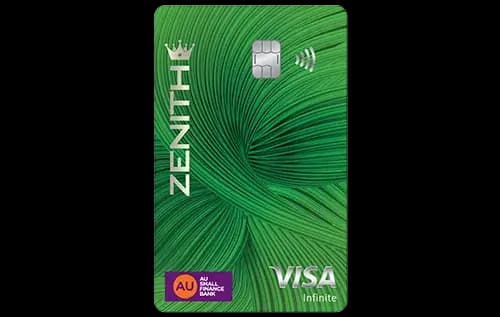
Quick Verdict
- For everyday spend, the ICICI Bank Emeralde Private Metal Credit Cardⓘ wins with a 3% base reward rate versus 1% on the Zenith Credit Cardⓘ.
- For travel and lounge access, the ICICI card offers unlimited domestic and international lounge visits, beating Zenith’s limited 8 domestic and 6 international lounges per year.
- The Zenith Credit Cardⓘ is cheaper to hold with a Rs 7,999 annual fee compared to Rs 12,499 on the ICICI Emeralde Private Metal Credit Cardⓘ.
- Pick Zenith if you want a lower fee, milestone bonuses, and decent lounge access; choose ICICI Emeralde for higher rewards on all spends, unlimited lounges, and premium travel perks.
Side by Side
| Detail | Zenith Credit Cardⓘ | ICICI Bank Emeralde Private Metal Credit Cardⓘ |
|---|---|---|
| Annual fee | Rs 7,999 | Rs 12,499 |
| Joining fee | Rs 7,999 | Rs 12,499 |
| Fee waiver on spend | Not recorded | Not recorded |
| Reward rate | 1% base, 5% dining & travel | 3% base, 3% online, dining & travel |
| Reward type | points | points |
| Domestic lounge | 8 per year | Unlimited |
| International lounge | 6 per year | Unlimited |
| Forex markup | 1.99% | 2% |
| Best suited for | premium, travel, lounge, dining, shopping, rewards | premium, travel, lounge, forex, shopping, rewards |
Rewards Compared
The Zenith Credit Cardⓘ offers a base reward of Rs 100 on Rs 10,000 spent, with elevated returns of Rs 500 on Rs 10,000 spent in dining and travel categories due to its 5% category rate. This makes it attractive for users who focus their spends specifically on dining and travel, leveraging the higher category returns.
In contrast, the ICICI Bank Emeralde Private Metal Credit Cardⓘ delivers a consistent Rs 300 on Rs 10,000 spent across base, online, dining, and travel categories at a 3% rate. This steadier reward rate across multiple categories suits users who prefer a simpler, higher flat return on all spends rather than category-specific bonuses.
Fees Compared
The Zenith Credit Cardⓘ charges Rs 7,999 as both joining and annual fee, while the ICICI Emeralde Private Metal Credit Cardⓘ demands a heftier Rs 12,499 for each. Neither card specifies a fee waiver threshold based on spend, so these fees are fixed costs. The Zenith card requires approximately Rs 7,99,900 in annual spend to cover its fee at base rates, whereas the ICICI card needs about Rs 4,16,633, reflecting its higher reward rate. The Rs 4,500 extra fee on the ICICI card is offset by higher rewards if you spend over Rs 2,25,000 annually.
Which One Should You Pick
Choose the Zenith Credit Cardⓘ if you are a premium user who values category-specific high rewards in dining and travel, prefers a lower annual fee, and appreciates milestone and birthday bonus points. It also suits those who want decent but limited lounge access and lower forex charges.
Opt for the ICICI Bank Emeralde Private Metal Credit Cardⓘ if you are a high spender seeking a higher flat reward rate across all spends, unlimited lounge access both domestic and international, and premium travel perks like golf access and concierge services. This card is better for those who want simplicity in rewards and can justify the higher fee with their spend.
Skip Zenith if you want unlimited lounge access or higher base rewards on all spends. Skip ICICI Emeralde if you are a moderate spender who cannot justify the higher fee or if you focus mainly on dining and travel categories where Zenith’s 5% rate excels.
What to Check Before You Apply
- Confirm the quarterly Rs 20,000 spend gate for domestic lounge access with Zenith Credit Cardⓘ.
- Check the actual redemption value of reward points to ensure you get the stated effective returns.
- Verify if the fee waiver thresholds exist or if fees are non-negotiable annual fixed payments.
- Consider the forex markup differences: 1.99% with Zenith versus 2% with ICICI Emeralde.
- Review which airport lounges are accessible and their locations to match your travel patterns.

Comments
No comments yet
Be the first to share your experience with this card.