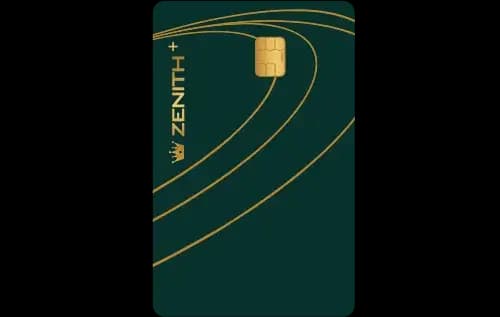
Quick Verdict
- For everyday spend including dining, travel, and online shopping, the Zenith Plus Credit Cardⓘ wins with a higher 4% reward rate in these categories compared to 2% on the ICICI Bank Sapphiro Credit Cardⓘ.
- For travel benefits and lounge access, Zenith Plus offers more international lounge visits and premium services like personalized airport meet and assist, making it the better choice for frequent travelers.
- The ICICI Sapphiro card is cheaper to hold with a lower annual fee and a fee waiver on Rs 6 lakh annual spend, which is easier to achieve than Zenith Plus’s effective break-even spend of about Rs 5 lakh without waiver.
- Pick Zenith Plus if you want premium travel perks and higher category rewards and can justify the higher fees. Choose ICICI Sapphiro for a lower cost card with solid travel rewards and easier fee waiver.
Side by Side
| Detail | Zenith Plus Credit Card ⓘ | ICICI Bank Sapphiro Credit Card ⓘ |
|---|---|---|
| Annual fee | Rs 4,999 | Rs 3,500 |
| Joining fee | Rs 4,999 | Rs 6,500 |
| Fee waiver on spend | None | Rs 6.00 lakh |
| Reward rate | 1% base, 4% dining, travel, online | 1% base, 2% dining, travel, online |
| Reward type | Points | Points |
| Domestic lounge | 8 per year | 8 per year |
| International lounge | 6 per year | 4 per year |
| Forex markup | 1.99% | 3.5% |
| Best suited for | Premium, travel, lounge, rewards, dining, shopping | Travel, lounge, rewards, shopping |
Rewards Compared
Spending Rs 10,000 on the Zenith Plus Credit Cardⓘ earns Rs 100 back at the base rate. However, in key categories such as dining, travel, and online shopping, the effective return quadruples to Rs 400 per Rs 10,000 spent. This makes it highly rewarding for users who spend heavily in these categories, delivering a 4% return which is excellent for premium users who prioritize rewards.
In contrast, the ICICI Bank Sapphiro Credit Cardⓘ also returns Rs 100 at the base rate for every Rs 10,000 spent. Its category rewards are more modest, offering 2% returns or Rs 200 per Rs 10,000 spent in dining, travel, and online categories. While lower than Zenith Plus, this is still a decent rate for a card with a lower annual fee and a fee waiver threshold.
Fees Compared
The Zenith Plus card demands a Rs 4,999 joining fee and an equal annual fee of Rs 4,999, with no fee waiver on spending. To cover the annual fee purely through base rewards, a cardholder would need to spend approximately Rs 4,99,900 annually, which is a high threshold.
ICICI Sapphiro charges a higher joining fee of Rs 6,500 but a lower annual fee of Rs 3,500. It offers a fee waiver if you spend Rs 6 lakh annually, which breaks down to Rs 50,000 per month. This makes the card more accessible for fee waiver compared to Zenith Plus, especially for regular spenders who can maintain this monthly spend.
Which One Should You Pick
The Zenith Plus Credit Cardⓘ is best suited for premium users who frequently spend on dining, travel, and online shopping and want superior lounge access and concierge services. If you value luxury perks like Taj Epicure Membership and personalized airport services and can comfortably spend above Rs 5 lakh annually, this card delivers strong value.
The ICICI Bank Sapphiro Credit Cardⓘ is ideal for travelers and shoppers who want a lower annual fee and the possibility of fee waiver with Rs 6 lakh annual spend. It suits those who want decent rewards and lounge access but are not necessarily looking for ultra-premium benefits.
If you are a low or moderate spender, skip Zenith Plus due to its high fees and spend requirement. If you rarely spend Rs 50,000 monthly, Sapphiro’s fee waiver may also be hard to achieve, so consider other options.
What to Check Before You Apply
- Confirm the caps on category rewards if any, as some cards limit how much you can earn at elevated rates.
- Understand the redemption value of points, since the stated reward rates are effective returns after point valuation.
- Calculate the monthly spend needed for fee waiver carefully to ensure you can realistically meet it.
- Note the forex markup differences: Zenith Plus charges 1.99% while Sapphiro charges 3.5%, which affects foreign spending costs.
- Check which lounges are accessible and at which airports to ensure the lounge benefits align with your travel patterns.

Comments
No comments yet
Be the first to share your experience with this card.