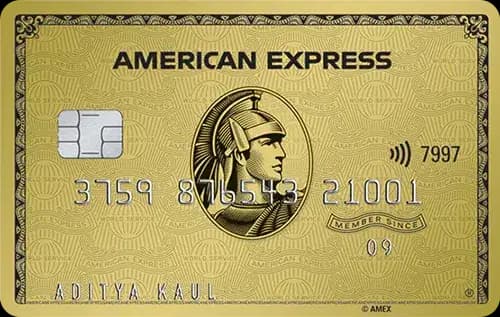
Quick Verdict
- The Mayura Credit Cardⓘ wins for everyday spend and rewards thanks to a higher base reward rate and excellent category multipliers.
- For travel and lounge access, the Mayura Credit Cardⓘ also leads with unlimited domestic lounge access and eight international lounge visits annually.
- The American Express Gold Credit Cardⓘ is cheaper to hold with a lower annual fee and joining fee, but requires nearly double the spend to justify its fee with rewards.
- Choose the Mayura Credit Cardⓘ if you prioritize premium travel perks, forex spending, and higher rewards; pick the Amex Goldⓘ if you want moderate fees and solid dining and shopping discounts.
Side by Side
| Detail | American Express Gold Credit Cardⓘ | Mayura Credit Cardⓘ |
|---|---|---|
| Annual fee | Rs 4,500 | Rs 5,999 |
| Joining fee | Rs 1,000 | Rs 5,999 |
| Fee waiver on spend | Rs 9,00,000 annually | Rs 3,99,933 annually |
| Reward rate | 0.5% base | 1.5% base, 3% dining, travel, online |
| Reward type | points | points |
| Domestic lounge | 8 per year | Unlimited |
| International lounge | None | 8 per year |
| Forex markup | 3.5% | 1.5% |
| Best suited for | rewards, travel, shopping | premium, travel, lounge, rewards, forex, shopping |
Rewards Compared
Spending Rs 10,000 on the American Express Gold Credit Cardⓘ earns you Rs 50 worth of rewards at the base rate of 0.5%. This modest rate is supplemented by benefits such as dining discounts and hotel deals but no category multipliers, so all spends essentially return the same value.
In contrast, the Mayura Credit Cardⓘ offers a much stronger base return of Rs 150 per Rs 10,000 spent, tripling the Amex Gold's baseline. Furthermore, it shines in key categories like dining, travel, and online spends, where the return jumps to Rs 300 per Rs 10,000, doubling even its base rate. This makes the Mayura Cardⓘ far more lucrative for those who spend heavily in these areas.
Fees Compared
The American Express Gold Credit Cardⓘ charges a joining fee of Rs 1,000 and an annual fee of Rs 4,500. To avoid paying the fee outright through reward earnings, you must spend approximately Rs 9,00,000 annually, which is relatively high.
The Mayura Credit Cardⓘ has a much steeper joining fee and annual fee of Rs 5,999 each. However, its higher reward rate lowers the break-even spend to about Rs 3,99,933 annually. According to the head-to-head data, the Mayura Cardⓘ commands Rs 1,499 more in fees but you only need to spend Rs 1,49,900 more annually to justify this difference, making it more cost-effective at moderate to high spends.
Which One Should You Pick
If you are a frequent traveler who values unlimited domestic lounge access, international lounge visits, and a lower forex markup, the Mayura Credit Cardⓘ is ideal. Its high rewards on travel, dining, and online shopping also make it attractive for premium spenders who can comfortably exceed its fee waiver threshold.
On the other hand, if you want a card with a lower annual and joining fee and benefit from dining or hotel discounts without heavy spending requirements, the American Express Gold Credit Cardⓘ suits you better. It is also a good choice if you prefer a simpler rewards structure without focusing on lounges or forex.
In summary, skip the Amex Goldⓘ if you spend heavily in premium categories or want extensive lounge access. Avoid the Mayura Cardⓘ if you spend below Rs 4 lakh annually or are sensitive to upfront fees.
What to Check Before You Apply
- Confirm whether your typical monthly spend meets the fee waiver threshold to avoid unnecessary costs.
- Understand the redemption process and value of reward points, especially since both cards use points but differ in earning rates.
- Check if forex spend is a significant part of your expenses; the Mayura Cardⓘ offers a much lower forex markup.
- Verify access rules for lounges and golf benefits, including number of visits allowed and participating locations.

Comments
No comments yet
Be the first to share your experience with this card.