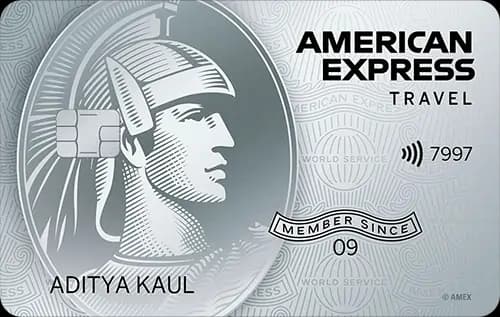
Quick Verdict
- For everyday spend, the City Union Bank CSK Mastercard World Credit Cardⓘ wins with a 1% base reward rate, double that of the Amex card.
- For travel and lounges, the American Express Platinum Travel Credit Cardⓘ offers 8 domestic lounge visits per year and concierge services, which the City Union Bank card lacks.
- The City Union Bank CSK card is cheaper to hold with Rs 4,000 annual and joining fees, compared to Rs 5,000 each on the Amex card.
- Pick the Amex card if you prioritize domestic lounge access and concierge support. Choose the City Union Bank card if you want higher rewards on travel and better forex rates at a lower fee.
Side by Side
| Detail | American Express Platinum Travel Credit Cardⓘ | City Union Bank CSK Mastercard World Credit Cardⓘ |
|---|---|---|
| Annual fee | Rs 5,000 | Rs 4,000 |
| Joining fee | Rs 5,000 | Rs 4,000 |
| Fee waiver on spend | None | None |
| Reward rate | 0.5% (base) | 1% (base), 2% on travel |
| Reward type | Points | Points |
| Domestic lounge | 8 per year, Rs 1.00 lakh quarterly spend gate | None |
| International lounge | None | None |
| Forex markup | 3.5% | 1% |
| Best suited for | Travel, rewards, shopping | Rewards, travel, lounge |
Rewards Compared
Spending Rs 10,000 on the American Express Platinum Travel Credit Cardⓘ earns Rs 50 worth of points at the base reward rate of 0.5%. In contrast, the City Union Bank CSK Mastercard World Credit Cardⓘ delivers Rs 100 on the same spend due to its 1% base rate, making it twice as rewarding for general purchases. When focusing on travel expenses, the City Union Bank card further doubles the return to Rs 200 for every Rs 10,000 spent, highlighting a strong travel rewards advantage. The Amex card does not specify elevated travel category rates but adds value through other travel benefits.
Fees Compared
The American Express Platinum Travel Credit Cardⓘ demands Rs 5,000 each for joining and annual fees, with no fee waiver tied to spending. The City Union Bank CSK Mastercard World Credit Cardⓘ is slightly more affordable at Rs 4,000 for both joining and annual fees, also without any fee waiver thresholds. To cover the Rs 5,000 fee at the base reward rate, the Amex cardholder needs to spend approximately Rs 10,00,000 annually, whereas the City Union Bank cardholder breaks even much earlier at Rs 4,00,000 due to the higher 1% base reward rate. This makes the City Union Bank card more accessible for rewards-driven users who spend less.
Which One Should You Pick
If you are a frequent domestic traveler who values lounge access and concierge services, the American Express Platinum Travel Credit Cardⓘ is tailored for you. Its 8 complimentary domestic lounge visits per year and personal concierge support enhance travel comfort significantly. However, this card is costlier to maintain and requires a high spend to justify the fees.
The City Union Bank CSK Mastercard World Credit Cardⓘ suits users who want better returns on everyday and travel spends at a lower fee. Its 2% travel category rewards and low forex markup of 1% make it a solid choice for international travelers and rewards enthusiasts who do not need lounge access. This card is more budget-friendly with easier fee recovery through rewards.
In conclusion, pick the Amex card if travel perks and lounge access are your priority, and the City Union Bank card if you want higher rewards and lower fees without lounge benefits. Skip the Amex card if you cannot leverage the lounge or concierge features, and skip the City Union Bank card if you need lounge access.
What to Check Before You Apply
- Confirm the Rs 1.00 lakh quarterly spend gate for domestic lounges on the Amex card to ensure you can meet it.
- Investigate the redemption process and value of points for both cards, as points are the reward type.
- Be aware that neither card offers fee waivers based on spend, so fees are fixed.
- Note the forex markup differences: 3.5% for Amex versus 1% for City Union Bank, important for foreign transactions.
- Check the availability and locations of lounges, particularly for the Amex card’s domestic access.

Comments
No comments yet
Be the first to share your experience with this card.